Full Report
What this industry actually sells
Nickel is sold as nickel units — tonnes of contained nickel metal — but almost never as metal. It is sold as ore, as an iron-nickel alloy, or as a wet chemical intermediate, and the form determines who buys it and at what price.
Everything in Indonesia starts with laterite ore, a weathered soil profile with two layers. The upper layer is limonite, typically 1.1%–1.2% nickel, sitting close to the surface. Beneath it is saprolite, at a higher nickel grade [1]. Two ore types feed two completely different process routes, two different products, and two different end markets.
Saprolite goes into a rotary kiln electric furnace (RKEF) — a pyrometallurgical smelter — and comes out as ferronickel (FeNi), raw material for stainless steel [2]. Limonite goes into a high-pressure acid leach (HPAL) autoclave and comes out as mixed hydroxide precipitate (MHP), which is refined into nickel sulphate and cobalt sulphate — the inputs to lithium-ion battery cathodes [3].
The trade classifies the output into two grades. Class 1 is pure metal, above 99.8% nickel, deliverable against the London Metal Exchange contract, plus the nickel salts made from intermediates. Class 2 is the ferroalloys — FeNi and nickel pig iron (NPI) — which cannot be delivered into LME warehouses at all. In 2024 Class 1 was about 26% of global primary nickel production and Class 2 about 74% [4]. That asymmetry is the single most useful fact for reading nickel prices: the LME contract prices roughly a quarter of the market, and the physical market that dominates volume trades on separate indices.
Three specialist terms recur throughout this report and are worth fixing now. MHP contains 20%–25% nickel and 5%–10% cobalt and is produced by HPAL, a process that grew rapidly in Indonesia — 350 kt produced there in 2024. Nickel matte is the competing intermediate, made by converting NPI, at 140 kt in 2024. Both are shipped mainly to China for refining [5]. NPI is the low-grade ferroalloy China developed from 2005 as a cheaper substitute for FeNi: FeNi typically carries more than 20% nickel, NPI only 10%–12%, and Chinese mills prefer NPI because it costs less to make [6].
Who pays, and for what
Demand is not evenly split. Stainless steel took 65% of primary nickel in 2024; batteries 17%; nickel-based alloys 7%; electroplating 5%; alloyed steel and casting 4%; catalysis 2% [7].
Source: Eramet FY2024 Universal Registration Document, main applications of primary nickel, December 2024 [8].
The stainless steel buyer is overwhelmingly Chinese. The International Stainless Steel Forum data cited by Harita puts China at roughly 60% of global stainless production, ahead of Europe (12%), Indonesia (10%), India (8%) and the United States (4%) [9]. On the nickel side, INSG figures cited by Merdeka Battery Materials expect China to account for 63.5% of global primary nickel consumption in 2025, with Indonesia second at 12.2% [10]. One country is the swing consumer for both of nickel's end markets.
Purchasing power sits in a short list of counterparties, and the concentration is visible in the seller's own accounts. Three customers took 70.78% of Harita's FY2025 revenue: Lygend Resources and Technology (44.84%), Glencore International (19.02%) and Ningbo Lygend Wisdom (6.92%) [11]. The pattern repeats across the peer set. Nickel Industries sold all of its 2025 NPI either to Shanghai Decent in China or to stainless mills operating inside the same Indonesian industrial park — PT Indonesia Stainless Steel, PT Qing Feng Ferrochrome and others [12]. Merdeka sells most of its NPI to the Tsingshan group and its affiliates at published NPI prices [13].
Source: FY2025 Annual Report, Note 37 Segment Information — revenue from contracts with customers by location of the customers [14].
Two structural points follow. First, the "Indonesia" line is domestic ore sold to processors, not an end market — the ultimate consumer is still the Chinese mill or the Chinese refinery. Second, the Swiss line is Glencore, a trader rather than a consumer, so a meaningful share of output reaches the end user through an intermediary that holds its own price optionality.
The value chain, and where the margin sits
Because the industry is vertically fragmented across ore, smelting, refining and cathode manufacture, and because several listed players disclose per-tonne economics, it is possible to see roughly where the profit pool sits in a given year rather than guess.
Sources: FY2025 Annual Report, Obi Island integrated value chain [15] [16]; Eramet FY2024, nickel products and supply [17].
The per-tonne disclosures for 2025 are unusually clear. Ore, smelted metal and leached intermediate all sold into the same weak nickel price, and the spread over cash cost differed by a factor of six.
Sources: Merdeka Battery Materials FY2025, mining segment prices and cash costs [18] and RKEF operating data [19]; Nickel Industries FY2025, Hengjaya Mine ore contract price and operating cost [20] and RKEF operations [21]; Huayue Nickel Cobalt MHP sale price and operating cash costs as reported by Nickel Industries [22]. Spreads for the ore rows are price less cash cost; Nickel Industries separately reports adjusted EBITDA of US$9.3 per wmt at Hengjaya. Cash-cost definitions are each company's own and are not audited-comparable.
Sources: Merdeka Battery Materials FY2025 RKEF data [23]; Nickel Industries FY2025 RKEF [24] and HPAL cash costs and byproduct credits [25] disclosures. Derived as realised price less reported cash cost; cash costs exclude by-product credits.
Two mechanics explain the HPAL gap. Cobalt comes out of the autoclave alongside nickel and is credited against cost — Nickel Industries puts the 2025 cobalt by-product benefit at roughly US$1,900 per tonne of nickel, on top of an MHP contract price that rose 8% to US$14,990 per tonne of nickel while NPI prices fell [26]. And HPAL is capital-intensive in a way RKEF is not: Harita's management has put the total investment in the HPL refinery, with a nameplate of 55,000 tonnes of contained nickel in MHP per year, at US$1.2 billion, and described the cash margin on MHP as around 30% [27]. That is roughly US$22,000 of capital per annual tonne of nickel capacity — a barrier that keeps the HPAL field small and, so far, profitable.
The last link is the least visible from Indonesia. Zhejiang Huayou Cobalt, which operates HPAL capacity in Indonesia and refines it in China, reported 2025 revenue of RMB 81.019 billion, up 32.94%, and net profit attributable to the parent of RMB 6.110 billion, up 47.07% — its best result on record. Its Indonesian laterite hydrometallurgical project shipped 236,500 tonnes of MHP, up 30%, and total nickel product shipments reached about 292,500 metal tonnes, up 58.72% [28]. The refining and cathode step, sitting outside Indonesia, grew earnings sharply in a year when the nickel price fell. Huayou itself flags the risk on that side of the chain as phased and structural overcapacity in power batteries and lithium battery materials — the precursor and cathode end of its own chain — rather than in nickel [29].
Market size, and the Indonesian share of it
Global primary nickel consumption was 3.3 million tonnes in 2024, growing 4% on the year, driven mainly by stainless steel; production grew about 4% on the back of Indonesian HPAL projects, leaving the market in surplus [30]. INSG figures cited by Merdeka put primary nickel demand growth at 4.8% in 2024 and a projected 5.7% in 2025 [31]. Demand has not been the problem.
Supply has. The concentration of the supply side into one country over five years is the defining structural fact of this industry.
Source: Eramet FY2024 Universal Registration Document, ore production in thousands of tonnes of nickel content, sourced to INSG, February 2025 [32].
Source: Eramet FY2024 Universal Registration Document, production of finished products, Eramet estimates [33].
Indonesia's finished-nickel output nearly tripled between 2020 and 2024, from 606 kt to 1,780 kt, while world output grew by less than 1,000 kt — meaning Indonesian growth accounted for more than the entire net increase in global supply, with production shrinking elsewhere. NPI's share of global primary nickel production rose to 54% in 2024 from 24% in 2014, and all Class 2 nickel plants in Europe have now stopped, on non-competitive production costs [34].
Harita records Indonesian output of 2.2 million tonnes in 2024, the highest in the world, and attributes the oversupply and the price decline since 2023 to that expansion [35]. The policy that produced it was deliberate: the 2009 Mining Law mandated domestic value addition, the ban on unprocessed ore exports was reinstated in January 2020, and since then all ore mined in Indonesia is destined for domestic use [36] [37].
A caution on the market-size numbers. The filings do not agree on Indonesia's reserve share. Harita's FY2023 report puts Indonesia at approximately 72 million tonnes of nickel, or 52% of a 139-million-tonne world total [38]; Merdeka's FY2025 report puts it at approximately 42% of world reserves and around 50% of world output [39]. Neither states its reserve definition. Stainless-steel production is similarly unreconciled: Eramet reports global output of 61.5 Mt in 2024 [40], while Harita, citing ISSF, puts it at 54–55 Mt [41]. The scope differences are not disclosed; the figures should not be used interchangeably.
How the product is priced
There is no single nickel price. There are at least four, and each stage of the chain is exposed to a different one.
The LME cash price is the headline reference for Class 1 metal. Eramet is explicit that LME volumes and prices "are no longer as representative" of a physical market now dominated by Class 2 nickel for stainless steel, which is why steelmakers have structured supply contracts off the Chinese NPI price index since 2022 [42]. The divergence is measurable: over 2024 the LME price fell nearly 3% to US$15,810 per tonne while the NPI price rose 2% to US$11,635 per tonne [43].
Indonesian ore is priced off a government-set floor. Since 2017 the authorities have published a monthly benchmark, the Harga Patokan Mineral (HPM), calculated as the reference nickel price multiplied by the ore's nickel grade, a correction factor, and one minus the moisture content. For 1.8% nickel ore at 35% moisture, the 2024 floor ranged from US$35 to US$42 per wet tonne, averaging US$38; at 1.6% grade, US$28 to US$34, averaging US$30. A premium on top is negotiated according to local supply and demand [44]. Those premiums are where quota policy shows up in cash: Eramet's Weda Bay joint venture earned premiums close to 50% over the HPM floor in the fourth quarter of 2024, driven by permit-driven supply restriction [45].
MHP is priced as a payability against nickel, with a cobalt credit — which is why MHP realisations rose in 2025 even as the LME fell [46].
The consequence for a reader: a producer's revenue line and the LME chart can move in opposite directions, and a company's product mix determines which of the four prices actually governs its margin.
Where the cycle sits
The current downturn is now in its fourth year, and it is legible in a single series of disclosed annual averages.
Sources: FY2022 Annual Report for the 2016, 2019, 2020 and 2022 averages, rising from US$9,595.2 to US$25,638 per tonne of metal [47]; FY2023 Annual Report for the 2023 average, sourced to World Bank commodity price data [48]; FY2025 Annual Report for the 2024 and 2025 averages, sourced to World Bank Pink Sheet data, December 2025 [49]. 2017, 2018 and 2021 are not disclosed in the corpus and are omitted; the 2022 figure is US$25,638 on the FY2022 report's source and US$25,834 on the World Bank series used from 2023 onward.
The arc: prices peaked at US$33,924 per tonne in March 2022 on the Russia-Ukraine conflict and Chinese restocking, and rose 29% across 2022 as a whole [50]. The 2023 average then fell 17% to US$21,521 per tonne and the price touched US$16,461 in December 2023, with the report naming slowing Chinese demand, excess inventory, weaker EV demand and supply growth "mainly from Indonesia" [51]. Through 2025 prices consolidated in a narrow band, peaking at US$16,066 in March and closing the year near US$14,884 [52]; the monthly series in the same report puts the low at US$14,671 in November [53].
One arithmetic note. The FY2025 report states the 2025 average of US$15,162 was "a 19.0% decrease" on the 2024 average of US$16,814 [54]. Those two figures imply a fall of about 9.8%, which is consistent with the same report's citation of the World Bank's October 2025 estimate of an annual decline of around 9% [55]. The 19.0% appears to be an error in the report; the levels themselves reconcile with the FY2024 disclosure that the LME index fell 21.9% year on year in 2024 [56].
Read across the players, the cycle commentary triangulates rather than diverges. Every large producer in this corpus reported the same three things in 2025: falling realised prices, falling unit cash costs, and a squeeze that landed differently depending on product mix.
Sources: Harita Nickel Annual Public Expose minutes, June 2024 [57] and June 2025 [58], and June 2026 [59]; FY2024 Annual Report [60]; Eramet FY2024 [61] and FY2025 [62] and its 2026 price consensus [63]; Nickel Industries FY2025 RKEF adjusted EBITDA [64]; Merdeka Battery FY2025 [65]; Huayou Cobalt FY2025 [66].
The prior cycle offers a scale reference. Nickel Industries — a pure Indonesian RKEF operator listed in Australia — earned US$110.6m attributable in 2020, US$137.9m in 2021 and US$159.0m in 2022, then US$121.6m in 2023, before swinging to losses of US$168.6m in 2024 and US$57.1m in 2025 [67]. The same business model produced a swing of more than US$300m between the top and the trough of this cycle.
The forces that divide this arena
Sources: MoEMR Regulation 17/2025 as summarised in the FY2025 Annual Report [68]; Nickel Industries FY2025 on RKAB delay [69] [70]; royalty regime under GR 26/2022 [71] and GR 19/2025 [72], with amounts charged from Note 30 [73]; customer concentration from Note 29 [74]; LFP share as put to management at the 2026 public expose [75]; NPI share [76]; sulphur disruption [77]; B40 and royalty cost effect [78]; assurance standards [79] [80].
The quota is the industry's supply valve
Because Indonesia is the marginal supplier of the world's nickel, the Indonesian permit calendar is now a global price variable. The mechanism is the Rencana Kerja dan Anggaran Biaya — RKAB — an annual work plan and budget that fixes how much ore each licence holder may produce and sell. Ministerial Regulation 17/2025 cut its validity from three years back to one, explicitly to "strengthen Government control over mining activities" and balance domestic needs against exports [81].
An annual permit is an annual outage risk. Nickel Industries' Hengjaya mine undertook no mining activity from mid-September 2025 until its extension was granted on 12 December, incurring US$21.3 million of standby charges and taking segment adjusted EBITDA down to US$91.6m from US$100.9m [82] [83]. Its limonite supply contract to a domestic trader lapsed entirely from October 2025 because the approved RKAB would not cover it, and resumed in December at a reduced 250,000 wmt per month [84].
The 2026 tightening is larger in scale than anything in the prior three years.
Indonesia nickel RKAB 2026 (Mt, midpoint)
Indonesia nickel RKAB 2025 (Mt, midpoint)
Weda Bay initial 2026 RKAB filing (Mwmt)
Sources: FY2025 Annual Report, which sets the 2026 nickel RKAB at approximately 260–270 million tonnes against 2025 production of around 364–379 million tonnes (midpoints shown) [85]; Eramet FY2025, reporting notification of an initial 2026 RKAB filing for 12 Mwmt at PT Weda Bay Nickel, of which 9 Mwmt for external sale, with the intention to request an upward revision [86].
The Weda Bay figure deserves emphasis because of what the same mine was permitted to do the year before: the RKAB issued in October 2024 limited its production and sales to 32 Mwmt in 2025, of which 3 Mwmt went internally to the NPI plant — implying roughly 29 Mwmt for external sale [87]. An initial 2026 filing of 12 Mwmt, 9 Mwmt of it for external sale, at the world's largest nickel mine is a very different starting point, whatever the eventual revision. Eramet's own 2026 expectation follows directly: domestic Indonesian ore prices should benefit from premiums higher than 2025, supported by tension on Indonesian ore supply [88].
Harita's own framing is consistent: the government introduced quota adjustment as a way to maintain market balance and price stability, the discussion began to move market expectations in the fourth quarter of 2025, and prices briefly held around US$16,000 per tonne in early January 2026 — a move management characterises as sentiment-driven, not yet a change in the fundamental surplus [89].
The state's take has been repriced
Until April 2025 the royalty on nickel ore sales was a flat 10%, or 2% for ore below 1.5% nickel content, under Government Regulation 26/2022 [90]. Government Regulation 19/2025, effective 11 April 2025, replaced it with a sliding scale of 14% to 19% indexed to the global reference price [91]. The effect landed inside cost of goods sold within the same year: Harita's royalty charge rose to Rp1,337bn plus a Rp173bn adjustment in respect of the prior year, from Rp838bn in FY2024 — with under nine months of the new rate applying [92].
Two further state levers appeared in 2026. A new HPM benchmark formula, implemented in mid-April 2026, extends the priced value to associated minerals — nickel, cobalt, chromium and iron — rather than nickel alone; and a single-gate export system under Danantara Sumber Daya Indonesia came into force in June 2026, aimed at under-invoicing and transfer pricing [93]. Separately, mining land clearings without a forest-area use permit became subject to administrative fines set by ministerial decree in December 2025 [94]. Taken together, the state has moved in one direction: a larger and better-monitored share of the value the resource produces.
The players that matter
Six names dominate the Indonesian nickel arena in this corpus. Four are genuinely comparable and are set out below; two require caveats. INCO (PT Vale Indonesia) and ANTM (PT Aneka Tambang) are named as peers in the run's screen but no filings for either are present in the corpus, so neither can be benchmarked here. Eramet is included because it owns the world's largest nickel mine through PT Weda Bay Nickel, but it is a manganese-led diversified group and its consolidated figures are not a nickel read-across.
Sources: Harita Nickel FY2025 Annual Report, revenue Rp29,633bn, gross margin 32.7%, profit for the year Rp10,970bn [95]; Merdeka Battery FY2025 consolidated statement of profit or loss [96] and segment review [97]; Nickel Industries FY2025 consolidated statement of profit or loss, with the profit line being the loss attributable to owners [98]; Huayou Cobalt FY2025 [99]; Eramet FY2025 adjusted revenue and net result attributable to the group [100]. Figures are each company's reported currency and are not FX-converted; gross margin is not disclosed on a comparable basis for Huayou or Eramet and is shown as blank. Nickel Industries growth is derived from reported FY2025 and FY2024 revenue.
The table carries one comparability warning worth stating plainly. Harita's reported revenue excludes its HPAL refineries and its newest RKEF smelter entirely: HPL, ONC and KPS are equity-accounted associates, and their contribution arrives as share of profit — Rp4,091bn in FY2025, against Rp2,013bn in FY2024 [101]. Merdeka and Nickel Industries consolidate more of their processing chain. Revenue and gross margin are therefore not measuring the same span of the value chain across these companies.
Capacity, not revenue, is the better scale comparison in this industry. Harita ended 2025 with three RKEF smelters at roughly 240,000 tonnes of contained nickel in FeNi per year and six HPAL lines at approximately 120,000 tonnes of nickel-cobalt compound metal, including about 14,250 tonnes of cobalt; it sold 188,581 tonnes of nickel in FeNi and 130,551 tonnes of MHP and nickel sulphate, up from 102,054 tonnes in 2024 [102] [103]. Nickel Industries produced 124,966 tonnes of nickel metal in NPI [104], and Merdeka's RKEF fleet produced 73,871 tonnes of nickel equivalent [105]. Harita's mining base sits on estimated reserves and resources of 310.8 million wet tonnes, 215.1 Mt of it limonite and 95.7 Mt saprolite [106].
A disclosure gap worth naming. Merdeka and Nickel Industries both publish cash cost per tonne of nickel on an explicitly stated industry convention [107] [108]. Harita does not publish a cash cost per tonne in any document in this corpus; it describes itself as holding "competitive cash costs among industry peers" and as aiming to be "the lowest cash cost producer" without quantifying either [109] [110]. A like-for-like cost-curve position for Harita cannot be established from the primary record.
Three currents running through the arena
Profit is migrating up the chain, toward the ore
For most of the downstreaming decade the story ran the other way: value was supposed to move downstream, from ore into metal. In 2025 and the first half of 2026 the disclosed economics point upstream. Limonite ore earned a US$5.3 per wet tonne spread at Merdeka's SCM mine while saprolite earned US$1.9 [111]; Nickel Industries saw its saprolite contract price fall 30% while limonite rose 31%, on higher demand from Indonesian HPAL projects [112].
Harita's own segment accounts show the same shape. In the first half of 2026 its nickel mining segment produced Rp2,941bn of gross profit on Rp8,957bn of revenue — a 32.8% margin — while nickel processing produced Rp2,173bn on Rp10,431bn, a 20.8% margin [113].
Sources: Q2 FY2026 interim consolidated financial statements, Note 34 Segment Information — 1H26 segments [114] and the unaudited 1H25 comparatives [115]. Figures are before eliminations.
Management's own account of why is worth recording: the mining segment grew because the new KPS smelter demands more ore, the mining margin is higher in percentage terms because production costs are lower, but in absolute terms mining remains the smaller contributor because the price per tonne of ore is far below the price per tonne of processed product [116]. If quota tightening keeps ore scarce relative to smelter capacity, that relationship is the one to watch.
The two process routes have decoupled
RKEF and HPAL now sit in visibly different places. RKEF sells into stainless steel at a price index that has been flat to falling, against cash costs that have proved sticky — Nickel Industries cut RKEF cash costs only 1.8% in 2025 while its sale price fell 8.8%, and notes that group RKEF cash costs remain at 2021 levels [117]. HPAL sells into the battery chain with a cobalt credit and, at Huayue, ran 42% above nameplate capacity in 2025 [118].
Harita frames the two routes as complementary rather than competing: RKEF as the more stable, lower-cost structure that acts as a margin stabiliser when prices are pressured, HPAL as the higher-value-added exposure that is more sensitive to input prices such as sulphur but benefits from cobalt by-product credits [119] [120]. The 2025 peer numbers put more of the margin in the second of those.
The counterweight is chemistry. LFP batteries contain no nickel at all, and were put to Harita's management in June 2026 as accounting for roughly 80% of Chinese EV battery installations. Management's answer is segmentation rather than displacement: nickel chemistries serve mid- to upper-class vehicles requiring higher energy density in Europe and the United States, where charging infrastructure is sparser, while LFP suits China's denser charging network — and NCM cells are more recyclable into black mass and back into nickel sulphate [121]. Harita's FY2025 report makes the same argument, calling the battery-chemistry contest "market segmentation rather than a structural shift in global nickel demand" [122]. The record supports that the two chemistries serve different segments; it does not settle how those segments' relative sizes evolve.
Harita's own two estimates of the battery share of nickel demand also differ within the same FY2024 report: one section puts it at around 14% of total nickel production, up from 3%–4% five years earlier, with stainless steel falling from about 70% to 65% [123]; another, citing Mining.com, puts it at nearly 17% in 2023, up from 3% in 2020, with stainless steel down from 71% to 64% [124]. The direction is unambiguous; the level is not.
Cost, not price, is where 2026 is being decided
Every producer in this corpus reported the same cost architecture under pressure. Sulphur is the critical HPAL reagent, and its price rose through 2025, partly offset by higher cobalt as a by-product credit [125]. Then in 2026 the Strait of Hormuz closed. Harita reports minor disruption to sulphur distribution, says it anticipated the trend from the end of 2025 by holding three to four months of site stock, and describes a diversified supplier base not dependent on the Middle East [126]. Eramet, independently, flags the same event — military operations from late February 2026, tension in the Strait of Hormuz, higher energy and freight costs, and a price surge in certain raw materials, sulphur among them, described in its French-language report as an input used in several industrial processes relevant to its markets — as a new source of uncertainty for 2026 [127].
On the mining side, Merdeka attributes higher saprolite cash cost directly to increased royalty and to the mandatory B40 biodiesel blend [128]. Producers are responding by internalising reagents: Harita is building a quicklime plant specifically to make, rather than buy, a principal HPAL input [129]. The plant is held through PT Cipta Kemakmuran Mitra; building construction completed in the first half of 2026, production lines are still going up, and the stated project investment is around US$70 million [130].
Meanwhile the price consensus for 2026 sits at roughly US$16,450 per tonne on the LME per Eramet's mid-March 2026 reading [131] — above the 2025 average but below 2024. With prices range-bound, the variables that move producer margins in 2026 are quota volume, royalty, reagent cost and utilisation, not the LME print.
What the record does not settle
Four things this corpus cannot resolve, stated so they are not mistaken for gaps in the analysis.
Cost-curve position. With no per-tonne cost disclosure from Harita, its claimed low-cost position cannot be tested against the peers that do publish one [132].
Market share. No document in the corpus states any producer's share of Indonesian or global nickel supply on a consistent basis. Capacity and volume comparisons above are the closest available substitute.
The size of the quota cut in practice. The 2026 RKAB figures are national ceilings and initial filings, both subject to revision — Eramet explicitly states its intention to seek an upward revision [133], and Nickel Industries received an increase to 14.3 million wmt for 2026 after year end [134]. Announced quotas and realised production have not historically been the same number.
Guidance. Harita does not publicly disclose financial targets, citing the highly competitive market environment [135]. It guides on volume only: for 2026 it expects nickel ore sales volumes about 24% higher before eliminations on completion of the PT KPS phase-three RKEF lines, with ferronickel volumes broadly flat, and states that its financial performance depends heavily on the nickel price and on the associates PT HPL, PT ONC and PT KPS [136]. There is no margin, price or earnings guidance against which the industry outlook above can be measured.
For how these forces show up in the named rivals' record against this company, see Competition; for how Harita itself arrived at this position, see History.
The contested ground
Harita Nickel sells four things, and each one meets a different set of rivals. Laterite ore — 30.59 million wet tonnes of it in 2025, split 12.09 million wmt saprolite and 18.50 million wmt limonite — never reaches an outside buyer: the Group states in its own accounts that it "exclusively sells nickel ore to related parties for further processing" [1]. Ferronickel from three RKEF smelters with roughly 240,000 tonnes a year of installed nickel-in-FeNi capacity goes to stainless-steel mills. Mixed hydroxide precipitate and nickel sulphate from two HPAL refineries with roughly 120,000 tonnes a year of nickel-cobalt compound capacity go to the battery chain [2]. An industrial estate on Obi Island houses the whole thing.
The evidence base for this tab has an unusual shape. Harita's own filings name no competitor — not Vale Indonesia, not Aneka Tambang, not Weda Bay, not Tsingshan. The word "competitive" appears in its marketing section as a description of its own pricing posture, not as a map of who it is pricing against [3]. So the rival record here is built almost entirely from the rivals' own annual reports: PT Merdeka Battery Materials (MBMA), Nickel Industries Limited (NIC), Zhejiang Huayou Cobalt (603799) and Eramet SA. Two names in the staged peer set — PT Vale Indonesia and PT Aneka Tambang — have no documents in this corpus, so they appear below only where a rival's filing describes them. The arena's structure and cycle belong to Industry; the full source shelf, including the peer passages reproduced as filed, sits in Competitors.
Sources: Harita FY2025 Annual Report, Operational Performance Review [2]; MBMA FY2025 Annual Report, Manufacturing Assets [4]; Nickel Industries FY2025 Annual Report, Review of Operations [5]; Huayou FY2025 Annual Report, Business Review [6]; Eramet 2024 Universal Registration Document, Nickel Activity [7].
The comparator set
Four rivals were confirmed against their own filings rather than accepted from the screen.
MBMA is the closest structural analogue: an IDX-listed group running a laterite mine (SCM, 51% held, 21,100 hectares), RKEF smelters at IMIP and an HPAL-to-MHP build-out, all under the same Indonesian permitting regime [8].
Nickel Industries is ASX-listed but wholly Indonesia-operating, and runs the same product straddle: RKEF nickel units plus a growing HPAL position, fed by its own mine. It describes itself as "a globally significant, low-cost producer of nickel pig iron (NPI)" that has "acquired interests in high pressure acid leach (HPAL) projects, producing mixed hydroxide precipitate (MHP) for use in the electric vehicle (EV) supply chain" [5]. It is by some margin the most disclosure-rich comparator.
Huayou Cobalt operates the largest Indonesian HPAL position, Huayue and Huafei, and is also the refiner and cathode-maker at the far end of the chain. It is a like-for-like rival only in nickel: the group also sells cobalt, copper, lithium, precursors and cathode materials, and reported nickel product revenue of RMB 25,895m and nickel intermediate revenue of RMB 11,781m out of RMB 81,019m total in 2025 [9].
Eramet is a partner, not an operator: it holds 38.7% indirectly in PT Weda Bay Nickel and takes an offtake of the NPI plant's output. Its economics are diluted by manganese, mineral sands and lithium, so only the nickel activity is used here, and even that is reported on an adjusted basis that folds in its share of an equity-accounted joint venture [10].
Huayou and Eramet run models different enough to keep out of like-for-like economics: Huayou is a diversified battery-materials group whose Indonesian nickel plants are one input among many, and Eramet consolidates none of Weda Bay.
Indonesia is the arena
Every rival above competes in one country, and the country's weight has roughly doubled in five years. Eramet's registration document reproduces the INSG country tables: Indonesian ore production rose from 767.0 thousand tonnes of nickel content in 2020 to 2,328.0 in 2024 against a world total of 3,776.4, and Indonesian finished primary nickel rose from 606.2 to 1,779.8 thousand tonnes against a world total of 3,392.7 [11].
Source: derived from the INSG ore-production table and the Eramet finished-products table, Eramet 2024 Universal Registration Document [11].
The same document draws the line that separates Harita's two product families. Class 1, pure metal and the sulphates made from intermediates, was "around 26% of total primary nickel production" in 2024; Class 2 ferroalloys, NPI and ferronickel, "around 74%". Within Class 1, HPAL in Indonesia produced 350 kt of MHP in 2024 against 140 kt of nickel matte, and "these two intermediates are mainly refined in China" [12]. Eramet also names the dominant Class 2 player, and it is not a listed company: "NPI represents approximately 90% of Class 2 nickel, and our partner Tsingshan at PT Weda Bay Nickel is the leading player in this market" [13].
Scale and profit, side by side
Peer financial series are not available in this run's structured data — its own coverage note records zero of six peers loaded — so the figures below come from each rival's audited statements, in the currency that rival reports.
Sources: Harita FY2025 Annual Report, Note 37 Segment Information [14]; MBMA FY2025 Annual Report, Financial Highlights [15]; Nickel Industries FY2025 Annual Report, Note 24 Segment Information [16] and Review of Operations [5]; Huayou FY2025 Annual Report, Major Accounting Data [17]; Eramet 2024 Universal Registration Document, Nickel Activity Key Figures [10].
Currencies and consolidation perimeters differ, so the table records levels rather than a ranking. What it shows without ambiguity is that in 2025 the three Indonesia-centred producers moved in different directions. Harita's revenue rose 9.9% and profit for the year rose 42.2%; MBMA's revenue fell 22.2% while profit rose 26.4%; Nickel Industries' revenue fell 5.5% and its loss narrowed from $189.8m to $41.2m. Harita's reported profit also carries a large equity-accounted component: Rp4,090,748 million of share in associates' profit in 2025 against Rp2,012,894 million in 2024, from HPL, ONC and KPS, none of which it consolidates [18].
Where the margin sits in the chain
Three of the four rivals publish segment splits, and each one puts the margin in the same place: the mine, not the smelter.
Sources: derived from Harita FY2025 Annual Report, Note 37 Segment Information [14] and [19]; Nickel Industries FY2025 Annual Report, Note 24 Segment Information [16] and [20]; MBMA FY2025 Annual Report, Segment Performance [8].
The three measures are not the same measure. Harita reports gross profit by segment, Nickel Industries reports adjusted EBITDA by segment, and MBMA reports profit for the year by segment, a figure struck after depreciation, interest and tax. The comparison is therefore between shapes, not levels: in each of the three, the mining segment earns a multiple of the processing segment's margin on the same revenue. Harita's management said as much when asked directly, noting that "in percentage terms, the margin of the nickel mining segment is indeed higher than that of the nickel processing segment, given the relatively lower production costs in the mining segment", while adding that in nominal terms mining remains the smaller contributor because "the selling price per ton of nickel ore is significantly lower than the selling price of nickel processing products" [21].
The volume race
Harita's ore book has quadrupled in four years, and it moved because its own downstream plants asked for more feed.
Sources: Harita FY2023 Annual Report, Operational Performance Review [22]; FY2024 Annual Report, Board of Directors Report [23]; FY2025 Annual Report, Operational Performance Review [24].
Sources: Harita FY2024 Annual Report, Operational Performance Review [25]; FY2025 Annual Report, Operational Performance Review [24] and [26].
Against that ramp, the two listed Indonesian RKEF rivals went backwards in 2025. Nickel Industries produced a record 1,055,658 tonnes of NPI but only 124,966 tonnes of contained nickel, below 2024's 127,261 tonnes because ore grade fell from 12.2% to 11.8% [27]. MBMA produced 73,871 tonnes of nickel in NPI and LGNM against 82,161 in 2024, after taking smelters down for scheduled maintenance and revising NPI guidance to 70,000–80,000 tonnes [4].
Sources: Harita FY2025 Annual Report, Operational Performance Review [24]; Nickel Industries FY2025 Annual Report, RKEF Operations [27]; MBMA FY2025 Annual Report, Manufacturing Assets [4] and FY2024 Annual Report, Manufacturing Assets [28].
Harita's FeNi is not the same product as its rivals' NPI — ferronickel carries a higher nickel grade — so the chart compares contained nickel units competing for the same stainless-steel demand, not identical goods.
Intermediates and the MHP supply base
The HPAL side is where capacity is being added fastest, and where the disclosures overlap in a way that makes double-counting easy.
Sources: Harita FY2025 Annual Report, Operational Performance Review [24] and [26]; Nickel Industries FY2025 Annual Report, HPAL Operations [29]; MBMA FY2025 Annual Report, President Director Report [30]; Huayou FY2025 Annual Report, Business Review [6] and FY2024 Annual Report, Business Review [31]; Eramet 2024 Universal Registration Document, Nickel Activity [7].
Two cautions the table cannot carry. Huayue appears twice in the public record — Huayou consolidates it, and Nickel Industries reports its own 10% share of the same plant — so adding the two disclosures together counts the same tonnes twice. And Huayou's 235,000-tonne 2025 MHP shipment figure is not stated on the same basis as its predecessor: the prior-year report gave "the shipment of nickel intermediates was nearly 230,000t", a wider product label, so the two years are not a clean like-for-like [6] [31].
Set against 350 kt of Indonesian MHP produced in 2024 on Eramet's count [12], the named nameplate already running or under construction in the table above adds several hundred thousand tonnes more. No participant in this corpus publishes a market share for MHP, and none is calculated here.
The ore book
Ore is where the rivals meet most directly, because four of them mine laterite in the same country under the same annual quota.
Sources: Harita FY2024 Annual Report, Board of Directors Report [23] and FY2025 Annual Report, Operational Performance Review [24]; Eramet 2024 Universal Registration Document, Weda Bay operational indicators [7]; MBMA FY2024 Annual Report, Mining Segment [32] and FY2025 Annual Report, Comparison of Target and Realisation [33] and Mining Segment Production and Sales [34]; Nickel Industries FY2025 Annual Report, Mining Operations [35].
Weda Bay's 2024 figure is at 100% of a mine Eramet does not consolidate, and its 2025 line is a permit ceiling rather than a realised volume: Eramet stated that production and sales "will be limited to 32 Mwmt in 2025 (including 3 Mwmt internally to the NPI plant)" [7]. On the record as filed, Harita's own ore volume passed Weda Bay's 2024 external sales during 2025, and it did so without selling a tonne to a third party.
Cost and price lines rivals publish
Harita publishes no cash cost. Its FY2025 annual report describes "the Company's position as a nickel producer with competitive cash costs among industry peers" [2], and management repeated the claim at the 2025 public expose while describing efficiency work including a captive quicklime plant, PT CKM, because to date "we buy the quicklime from the external party at a higher cost" [36]. Harita's record contains one quantified cost placement, and it is third-party and three years old: the IPO prospectus cites AME placing the Stage I HPAL Project's estimated 2022 cash cost at the lower end of the first quartile of the 2022 global nickel smelter cash-cost curve [37]. Two rivals publish current numbers.
Sources: Nickel Industries FY2025 Annual Report, RKEF Operations [27], HPAL Operations [29] and Mining Operations [35]; MBMA FY2025 Annual Report, Manufacturing Assets [4] and Mining Segment Production and Sales [34]; Harita blended ore price derived from FY2025 Annual Report, Note 37 Segment Information [14] and Operational Performance Review [24].
The cost definitions are each company's own and are not reconciled to one another: MBMA defines RKEF cash cost as direct cost per tonne of nickel produced including transport, and Nickel Industries reports cash costs excluding by-product credits. Peer figures stay in the currency each rival reports; Harita's derived ore price is in rupiah per wet tonne and is not directly comparable to the dollar rows above it. The cross-cutting fact is the spread. On Nickel Industries' 2025 figures the RKEF line earned roughly $1,100 per tonne of nickel between cash cost and realised price, while the HPAL line earned roughly $7,200 — a gap the company attributes in part to a cobalt credit of about $1,900 per tonne of nickel and to MHP contract prices rising 8% to $14,990/t Ni [29].
Ore pricing moved in two directions at once
The clearest disclosed price movement in the peer set is the divergence between the two ore types Harita sells.
Source: Nickel Industries FY2025 Annual Report, Mining Operations [35].
Nickel Industries attributes the split to two different forces: "the saprolite contract price decreased 30%, driven by a reduction in the local premium", while "the limonite contract price increased 31% due to the increased demand for limonite ore from Indonesian HPAL projects" [35]. Harita's own 2025 mix shifted the same way, limonite growing to 18.50 million wmt to feed a full year of PT ONC and saprolite to 12.09 million wmt to feed the new PT KPS lines [24]. Because it sells only within its own group, none of that limonite premium is struck at a third-party price.
The two mines that do sell ore externally realised very different limonite prices in 2025: $23.6/wmt at Hengjaya against $15.3/wmt at SCM [35] [34]. Both are struck off the same government HPM benchmark; grade, moisture and haulage distance account for the rest, and neither company reconciles the two.
The quota that binds everyone
The one constraint every rival in this corpus names is the RKAB, Indonesia's annual work-plan-and-budget approval. Its bite is documented, not hypothetical.
During the year, the Company experienced substantial downtime and $21.3 million in standby charges at the Hengjaya Mine as the RKAB extension was not granted until 12 December 2025 and consequently the Adjusted EBITDA decreased from $100.9m in 2024 to $91.6m in 2025.
— Nickel Industries, FY2025 annual report [35]
Eramet recorded the same mechanism a year earlier, reporting that "PT WBN's mining operations were constrained by the RKAB granted by the Ministry of Mines, limiting annual production and sales for the 2024-2026 period", with external sales down 9% and the mine benefitting from high-grade premiums "close to 50%" in the fourth quarter as domestic supply tightened [7].
Huayou, a buyer rather than a miner, states the consequence at the level of the world price: "At the end of the year, it rebounded significantly under the expectation of the tightening of Indonesia's RKAB quota policy. From the supply side, global nickel production was highly concentrated in Indonesia. Its policy trends such as the RKAB quota have become key variables affecting the global nickel supply and demand balance" [38]. Harita's account of the same quarter is consistent: prices peaked at $16,066 per MT in March 2025, weakened through November, and recovered to about $14,884 per MT in December as quota-adjustment talk began to move expectations [39].
Rivals on the record
In date order, the peer filings describe a market that added supply faster than it added demand.
MBMA, FY2025 annual report. "In 2025, the global nickel market was dominated by a surge in production, particularly from Indonesia and China, resulting in a significant surplus. Although demand for stainless steel and EV batteries continued to grow, the increase in demand was not proportional to the rise in supply, leading to downward pressure on nickel commodity prices throughout the year" [40].
Huayou, FY2025 annual report. "According to INSG, the global nickel supply was 3.81 million tons and the demand 3.6 million tons in 2025" — a surplus of roughly 210,000 tonnes, with prices "mainly fluctuating within the bottom range" [38].
Huayou on its Indonesian build. "The two HPAL projects, Huayue and Huafei, maintained stable and exceeded production capacity, achieving an annual MHP shipment of 235,000 tons, a 30% increase compared to the same period of the previous year. The Pomalaa HPAL project with an annual output of 120,000 tons of nickel metal progressed steadily as planned". The same passage records a whole-chain agreement with ANTAM and IBC, one of the few places a Harita rival names an Indonesian state producer as a partner rather than a competitor [6].
MBMA on its own HPAL start. "During 2025, PT ESG produced 25,994 tons of nickel in MHP" after receiving its industrial licence in February 2025, with MNEM running at 25,000 tonnes a year and SLNC "with a planned capacity of 90,000 tons of nickel in MHP per year, was currently under construction and targeted to begin operations in 2026" [30].
Eramet on where the ore goes. Weda Bay is "positioned in the first quartile of the cost curve" and supplies saprolite and laterite ore to local Class 1 and Class 2 nickel producers, with an ambition agreed with Tsingshan to raise the mine toward roughly 60 Mwmt a year [41]. The first-quartile claim is Eramet's own positioning statement, unquantified in the document.
Harita's counterpart commentary defends the nickel-battery chemistry rather than its own position. Asked at the 2026 public expose why investors should expect MHP demand to absorb Indonesia's HPAL build-out when LFP holds about 80% of Chinese EV battery installations, management argued that "these two battery types essentially serve distinct market segments", with nickel-based cells in longer-range mid-to-upper-class vehicles in Europe and the United States, and added a recycling argument: used NCM batteries "can be reprocessed into black mass or black powder for further processing into nickel sulfate" [42].
The sales book and its concentration
Harita's processing revenue has gone to a very small number of buyers since before the IPO, and one of them is also its joint-venture partner.
Sources: Harita FY2022 Annual Report, Note 26 Revenue from Contracts with Customers [43]; FY2024 Annual Report, Note 30 [44]; FY2025 Annual Report, Note 29 [45].
In FY2024 the three named buyers — Lygend Resources and Technology, Ningbo Lygend Wisdom and Glencore International — took Rp23,164,020 million, exactly the whole of the nickel processing segment's external revenue, or 85.90% of group revenue [44]. In FY2025 the same three took Rp20,975,164 million, or 70.78% of group revenue, against processing revenue of Rp22,454,667 million — the first year in the disclosed record in which buyers outside the named three account for a measurable slice of processed-product sales [45]. Within the three, the mix moved: Glencore rose from 11.27% to 19.02% of group revenue while Ningbo Lygend Wisdom fell from 22.52% to 6.92%.
The counterparty relationship runs both ways. Lygend is not only Harita's largest customer but its joint-venture partner across the downstream: the IPO prospectus records a 45.10% Harita interest in HPL, a Lygend subsidiary, and names Lygend as the main ferronickel customer under an offtake agreement with MSP [46].
Switching terms in the contracts
The prospectus is the only place in this corpus where contract duration, minimum volume, pricing formula and renewal are set out. What it describes is a chain of long-dated, priority-right agreements between parties that also own each other.
Sources: Harita IPO Prospectus 2023, Customers of the Mining Business [47]; Other Material Agreements [48] and [49].
Three features of that table govern how easily anything in Harita's chain could be replaced.
First, price is not negotiated. Ore transferred to MSP, HJF and HPL is priced off the government's mandatory minimum reference price, adjusted by formula for nickel grade and a product correction factor [50]. The same benchmark sets MBMA's ore realisations and Hengjaya's contract prices [34]. Competition on ore price is therefore bounded by regulation for every Indonesian participant; the variance shows up in grade, moisture, haulage and local premium.
Second, duration is long and the dates are known. The HPL ore supply runs to 31 December 2030 and the HJF supply to December 2032, both with minimum annual quantities [47]. The prospectus ties the first of these to the mine plan, noting that limonite stockpile reclamation is expected to continue to 2038 while the HPL supply agreement runs to December 2030 [37]. The ferronickel offtake runs 60 months with 24-month extensions available by consent and no cap on how many times.
Third, the shareholder agreements convert commercial preference into a standing right. In each of the KPS, ONC, HJF, OSS and DCM joint ventures, the shareholders agreed to give priority to Harita or its affiliates to supply ore, and the shareholders hold first priority to buy the plant's output. Those agreements remain in force until they are terminated by agreement of the parties, until all shares held by the relevant shareholders transfer to a third party, or until a binding order is made to wind the joint venture up [48].
The visible contrast in the peer set is how quickly an ore contract can stop when the quota moves. Nickel Industries disclosed that its subsidiary supplied limonite to a third-party trader "pursuant to a sales contract providing for the delivery of 850,000 wmt of limonite ore per month for the period from January to September 2025. No deliveries were made from October 2025 as the contract could not be continued due to limitations under the approved RKAB", and that supply resumed in December under a new contract at 250,000 wmt per month [51]. Its internal saprolite flows, by contrast, run "under a series of oftake agreements to supply between 80,000 to 100,000 wmt per month to each entity" — the same captive structure Harita uses [51].
Payment terms on Harita's processed sales are short, with no long-dated receivable lock: "The term of payment is generally due within 1 to 35 days upon fulfillment of the performance obligation. For export sales, the Group requires payment against the presentation of documents of title" [45].
What the record does not contain
Four gaps limit what can be drawn from the evidence above, and each is a gap in the filings rather than in the search.
Harita publishes no cash cost per tonne on any current definition, so its repeated low-cost-producer positioning [36] cannot be checked against the rival cost lines above. It also states plainly that it withholds targets: "Given the highly competitive market environment, the Company does not publicly disclose its financial targets" [52].
No participant publishes a market share for MHP, for ferronickel, or for Indonesian ore, and the two share claims that do appear in the peer set disagree with each other and with the INSG tables. MBMA's industry overview carries both "more than one-third of the global nickel supply" and "around 50% of total global nickel output" on the same page [53], against Eramet's INSG-sourced 62% of ore and 52% of finished primary nickel for 2024 [11].
The two Indonesian rivals with the closest ore-and-ferronickel overlap, PT Vale Indonesia and PT Aneka Tambang, have no documents in this corpus. They appear only at second hand, in Huayou's account of its whole-chain agreement with ANTAM and IBC [6].
And the associates that generate a third of Harita's pre-tax profit — HPL, ONC and KPS — publish no standalone accounts here. Their contribution is visible only as an equity-method line: Rp2,306,536 million from HPL, Rp1,462,710 million from ONC and Rp311,891 million from KPS in 2025 [18]. Nickel Industries' disclosure of the Huayue plant's cash cost, realised price and cobalt credit [29] is the closest available proxy for what sits inside that line.
The record in one view
PT Trimegah Bangun Persada Tbk was incorporated on 6 September 2004 and began mining nickel laterite on Obi Island in 2010 [1]. The dated record that follows covers that span, but it is dense only from 2016 onward, when the first ferronickel smelter came on line, and it becomes a public record on 12 April 2023, when the company listed 7,997,600,000 new shares on the Indonesia Stock Exchange at Rp1,250 apiece [2].
Three breaks separate the periods. The first is 2021, when the associate PT Halmahera Persada Lygend started Indonesia's first high-pressure acid leach refinery and the company acquired a battery-materials product line [3]. The second is 2023, when the listing and the eight-line PT Halmahera Jaya Feronikel smelter arrived within weeks of each other and revenue rose 149.4% [4]. The third is 2024–2025, when reported capital spending fell to roughly an eighth of its 2022 level and the company spent its cash buying stakes in refineries it did not build [5]. This tab records those events, the promises attached to them, and what the filings later reported. It does not weigh them.
Net IPO proceeds (Rp bn)
Dividends declared FY22-FY25 (Rp bn)
Buyback executed to Dec 2025 (Rp bn)
New shares issued since listing
Sources: IPO proceeds and use-of-proceeds table, FY2025 Annual Report [6]; dividend history and buyback realization, FY2025 Annual Report [7] [8]; FY2025 dividend as declared 30 June 2026, 1H26 results presentation [9]; share listing chronology, FY2025 Annual Report [10].
Dated beats, 2004 to 2026
Sources: founding deed and 2010–2024 milestone timeline, corporate website [11]; the 2011 Kawasi mining area and the 2016–2020 smelter and joint-venture milestones, FY2023 Annual Report [12]; HPL start-up [13]; KPS and OSS shareholders agreements, IPO prospectus [14]; IPO effective date and offer price, FY2022 Annual Report [15] and FY2023 Annual Report [16]; 2023 project milestones, August 2023 investor presentation [17]; 2024 EGMS and AGMS outcomes, FY2024 Annual Report [18] [19]; the December 2024 purchase of an additional equity ownership in ONC from Li Yuen, FY2025 Annual Report [20]; the June 2025 increase in share ownership to 40% bought from PT Harita Jayaraya [21]; the 2025 share buyback realisation [22]; KPS phasing, April 2025 and May 2026 presentations [23] [24]; the end-February 2026 escalation date, FY2025 Annual Report [25]; sulfur disruption and 1H26 project status, 2026 public expose and 1H26 presentation [26] [27]; FY2025 dividend [28].
The reported result over the same span is a step change concentrated in 2023 and a slower climb afterwards.
Sources: FY2021 revenue as reported in the FY2022 Annual Report [29]; FY2022 and FY2023 revenue and profit for the year, FY2023 Annual Report [30]; FY2025 revenue, profit for the year and share of associate profit, FY2025 Annual Report [31]; FY2022–FY2024 profit for the year per audited consolidated financial statements as reported. FY2021 profit for the year is not disclosed in the corpus filings and is left blank.
What the listing raised and where it went
The April 2023 offering raised Rp9,997.0 billion gross. Offering costs of Rp289.0 billion left Rp9,708.0 billion net. The prospectus allocation and the realisation reported at the end of 2025 differ in exactly one line: capital expenditure came in Rp24.6 billion under plan, and that amount is the entire unspent residue [32].
Source: FY2025 Annual Report, realization of the use of proceeds from the public offering [33].
Two features of that table belong in the record rather than in an argument. Rp4,067.8 billion, or 41.9% of the net proceeds, retired debt, of which Rp825.0 billion was owed to the controlling shareholder PT Harita Jayaraya. And Rp4,922.9 billion, or 50.7%, went into associates and subsidiaries as equity, loans or stake purchases rather than into assets the listed entity consolidates.
Guidance against outcome
From the FY2022 report through the FY2024 report, the company published a two-line operating target and the realisation against it: nickel ore sales volume in wet metric tonnes before elimination, and processing sales volume in tonnes of contained nickel. Each year's projection was stated as a percentage increase on the prior year in the report where it first appeared, and the absolute target appeared in the following year's comparison table.
Sources: the 2022 revenue and capital goods investment outturn against internal target, and the 2023 nickel ore sales volume projection, FY2022 Annual Report [34]; the 2023 target-versus-realization table and the 2024 nickel ore sales volume projection, FY2023 Annual Report [35]; the 2024 target-versus-realization table and the 2025 sales volume projection, FY2024 Annual Report [36]; the 2025 statement that financial targets are not publicly disclosed and the mining sales volume realization against target, FY2025 Annual Report [37]; the 2026 nickel ore sales volume projection [38]; the FY2025 nickel ore and FeNi sales volumes, FY2025 Annual Report [39]; half-year mining and RKEF sales volumes, 1H26 presentation [40]. The 2022 ore volumes behind the 97.9% comparison are the saprolite and limonite figures in the FY2023 Annual Report [41]. The FY2025 targets are derived by applying the FY2024 report's stated percentages to the FY2024 realisations.
Mining volume beat the published target in each of the three years the target was published, by 32.8%, 18.8% and, on the derived FY2025 basis, roughly 4.5%.
Sources: the 2023 nickel ore sales volume target and realisation as tabled in the FY2023 Annual Report [42]; the 2024 sales volume target and achievements from mining and processing operations, FY2024 Annual Report [43]; FY2025 realisation of 30.59 million wmt, FY2025 Annual Report [44]; the FY2025 target bar is derived from the FY2024 report's stated 23% increase, since no absolute FY2025 target was published.
The disclosure break in the 2025 report
The FY2025 Annual Report ends the series. Where the three prior reports opened this section with a table, the 2025 edition states: "Given the highly competitive market environment, the Company does not publicly disclose its financial targets." It then reports that mining volume came in 4.5% above target and processing volume 0.6% above target, without publishing either target [45].
The processing figure carries a second measurement question the report does not resolve. The FY2024 report set the 2025 processing target as "relatively the same as the previous year (reflecting the operations of PT MSP and PT HJF)" — that is, on the two consolidated smelters, excluding the 35%-held associate PT Karunia Permai Sentosa [46]. Earlier in the same FY2025 report, the Board of Directors Report states ferronickel sales volume of 188,581 tonnes of contained nickel against 126,344 tonnes in 2024, a 49.3% increase, and attributes it to PT MSP, PT HJF and PT KPS together [47]. A 0.6% beat and a 49.3% increase sit in the same document because they count different entities. Neither passage says so.
From the FY2025 report onward, the only published measure of delivery against plan is a percentage whose denominator is not disclosed, and the processing percentage and the headline processing volume are computed on different entity perimeters.
Capital allocation ledger
Every cash movement below is drawn from the filings that disclose it. Where a return or an objective is not stated, the row says so rather than estimating.
Sources: IPO proceeds [48]; dividend policy and FY2022–FY2024 dividends [49]; FY2025 dividend [50]; 2024 EGMS outcomes and buyback authority [51]; rights issue status [52]; buyback realisation by authority [53]; buyback realisation and HPL capital increase [54] [55]; ONC purchases, revaluation gain and dividends [56] [57] [58]; HPL dividend [59].
Two disclosure points sit inside that ledger. The Rp1,513.4 billion revaluation gain on the original 10% of ONC rests on a KJPP appraisal report dated 18 March 2025, three months after the transaction, valuing the stake as at 13 December 2024, and was routed to other comprehensive income [60]. And the two ONC purchases were struck at almost the same price per share — Rp3,370,570 in December 2024 from a third party, Rp3,381,837 in June 2025 from the controlling shareholder — a point the company itself made on the slide announcing the second deal, describing it as at "similar valuation with the previous transaction" [61] [62]. No hurdle rate, payback period or expected return was published for either purchase.
Capital returned to shareholders has risen each year the company has been listed; capital spent on its own assets has fallen every year since 2022.
Sources: capital goods investment as reported for 2022 and 2023 in the FY2023 Annual Report [63], for 2024 in the FY2024 Annual Report [64] and for 2025 in the FY2025 Annual Report [65]; dividends by payment year from the dividend table in the FY2025 Annual Report [66]. The FY2025 report restates 2024 capital goods investment as Rp1,255 bn against the Rp1,249 bn originally reported.
Authorised but not executed
Two capital-raising mechanisms were put to shareholders on 15 March 2024 for the same stated purpose. The financial statements set it out plainly: after obtaining approval, "the Company will decide to conduct Non-Preemptive Private Placement or Rights Issue. Company's decision is based on the final plan in relation to the purchase of equity stake in a company engaged in nickel ore smelter or other mining company" [67].
The private placement of up to 6,309,860,000 shares failed for want of a quorum and was never discussed. The rights issue of up to 18,929,580,000 shares — 30% of issued capital — passed with 99.93% of votes cast [68]. Asked about it at the June 2024 public expose, management said the proceeds "will be used to increase the capacity production and nickel reserves of the Company" and that "the Company also plans to increase shares ownership in the smelter and refinery facilities" [69].
Neither instrument was used. The FY2024 report recorded the rights issue as "has not been realized yet" [70]. The FY2025 report added a reason: "This decision was made after considering capital market dynamics, industry conditions, and the Company's funding requirements in order to ensure that the corporate action is carried out at the appropriate time and provides optimal value for the Company and its shareholders" [71]. The share listing chronology confirms the arithmetic: the only listing event since incorporation is the 12 April 2023 IPO, and "the Company did not issue other securities in any form" through 31 December 2025 [72].
The stake purchases the raise was meant to fund happened anyway, paid in cash: Rp2,117.5 billion in December 2024 and Rp4,249.2 billion in June 2025 [73] [74]. Over the same period the buyback authorities went almost unused: two successive Rp1 trillion mandates produced Rp75.6 billion of purchases through December 2025, which the FY2025 report describes as 7.6% of the approved amount — a figure that corresponds to one of the two authorisations rather than their sum [75].
Explanations that changed
Nickel prices have been the standing question at every public expose since the listing, and the account management gives has moved three times.
"Currently, nickel is oversupplied due to the increase of the nickel production in Indonesia. After we met several analysts and securities outside the country, they said that the oversupply is not as bad as predicted." — 27 June 2024, supported by stainless steel growth of 8% and Chinese property stimulus [76]
"The Company views the current nickel price as relatively stable. Based on LME data, the price hovers around USD 15,000/ton Ni and has occasionally lower below that level." — 18 June 2025, with the added expectation that the level was the floor [77]
"The Government has set the 2026 nickel RKAB at approximately 260 to 270 million tons, more controlled" than the 364 to 379 million tonnes of 2025 — the FY2025 report, which relocates the rebalancing hope from demand to Indonesian production quotas and describes 2023–2024 as "the oversupply period that pressured prices" [78]
The wording that disappears is as much a fact as the wording that arrives. The demand-side reassurance of 2024 — Chinese stainless steel growth, EV battery demand still compounding at double digits — is absent from the FY2025 report's outlook, which leads instead with supply policy. The FY2023 report had already named the risk that later dominated: it cited a World Bank forecast of nickel prices falling up to 10% in 2024 and the emergence of lithium ferro phosphate battery chemistry "as a substitute for nickel batteries" [79]. Asked directly in June 2026 why investors should expect MHP demand to absorb Indonesia's HPAL build-out when LFP holds roughly 80% of Chinese EV battery installations, management answered on market segmentation and recyclability rather than volumes [80].
A second, narrower drift runs through the IRMA responsible-mining certification.
"The Company expect that this certification will be completed soon and we will be certified no later than approximately in early 2025. If the certification is completed, we are the second company in Indonesia to be certified by IRMA after Vale." — 27 June 2024 [81]
"The audit has been ongoing since 2024 and remains in progress. The Company is currently in the corrective action period… The Company expects the auditor to conduct a re-verification within this year." — 30 June 2026 [82]
Between those two statements the target moved from certification by early 2025 to re-verification during 2026, and the comparison to Vale is not repeated.
Commitments still open
Sources: PT Obi Stainless Steel status and carrying value, FY2025 Annual Report [83] [84], and the stainless steel plan in the FY2023 Annual Report [85]; PT BBS, PT CKM and mining concessions from the 2024 and 2025 public expose minutes [86] [87]; CKM schedule and cost, November 2025 presentation [88]; KPS phasing and 1H26 project status [89] [90] [91]; Iron Extraction Project rename and the 50 MW steam power plant, May 2026 presentation [92]; IRMA status [93].
PT Karunia Permai Sentosa is the one item on that list delivered on the schedule management gave. In June 2025 the company said Phase 2 would "be commencing in Q3 or Q4" and the next phase "in early 2026", against a total installed capacity of 185,000 tonnes of nickel in ferronickel [94]. Phase 2's eight lines were reported complete as at December 2025 and Phase 3 in the first half of 2026 [95] [96].
Where the earnings now come from
The composition of reported profit has shifted alongside the stake purchases. Share of profit from associates — chiefly the 45.10%-held HPL, the 40%-held ONC and the 35%-held KPS — was Rp2,012.9 billion in 2024 and Rp4,090.7 billion in 2025, against profit for the year of Rp7,712.4 billion and Rp10,970.3 billion respectively [97] [98]. ONC alone moved from Rp54.8 billion to Rp1,462.7 billion of that line as its stake doubled and its refinery reached full capacity [99].
Source: profit for the year and share of associate profit as recorded in the FY2025 Annual Report [100]; the associates’ share of profit table, Note 10 [101]; the consolidated bar is derived as profit for the year less the share of associate profit.
The mining segment's reported revenue after elimination moved the other way over the same period, from Rp3,093 billion in 2023 to Rp3,801 billion in 2024 and Rp7,178 billion in 2025, as PT KPS's smelters drew ore from the group's own mines [102] [103]. Asked in June 2026 whether that meant selling ore had become more profitable than processing it, management said mining carries the higher percentage margin but the smaller nominal contribution, because ore sells for far less per tonne than processed product [104]. Named-rival comparisons on this point belong to Competition; the ownership and control questions the associate structure raises belong to People.
What the record does not settle
Three things the filings state but do not close out. The FY2025 report's 4.5% and 0.6% delivery percentages have no published denominators, and the processing percentage counts a narrower set of entities than the 188,581-tonne volume printed in the same report. The two ONC purchases, totalling Rp6,366.7 billion and taking the stake from 10% to 40%, carry disclosed prices and appraisal references but no stated return objective; the second was struck with the controlling shareholder. And PT Obi Stainless Steel, formed in November 2021 and still described in the FY2023 report as part of a plan to build a stainless steel manufacturing facility, sits at 31 December 2025 with Rp3 million of total assets, a Rp1.09 billion carrying value and no commercial operation date [105].
Control at a Glance
PT Trimegah Bangun Persada (Harita Nickel) is a single-share-class company with one controller. The Lim family's holding vehicle, PT Harita Jayaraya, held 81.32% of the issued shares at 31 December 2025, down from 84.69% a year earlier after selling part of its position into a stake taken by Glencore [1]. The public float is 10.44%. No director and no commissioner owns a single share, directly or indirectly [2].
That combination shapes everything else on this page. Pay is cash-only and set inside the controller's orbit; the operating board is drawn almost entirely from the group's own subsidiary directorships; and roughly a fifth of revenue and a sixth of cost of goods sold run through entities under common ownership. This tab records those facts and their dates. It does not grade them.
PT Harita Jayaraya stake
Public float
Board + commissioner ownership
Related-party share of revenue
Sources: FY2025 Annual Report, Shareholders Information [3]; indirect ownership disclosure [4]; Note 35 related-party revenue [5].
Votes Versus Economics
There is one class of registered common shares with a Rp100 par value; every share carries the same rights to dividends, liquidation proceeds and votes at the general meeting [6]. There are no founder shares, no multiple-vote structures, and no disclosed shareholder agreement or nomination-rights instrument in the annual reports. The only wedge between economic and voting percentages is the treasury block: the 110,733,300 shares repurchased during 2025 sit as treasury stock, 0.18% of issued capital, and carry neither vote nor dividend [7].
Sources: economics as reported at 31 December 2025 [8] and Note 26 Equity [9]; voting percentages derived by excluding the 110,733,300 non-voting treasury shares from the 63,098,600,000 issued.
The practical position for a minority holder follows from the arithmetic. At 81.46% of voting stock the controller passes ordinary and special resolutions alone. The 2025 annual meeting shows what that looks like in practice: on the six agenda items put to a vote, approval ran between 98.60% and 99.93%, with no item drawing more than 1.32% against [10]. The largest dissent, 766,650,207 votes against, landed on the auditor-appointment item.
The Ownership Chain
Control runs through three layers before it reaches a listed share.
Source: FY2025 Annual Report, Composition of Main/Controlling Shareholders — the Lim family holding chart [11]; the layer-2 individual holdings are shown as 7.33%, 6.42% and 4.58% in that chart.
Two things about this chart are worth stating plainly. The 40.00 / 35.00 / 25.00 split at the top of PT Harita Guna Dharma Bhakti appears identically in the FY2024 and FY2025 filings [12]. What did change is the layer beneath it: the FY2024 diagram shows four individuals holding PT Harita Jayaraya directly alongside the holding company — Lim Hariyanto Wijaya Sarwono at 4.58%, Rita Indriawati at 2.75%, Lim Gunawan Hariyanto at 6.42% and Lim Gunardi Hariyanto at 4.58% [13]. The FY2025 diagram shows three: Rita Indriawati is gone and Lim Hariyanto Wijaya Sarwono's direct holding is 7.33%, exactly the sum of those two [14]. Neither filing carries a text table beside the diagram or explains the transfer.
How Ownership Moved Since the IPO
NCKL listed on 12 April 2023 at Rp1,250 per share, selling 7,997,600,000 new shares equal to 12.67% of post-offer capital and raising Rp9,997 billion [15]. Before the offer, PT Harita Jayaraya held 99.00% [16]. Both pre-IPO holders were locked up under OJK Regulation 25/2017 for eight months after the registration statement became effective, because they had acquired their shares below the offer price within six months of filing [17].
Sources: FY2023 Annual Report, Shareholders Information [18]; FY2025 Annual Report, Shareholders Information [19]; Note 26 Equity for the December 2024 register [20].
During 2025 Glencore International Investments appeared on the register at 4,534,708,000 shares, or 7.19%, held through Citibank Hong Kong [21]. The controller's holding fell by 2,127,086,500 shares over the same period and the public float fell by 2,518,354,800 shares, so the new stake was assembled from both the controller and the market. Glencore is also a customer: Glencore International AG accounted for Rp5,637,265 million of nickel-processing revenue in FY2025, 19.02% of the total, up from 11.27% in FY2024 [22]. The filings disclose no shareholder agreement, board seat or offtake right attaching to that shareholding.
Foreign institutions held 12.13% of the register at year-end 2025 against 84.48% for domestic institutions and 3.39% for domestic individuals. The company's separate breakdown of holders below 5% covers 6.55% of issued capital — 3.93% individuals, 2.29% companies and institutions, and the balance across mutual funds, insurers, pension funds, foundations and cooperatives [23].
Two Boards, One Group
Indonesia's two-tier structure separates the executive Board of Directors from the supervisory Board of Commissioners. NCKL runs five directors and three commissioners. All eight were appointed by Deed No. 145 of 15 December 2022 or, for Suryadi Sasmita, Deed No. 404 of 27 January 2023 [24]. There was no change to either body during 2025, nor between year-end and the filing of the 2025 annual report [25].
Sources: FY2025 Annual Report, Profile of the Board of Commissioners — Donald J. Hermanus [26] and Darjoto Setyawan [27]; Profile of the Board of Directors [28], [29] and [30]; committee memberships from Committees under the Board of Directors [31] and [32]; AGMS chair [33].
Disclosed independence and observed facts
The company designates two of three commissioners as independent and designates no independent director; the term Direktur Independen does not appear in the FY2025 board disclosures. Every profile in the annual report carries the same standard sentence: the individual "has no financial, management, or family relationships with other members of the Board of Commissioners, members of the Board of Directors, as well as Major and Controlling Shareholders" [34].
Set against that designation, the same profiles record the following. President Commissioner Donald J. Hermanus is concurrently President Director of six Harita group companies, including PT Halmahera Jaya Feronikel, PT Obi Nickel Cobalt and PT Obi Stainless Steel, a director of three more and a commissioner of four more — thirteen concurrent group posts in total [35]. HSE director Tonny H. Gultom holds twelve [36]. Finance director Suparsin Darmo Liwan is simultaneously CFO of PT Halmahera Persada Lygend, the 45.10%-held HPAL associate that is also a related-party customer [37]. President Director Roy Arman Arfandy holds seven group posts, including President Director of PT Halmahera Persada Lygend and commissioner seats at PT Obi Nickel Cobalt, PT Karunia Permai Sentosa and PT Dharma Cipta Mulia — three of the counterparties in the related-party ledger below [38]. The FY2024 report listed six of those posts [39]. Only Younsel Evand Roos, the operations director, holds no outside position [40].
The two independent commissioners bring outside listed-company experience: Darjoto Setyawan is an independent commissioner of PT Cita Mineral Investindo Tbk and PT China Life Insurance Indonesia, and was President Director of PT Siloam International Hospitals Tbk to 2024 [41]; Suryadi Sasmita is an independent commissioner of PT Global Digital Niaga Tbk and holds several non-Harita directorships [42].
The company states it has no specific diversity policy for either body, while noting that the nomination process considers education, experience, age, gender and nationality [43]. One of five directors is female; all three commissioners are male. Director ages span 42 to 69, commissioner ages 59 to 77.
Meeting cadence and attendance
Sources: FY2025 Annual Report, Board of Directors meeting attendance [44]; attendance at joint meetings [45]; Board of Commissioners meeting attendance [46].
Twelve board meetings, six commissioner meetings and four joint meetings were held in 2025; average director attendance was 90% at board meetings and 100% at joint meetings, and average commissioner attendance was 94% and 92% [47] [48] [49]. The one director below 90% was Lim Sian Choo, at nine of twelve board meetings [50].
Committees
Sources: FY2025 Annual Report, Audit Committee composition [51]; Audit Committee meeting count [52]; Nomination and Remuneration Function [53]; Committees under the Board of Directors [54], Sustainability and Diversity Committee membership [55] and performance [56], Ethics and Risk Committee membership [57] and performance [58].
The Audit Committee is the one board committee with disclosed independent membership and a disclosed meeting record. It has three members appointed by commissioners' decree of 13 December 2022, all serving into their fourth year: Darjoto Setyawan as chair, plus two independent members with audit and CFO backgrounds — Toni Setioko, a former Prasetio Utomo audit manager and DBS Vickers Indonesia operations director [59], and Tsun Tien Wen Lie, an audit and tax partner at KAP Heliantono and Rekan who is also a director and corporate secretary of PT Arthavest Tbk and an independent commissioner at two other listed issuers [60]. It met four times in 2025 with full attendance [61].
No Nomination and Remuneration Committee has been formed. The company states that as of 31 December 2025 the function is carried out directly by the Board of Commissioners, which it says is permitted by the committee's own charter in the absence of a committee [62]. The nomination policy states that candidates for both boards are sourced primarily from within the group — from subsidiary directors or company employees — with external recruitment reserved for specified conditions [63].
The other two committees sit under the Board of Directors rather than the Board of Commissioners, and their membership is drawn from the directors themselves plus three senior employees [64]. The Sustainability and Diversity Committee is chaired by the President Director with the Director of Sustainability as co-chair, and met four times in 2025 [65] [66]. The Ethics and Risk Committee, which runs the whistleblowing system, changed chair during the year: Mordekhai Aruan resigned from the company, ending his tenure as chair, and directors' decree No. 145/S/LGL/TBP/VIII/2025 installed HSE director Tonny H. Gultom in his place [67]. It also met four times [68]. Both committees report to the executive body they advise; neither carries an independent member.
Operators
Sources: FY2025 Annual Report director profiles — the KPMG audit manager record for Suparsin Darmo Liwan [69], Younsel Evand Roos [70], Lim Sian Choo [71] and Tonny H. Gultom [72]; FY2024 Annual Report for Roy Arman Arfandy [73] and the Stevi Thomas departure [74].
The whole executive board shares one appointment date and one expiry: all five directors were named in Deed No. 145 of 15 December 2022, on a term running to the close of the 2027 annual meeting [75]. That means the entire operating team comes up for renewal at the same meeting, with no staggering.
Three dated departures sit in the record. Stevi Thomas C, Director of External Relations, resigned effective at the close of the 27 June 2024 annual meeting, which granted him acquit et de charge; the change was notarised as Deed No. 266 and registered with the Ministry of Law on 17 July 2024 [76]. His seat has not been refilled — the board went from six directors to five and stayed there. Separately, Corporate Secretary Franssoka Yunus Sumarwi, in post since 29 November 2022, resigned effective 12 December 2025, and the company states that as of 31 December 2025 no successor had been appointed [77]. By July 2026 the role was held by Rafika Fazrin, who signed the annual public expose report to the exchange [78]. Third, Mordekhai Aruan left the company during 2025, ending his chairmanship of the Ethics and Risk Committee; the HSE director took the chair in August 2025 [79].
Investor relations is run by Lukito Gozali, appointed July 2023, previously head of investor relations at Kalbe Farma, Nippon Indosari Corpindo and Erajaya Swasembada; he holds no concurrent positions [80].
What Compensation Pays For
The incentive architecture is short and can be stated in full.
Sources: FY2025 Annual Report, Remuneration Structure and Determination Process [81]; disclosure of bonuses and stock options [82]; long-term performance-based compensation policy [83].
The determination process is a six-step loop the company sets out explicitly: directors formulate strategy with commissioner approval, KPIs are set as the basis for measurement, directors self-assess monthly and report quarterly, commissioners assess against KPIs and market benchmarking, commissioners propose remuneration to the general meeting, and the meeting sets the commissioners' total while delegating the directors' figure back to the commissioners [84]. The 18 June 2025 annual meeting executed that delegation, passing the item with 99.93% support [85].
What the KPIs are, how they are weighted, and what thresholds apply is not disclosed. Nor is any individual figure: the company states plainly that it does not disclose per-member remuneration, citing the sensitivity of the information and the risk of unfair recruitment by others, and discloses collective totals only [86]. Indonesian rules do not require a CEO pay ratio and none is given.
Because there are no options and no long-term share plan, there is no strike price to compare with the current price, no vesting schedule, and no equity dilution from management incentives. The only share-based programme in the company's history was the Employee Stock Allocation at the 2023 IPO: 35,000,000 shares, 0.44% of the offer, priced at the Rp1,250 offer price, allotted on a fixed-allotment basis with no lock-up period [87].
The pay record
Sources: FY2022 Annual Report, key management compensation for FY2021 and FY2022 [88]; FY2023 Annual Report [89]; FY2024 Annual Report [90]; FY2025 Annual Report remuneration table [91].
Total board and commissioner pay quadrupled in the listing year — from Rp15.5 billion in FY2022 to Rp61.7 billion in FY2023 — then fell 22% to Rp48.1 billion in FY2024 and rose 6% to Rp51.1 billion in FY2025 [92] [93] [94]. Part of the FY2024 drop reflects the board shrinking from six directors to five. Note 35 of the audited accounts carries the identical figures, described as gross key-management compensation paid by the company and its subsidiaries and associates [95].
Against profit, the aggregate is small and falling: Rp51.08 billion of FY2025 pay against Rp8,951,516 million of profit attributable to owners is 0.57%, versus 0.75% on FY2024's Rp6,379,504 million [96]. Averaged across the five directors, FY2025 pay is Rp8.5 billion each; across the three commissioners, Rp2.8 billion each. Those averages are arithmetic, not disclosure — the company has said it will not break the figure down.
Insider Activity and Capital Returns
There is no conventional insider-transaction record to plot, because there are no insider holdings. The company states that as of the end of 2025 no member of either board holds shares directly or indirectly, so no ownership report or change report has been filed under OJK Regulation 4/2024 [97]. The FY2023 register carried the same nil entry for all nine officers then in post [98]. The company also states there were no insider-trading cases involving commissioners, directors, management or employees during 2025 [99].
What does move is the company's own buying and the controller's selling.
Sources: IPO Prospectus offering structure [100]; FY2025 Annual Report buyback resolution and realisation [101] and share buyback detail [102]; Note 10 for the ONC purchases [103] and [104]; director and officer departures [105] and [106].
Two authorisations of Rp1 trillion each produced Rp75.61 billion of actual repurchases — 110,733,300 shares at an average of Rp682.81, or 7.6% of the approved amount [107]. Results reports for both tranches were filed with the OJK on 15 July 2025 and 15 January 2026 [108]. The average repurchase price of Rp682.81 sits against a Rp1,250 IPO price and a Rp935 close on 3 August 2026.
The dividend policy is a stated minimum of 30% of net profit, as disclosed in the IPO prospectus. Both post-listing payouts have landed on that floor: Rp26.716 per share for FY2023, totalling Rp1,685.74 billion at exactly 30%, and Rp30.357 per share for FY2024, totalling Rp1,913.90 billion at 30.001% [109].
Related-Party Ledger
Related-party flows are the largest single governance surface here, and they grew sharply in 2025. Revenue from related parties reached Rp6,575,315 million, 22.19% of consolidated revenue, up from Rp3,801,242 million and 14.09% a year earlier [110]. Related-party cost of goods sold reached Rp3,215,711 million, 16.13% of consolidated COGS [111].
Sources: FY2025 Annual Report, Note 35 nature of relationships with common-control and associate entities [112], related-party revenue by counterparty [113], related-party cost of goods sold by counterparty [114], and the June 2025 ONC purchase from the parent in Note 10 [115]; the 45.10% holding in PT Halmahera Persada Lygend is from Note 10 [116].
Sources: FY2025 Annual Report, Note 35 related-party share of revenue [117] and related-party share of cost of goods sold [118].
The largest single related-party item of 2025 sat outside the trading ledger. On 25 June 2025 the company bought a further 20% of PT Obi Nickel Cobalt from its own parent, PT Harita Jayaraya, for US$262,913,649, or Rp4,249,210 million, taking its holding to 40% [119]. Six months earlier the company had bought 10% of the same entity from an unrelated Singapore holder, Li Yuen Pte Ltd, for Rp2,117,527 million, with a KJPP Benedictus Darmapuspita valuation putting the net fair value of a 20% ONC interest at Rp2,276,205 million as at 13 December 2024 [120]. Doubling the arm's-length December price implies roughly Rp4,235,054 million for 20%; the price paid to the parent six months later was Rp4,249,210 million. ONC then distributed dividends of US$40.0 million in July 2025 and US$52.0 million plus US$28.0 million in November 2025 to the company [121].
Approval process
The company records that transactions are governed by OJK Regulation 42/2020 on affiliated and conflict-of-interest transactions; that the Board of Directors states the terms compare with those available between unaffiliated parties on an arm's-length basis; and that before related-party transactions are entered into, the Board of Commissioners, through the Audit Committee, reviews and advises management on affiliated transaction plans that could give rise to conflicts of interest [122]. For FY2025 the company identifies its related-party transactions under PSAK 224 and states there were no material transactions containing a conflict of interest [123]. On the June 2025 purchase from the parent, the price of Rp3,381,837 per share was set by an appointed public appraiser (KJPP) [124]; the appraisal itself is not reproduced in the annual report, and no independent-shareholder vote on the transaction is recorded in the meeting agendas for 2025 [125].
Officer and Director Docket
Sources: FY2023 Annual Report, Litigations [126]; FY2024 Annual Report, Litigation follow-up [127]; FY2025 Annual Report, Legal Cases [128] and Administrative Sanctions [129].
The one substantive docket item concerns a former director and is stated as an allegation, not an outcome. In December 2023 Stevi Thomas, then Director of External Relations, was named a suspect by Indonesia's Corruption Eradication Commission in a case of alleged gratification, and was undergoing trial at Ternate District Court as at the FY2023 annual report's issue date. The company disclosed the matter to the OJK on 21 December 2023, stated that it does not have a material impact on business activities, and noted it had already received his resignation letter [130]. The FY2024 report records only that the resignation was formalised at the 27 June 2024 annual meeting [131]. Neither the FY2024 nor the FY2025 annual report states how the proceeding ended; the FY2025 report simply records no material legal cases involving the company or its current officers [132].
What a Minority Holder Can and Cannot Do
The mechanics are straightforward and worth setting out without inference. A holder of the 10.44% float cannot block an ordinary or extraordinary resolution, cannot force a board nomination — candidates are sourced internally through a function the commissioners perform themselves [133] [134] — and cannot see individual pay [135].
What a minority holder does get is a fixed dividend floor of 30% of net profit that has been met in both post-listing years [136], an audit committee chaired and staffed by independent parties with a disclosed remit over affiliated transactions [137] [138], a Big Four auditor — Chang Hartono of Purwantono, Sungkoro and Surja, a member of Ernst and Young Global, who signed the FY2024 opinion [139] — appointed through a meeting agenda item put to a vote each year [140], and a company with no management equity to dilute them with.
Where those protections are thin, they are thin visibly. The related-party ledger is disclosed to the counterparty and the rupiah, but the arm's-length assertion rests on a directors' statement and an audit-committee review rather than an independent-shareholder vote. The remuneration process names its inputs — KPIs, quarterly reporting, market benchmarking — but discloses neither the metrics nor the individual outcomes. These are facts about the architecture; the chapters can weigh them.
The numbers behind PT Trimegah Bangun Persada Tbk: as-reported financial statements and company metrics for FY2021–FY2025, traced to the source filings, opened with the share-price history those statements have to justify. Every linked figure opens the exact page of the filing it was printed on, with the statement row highlighted. Amounts in Rp millions unless noted.
Reading notes: All figures are in millions of Rupiah, the scale the consolidated financial statements are printed in ("Expressed in Millions of Rupiah"). Indonesian number formatting uses "." as the thousands separator and "," as the decimal separator, so a citation anchor reads 29.632.799 for 29,632,799 and 142,02 for 142.02. FY2022 figures are cited to the comparative column of the 2023 annual report. The company's own 2022 annual report presents the consolidated statements in full Rupiah rather than millions, so its pages cannot carry an anchor at this tab's display scale. FY2021 figures cited to the 2022 annual report come from its Financial Highlights and Financial Review tables (pages 8, 9, 85-88), which are printed in Rp million. FY2021 line items that appear only in the full-Rupiah consolidated statements — SG A, other operating income and expenses, operating profit, finance income and costs, share in profit of associates, profit before tax, income tax, inventories, fixed assets, long-term bank loans and non-controlling interests — are shown unlinked; their values were read from pages 187-191 of that report and rescaled to millions. FY2019 and FY2020 have no filing in the corpus. FY2020 revenue, profit, EPS, operating cash flow, total equity and total assets are cited to the 2022 annual report's three-year highlights tables; FY2019, and FY2020 operating profit, come from the standardized data feed and are shown without page links.
Share Price — Available History Since March 2026
The stock closed at IDR 935 on Aug 03, 2026 — down 25% over the window shown, trading between IDR 780 and IDR 1,240.
Source: market price feed, daily closes, Mar 2026–Aug 2026 — the feed marks this available history as partial. Price return only, excludes dividends.
Market capitalization IDR 58.93tn.
Market cap = 63.03B shares outstanding × the Aug 03, 2026 close of IDR 935.00. Market-derived, shown without filing links.
FY2025 at a Glance
Operating income (Rp millions)
Net income (Rp millions)
Source: FY2025 consolidated statements [1] [2] [3] [4]. Click any linked figure to open the filing page with the row highlighted.
Revenue by Business Line
| Revenue by Business Line | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Nickel processing | 7,863,259 | 7,107,313 | 20,765,154 | 23,164,020 | 22,454,667 |
| Nickel mining | 365,917 | 2,460,642 | 3,092,707 | 3,801,242 | 7,178,132 |
| Total revenue from contracts with customers | 8,229,176 | 9,567,955 | 23,857,861 | 26,965,262 | 29,632,799 |
| Total revenue from contracts with customers growth, derived | — | +16.3% | +149.4% | +13.0% | +9.9% |
Source: Note 29/30 to the consolidated financial statements — revenue from contracts with customers attributable to each business line, after eliminations [5] [6]. Click any linked figure to open the filing page with the row highlighted.
Gross Profit by Segment
| Gross Profit by Segment | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Nickel Processing - gross profit | — | 2,243,568 | 4,141,291 | 4,677,331 | 4,626,733 |
| Nickel Mining - gross profit | — | 2,618,378 | 4,271,472 | 4,140,859 | 4,578,200 |
| Eliminations | — | (186,606) | (136,916) | (370,904) | 486,465 |
| Gross profit | — | 4,675,340 | 8,275,847 | 8,447,286 | 9,691,398 |
Source: Segment information note — gross profit by reportable operating segment, before eliminations [7] [8] [9] [10]. Click any linked figure to open the filing page with the row highlighted.
Income Statement
Source: Consolidated Statement of Profit or Loss and Other Comprehensive Income [1] [2] [3] [4]. Click any linked figure to open the filing page with the row highlighted.
Columns marked E are consensus analyst estimates from S&P Capital IQ (CapIQ), shown alongside reported results for direct comparison; they are not company guidance.
Estimate source: S&P Capital IQ (CapIQ) consensus, as of 2026-08-03. Estimate figures are S&P Capital IQ consensus (vendor data — no filing page links). EPS and net income use the normalized (adjusted) consensus where the street reports it. Line-item analyst models (segments, drivers, KPIs) are in the Visible Alpha tab.
Balance Sheet
Source: Consolidated Statement of Financial Position [11] [12] [13] [14]. Click any linked figure to open the filing page with the row highlighted.
Cash Flow
Source: Consolidated Statement of Cash Flows [15] [16] [17] [18]. Click any linked figure to open the filing page with the row highlighted.
Long-Term Record
| Fiscal year | Revenue from contracts with customers | Operating profit | Profit for the year | Basic earnings per share | Net Cash Provided by Operating Activities | Total Equity | Total Assets |
|---|---|---|---|---|---|---|---|
| FY2019 | 6,892,503 | 2,496,164 | 1,074,675 | 21.21 | 2,221,706 | 5,967,150 | 13,312,834 |
| FY2020 | 4,071,638 | 1,242,185 | 80,555 | 5.16 | 653,843 | 8,479,775 | 20,260,264 |
| FY2021 | 8,229,176 | 3,566,908 | 2,076,818 | 35.73 | 1,832,229 | 9,542,267 | 21,001,860 |
| FY2022 | 9,567,955 | 3,983,616 | 4,588,805 | 84.70 | 3,524,508 | 14,229,133 | 34,604,697 |
| FY2023 | 23,857,861 | 7,023,989 | 7,068,054 | 92.39 | 6,785,478 | 28,391,963 | 45,289,026 |
| FY2024 | 26,965,262 | 7,166,381 | 7,712,368 | 101.10 | 5,708,382 | 36,454,054 | 52,253,838 |
| FY2025 | 29,632,799 | 8,384,607 | 10,970,337 | 142.02 | 8,601,085 | 46,755,865 | 61,770,103 |
Source: consolidated statements across filings; older years from the standardized feed [16] [1] [2] [11]. Click any linked figure to open the filing page with the row highlighted.
Operating KPIs
| KPI | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Nickel ore sales volume (wet metric tonnes) | — | — | 15,380,000 | 23,750,000 | 30,590,000 |
| Ferronickel sales volume (tonnes of nickel content) | — | — | 100,891 | 126,344 | 188,581 |
| MHP and nickel sulphate sales volume (metal tonnes) | — | — | 60,871 | 102,054 | 130,551 |
Source: company-reported operating metrics [19] [20] [21]. Click any linked figure to open the filing page with the row highlighted.
Analyst Consensus
Mean target
Median target
High target
Low target
Street ratings: 9 strong buy, 3 buy. Consensus: Strong Buy.
Estimate source: S&P Capital IQ (CapIQ) consensus, as of 2026-08-03. Estimate figures are S&P Capital IQ consensus (vendor data — no filing page links). EPS and net income use the normalized (adjusted) consensus where the street reports it. Line-item analyst models (segments, drivers, KPIs) are in the Visible Alpha tab.
Traceability
366 of 392 figures on this page (93%) link to the filing page where they are printed — click a linked figure to open the source PDF at that page with the row highlighted. Unlinked figures come from standardized data feeds or pre-filing years.
All figures are in millions of Rupiah, the scale the consolidated financial statements are printed in ("Expressed in Millions of Rupiah"). Indonesian number formatting uses "." as the thousands separator and "," as the decimal separator, so a citation anchor reads 29.632.799 for 29,632,799 and 142,02 for 142.02.
FY2022 figures are cited to the comparative column of the 2023 annual report. The company's own 2022 annual report presents the consolidated statements in full Rupiah rather than millions, so its pages cannot carry an anchor at this tab's display scale.
FY2021 figures cited to the 2022 annual report come from its Financial Highlights and Financial Review tables (pages 8, 9, 85-88), which are printed in Rp million. FY2021 line items that appear only in the full-Rupiah consolidated statements — SG A, other operating income and expenses, operating profit, finance income and costs, share in profit of associates, profit before tax, income tax, inventories, fixed assets, long-term bank loans and non-controlling interests — are shown unlinked; their values were read from pages 187-191 of that report and rescaled to millions.
FY2019 and FY2020 have no filing in the corpus. FY2020 revenue, profit, EPS, operating cash flow, total equity and total assets are cited to the 2022 annual report's three-year highlights tables; FY2019, and FY2020 operating profit, come from the standardized data feed and are shown without page links.
FY2024 cash-flow rows and the FY2024 revenue split are cited to the 2025 annual report's comparative column: the 2024 annual report's own cash-flow page splits the financing subtotals across two printed lines and its revenue note labels the business lines on a separate row from the figures, so the 2025 report gives a cleaner one-row anchor for the same audited numbers.
FY2022 profit for the year of Rp 4,588,805 million is after a Rp 1,248,336 million merging-entities adjustment; profit before that adjustment was Rp 5,837,141 million. No sum check is attached to the profit-for-the-year row for that reason.
The FY2021 income statement also carries a Rp 11,924 million "Production halt" line that no later year repeats, so no sum check is attached to the operating profit row.
Reported segment revenue changed presentation in the 2025 annual report: the segment note now shows external revenue plus a separate inter-segment line, where earlier reports showed gross segment revenue with an eliminations column. The revenue breakdown therefore uses Note 29/30, which reports the business-line split after eliminations on a consistent basis in every year.
Quarterly income-statement and cash-flow figures are derived from consecutive printed year-to-date interim statements; the balance sheet is as printed at each quarter end. Derived cells carry "derived": "ytd_diff" and are anchored on the printed year-to-date figure. Quarterly capital expenditure is not shown: the nine-month 2025 interim report prints a lower cumulative "acquisitions of fixed assets" figure (Rp 192,735 million) than the six-month report (Rp 353,437 million), so the line is not differenceable.
5 figure(s) differed between the data feed and the filing; the filing value is shown (see the run's metrics/metrics_tab.json for the audit trail).
PT Trimegah Bangun Persada Tbk's management explains the business in its own materials. The slides below do the most of that work, pulled from the documents preserved in Sources. Each source link opens the complete presentation at that slide in a new tab.
1H26 Results Update — 1H2026
Where the business stands now — what got built in 1H26, volumes and margins by segment, dividends, and the audits that guard market access. · Open the full document →
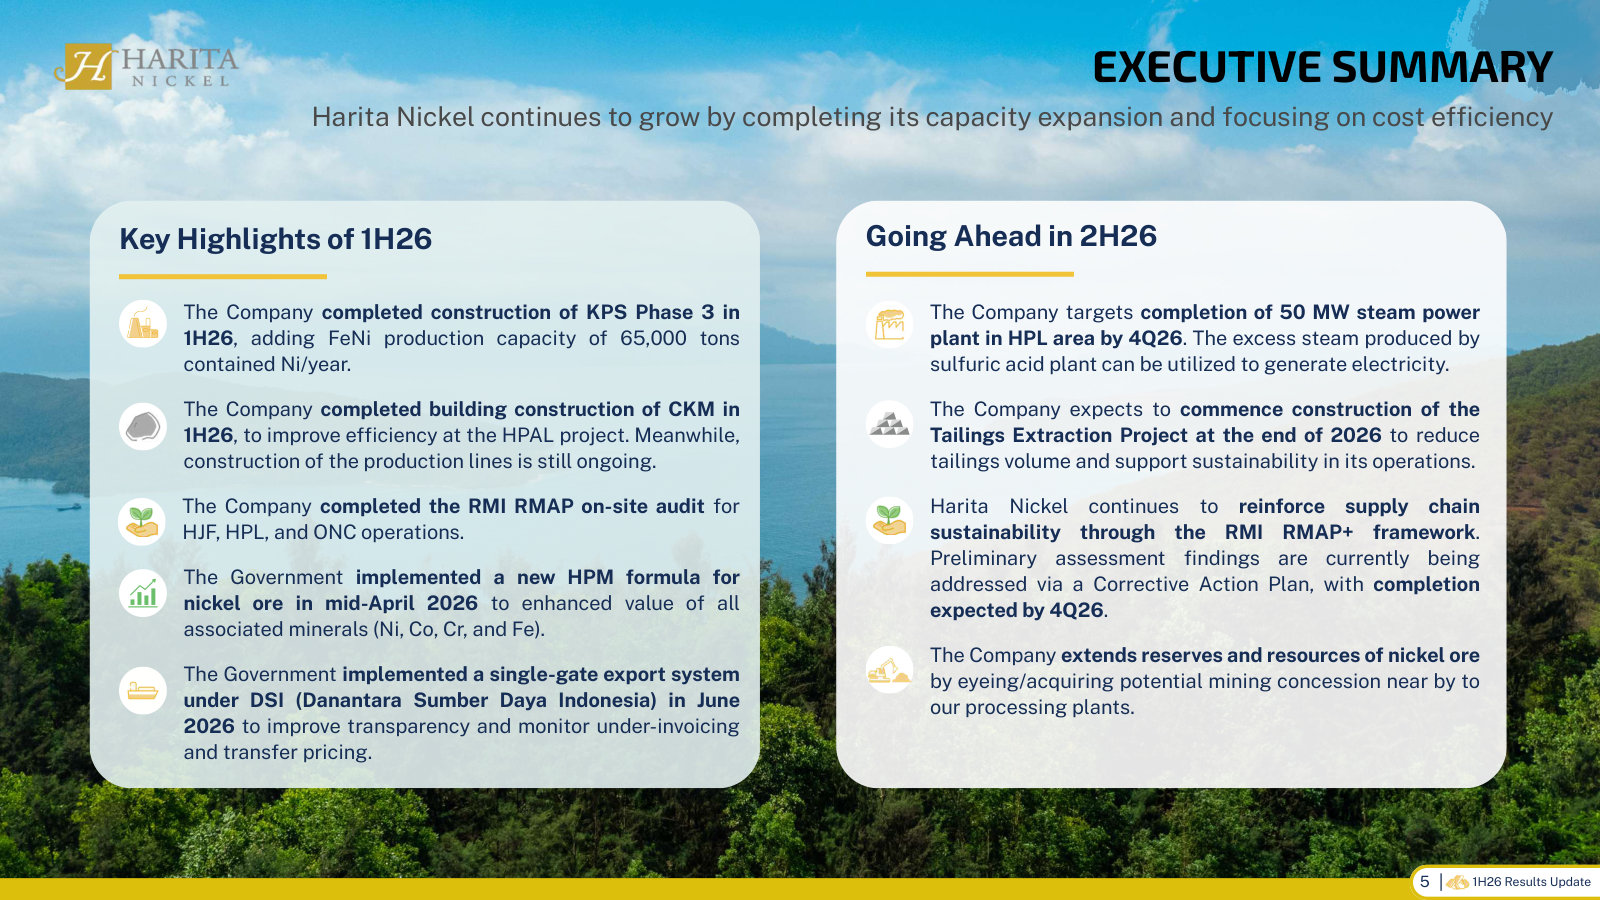
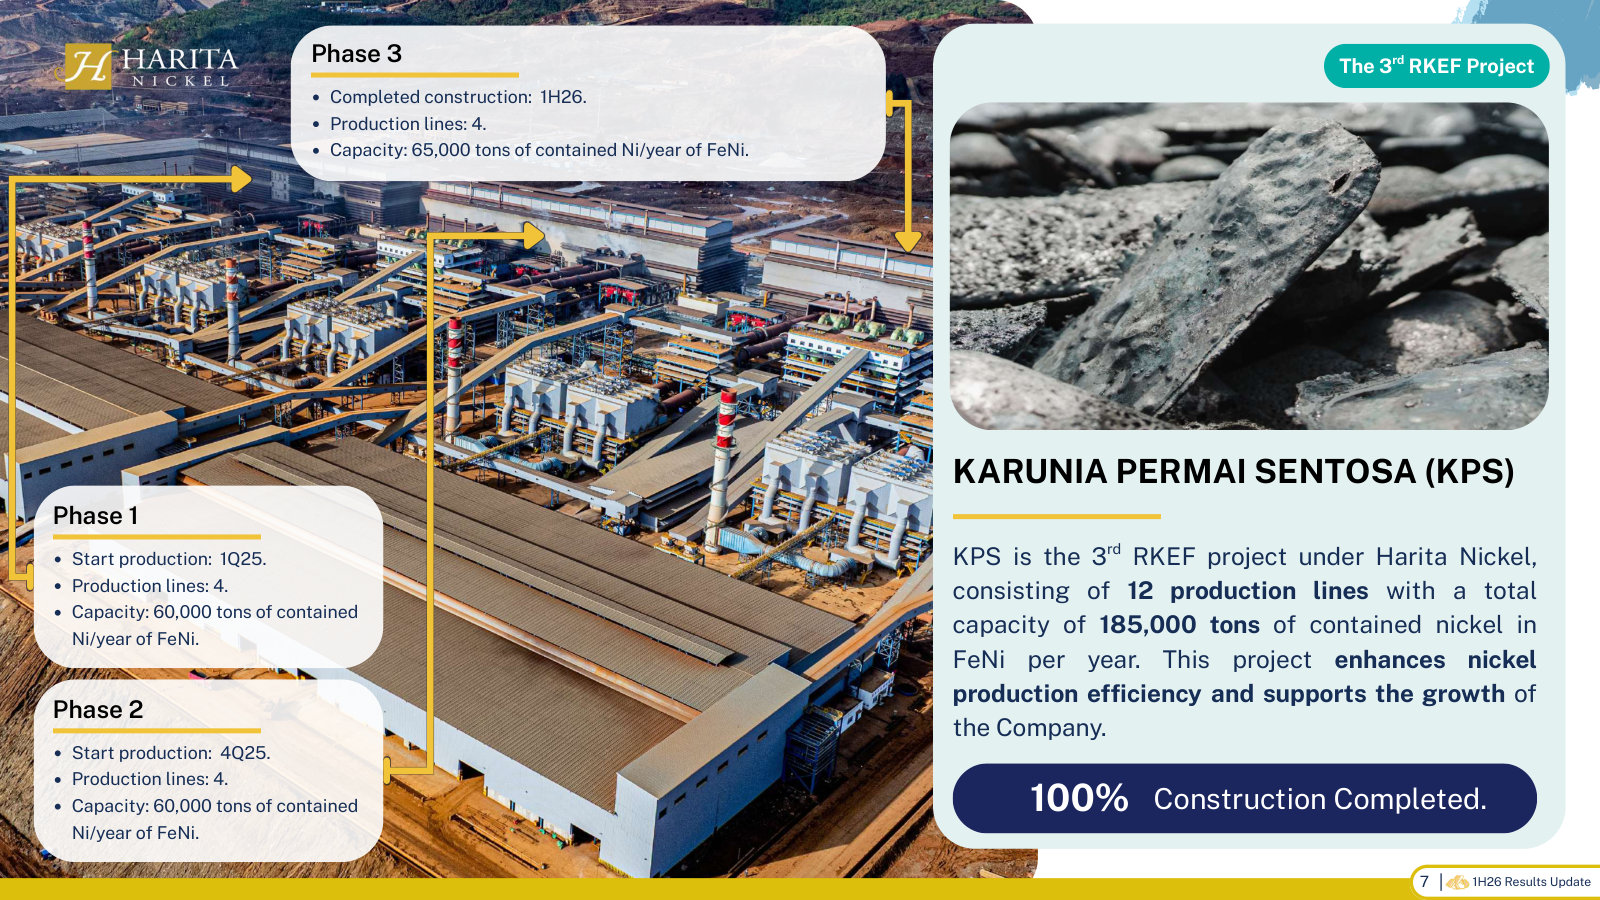
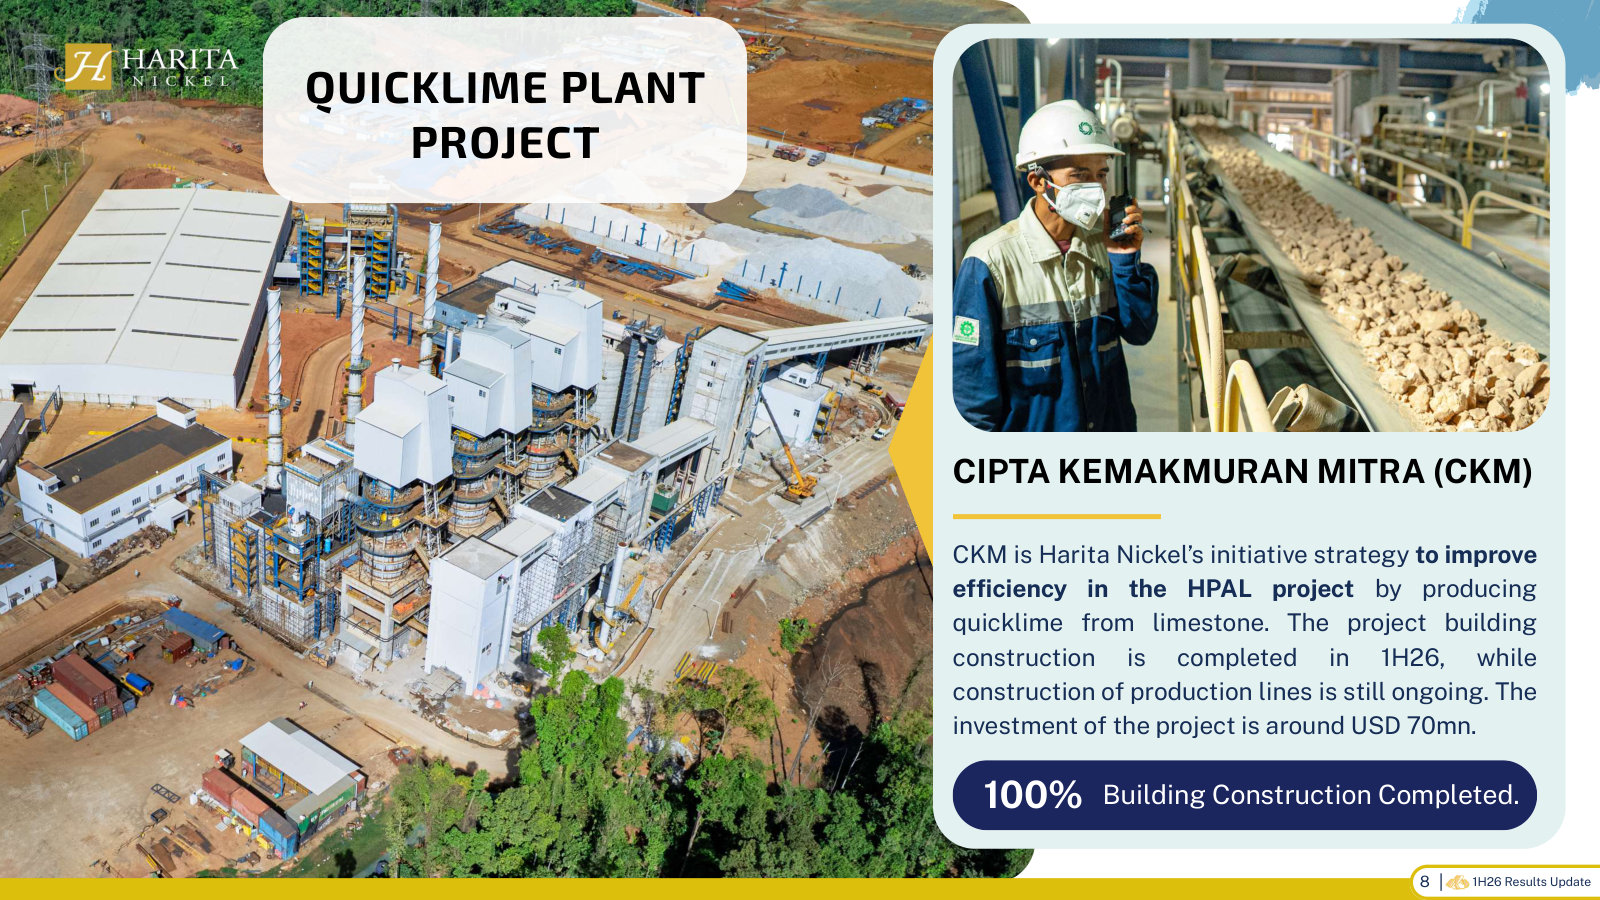
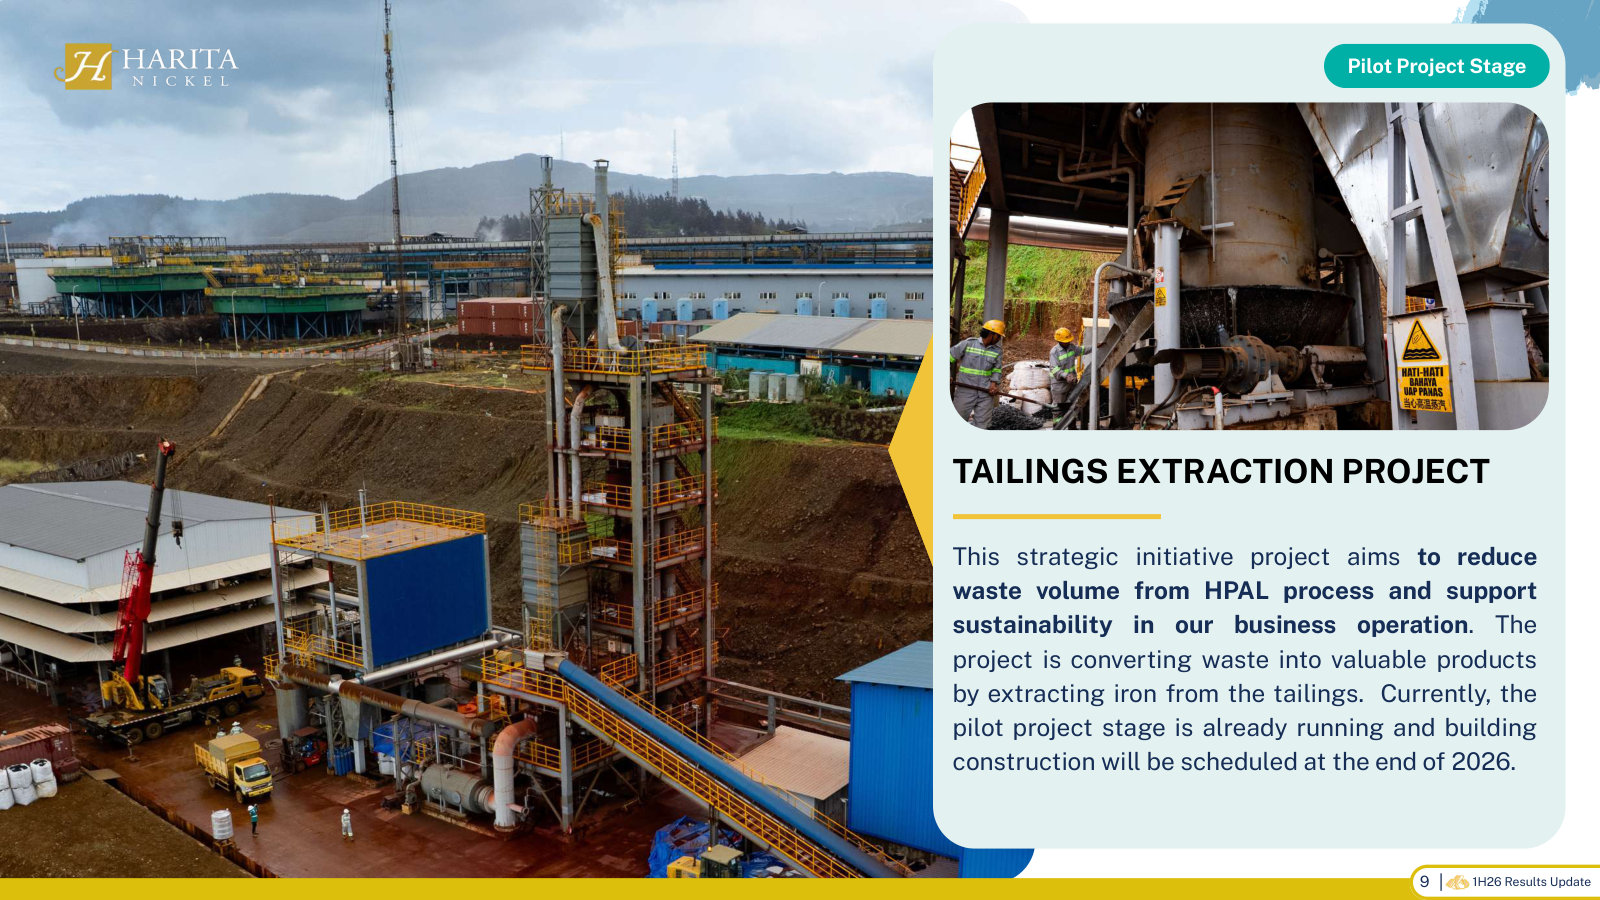
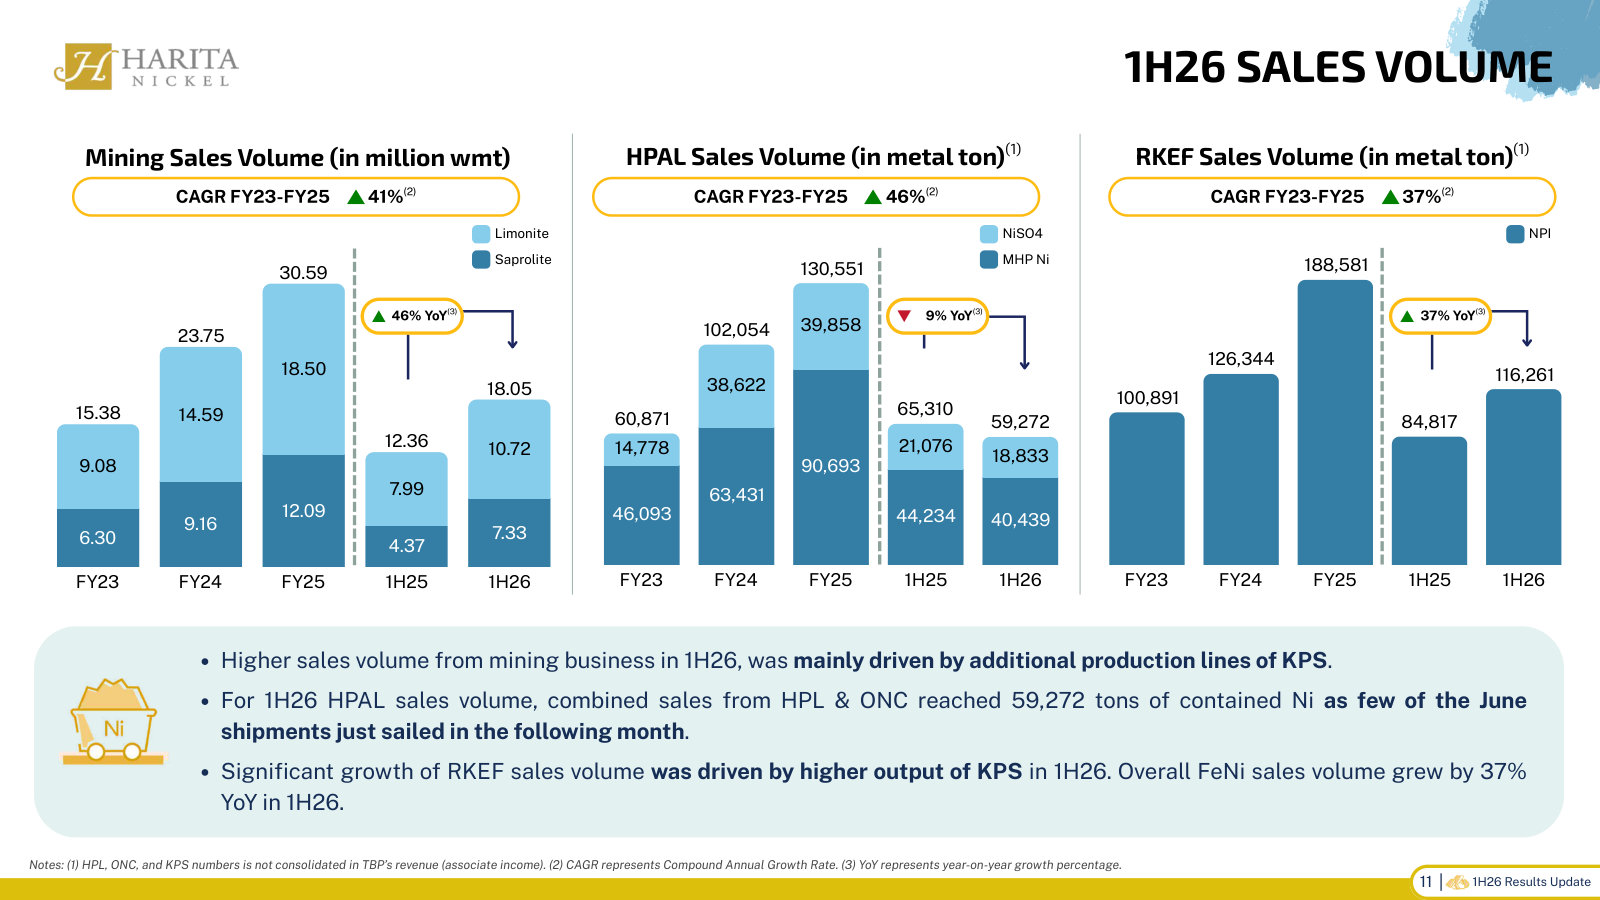
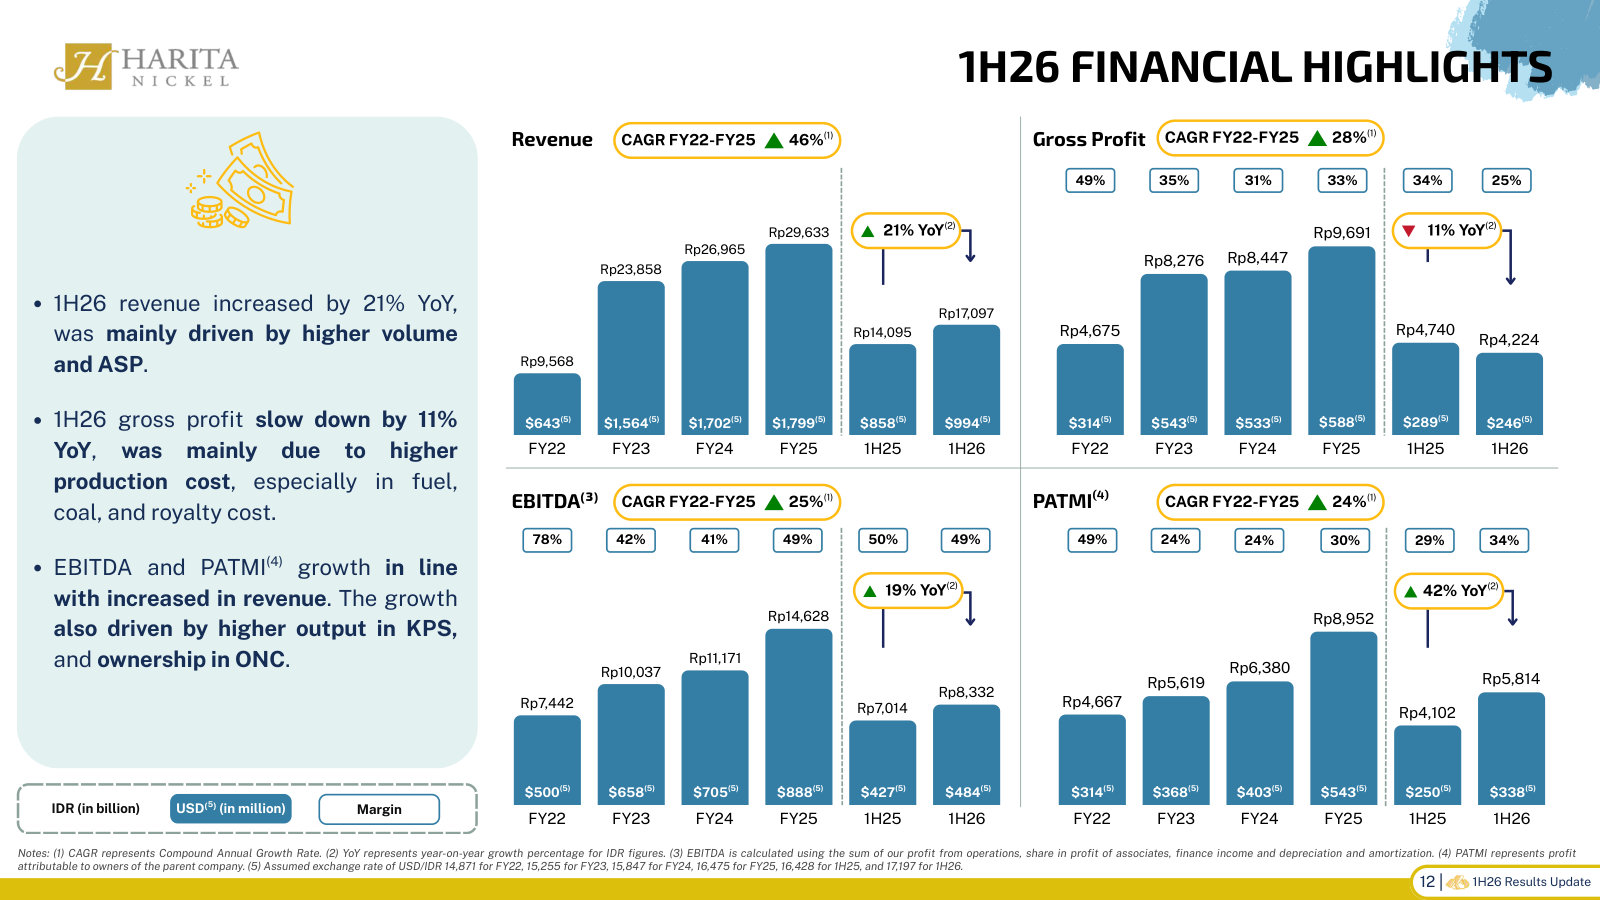
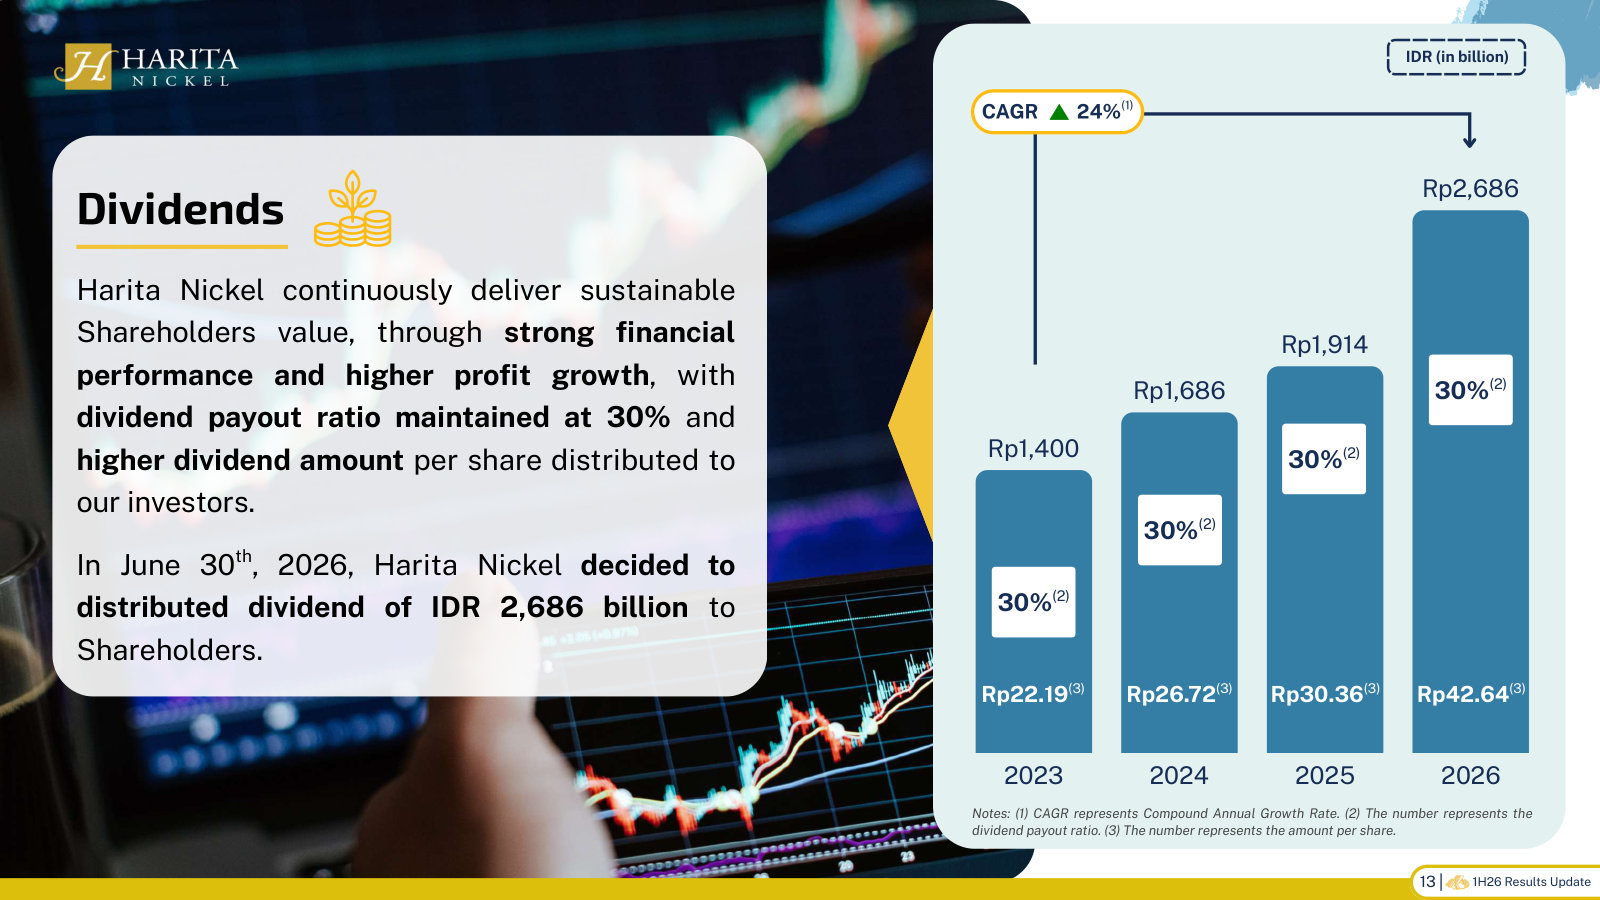
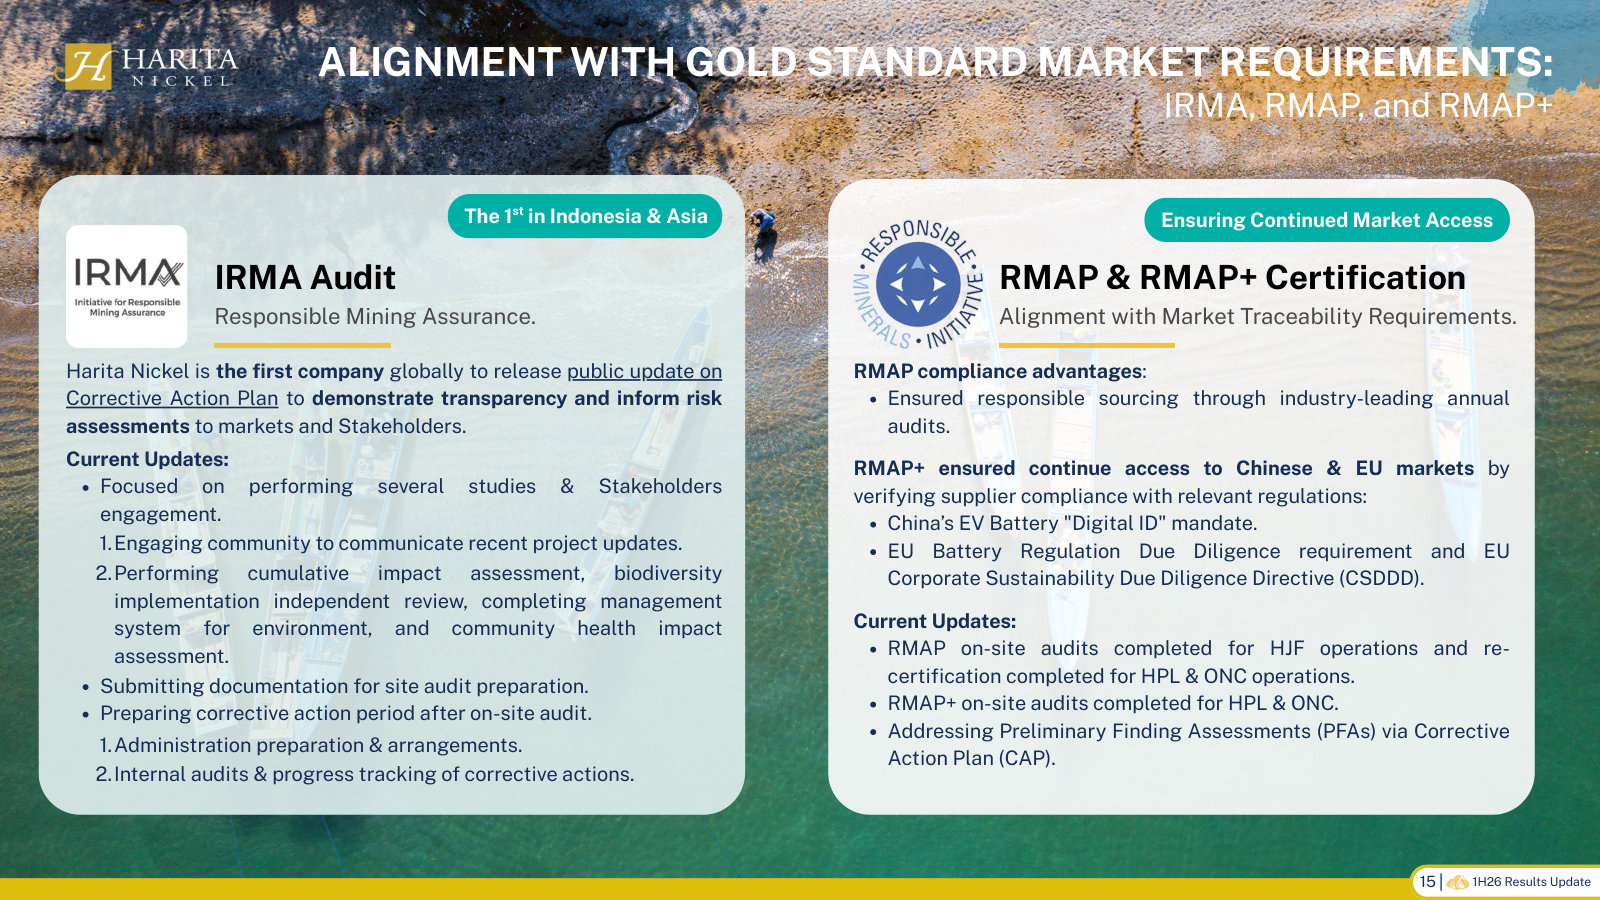
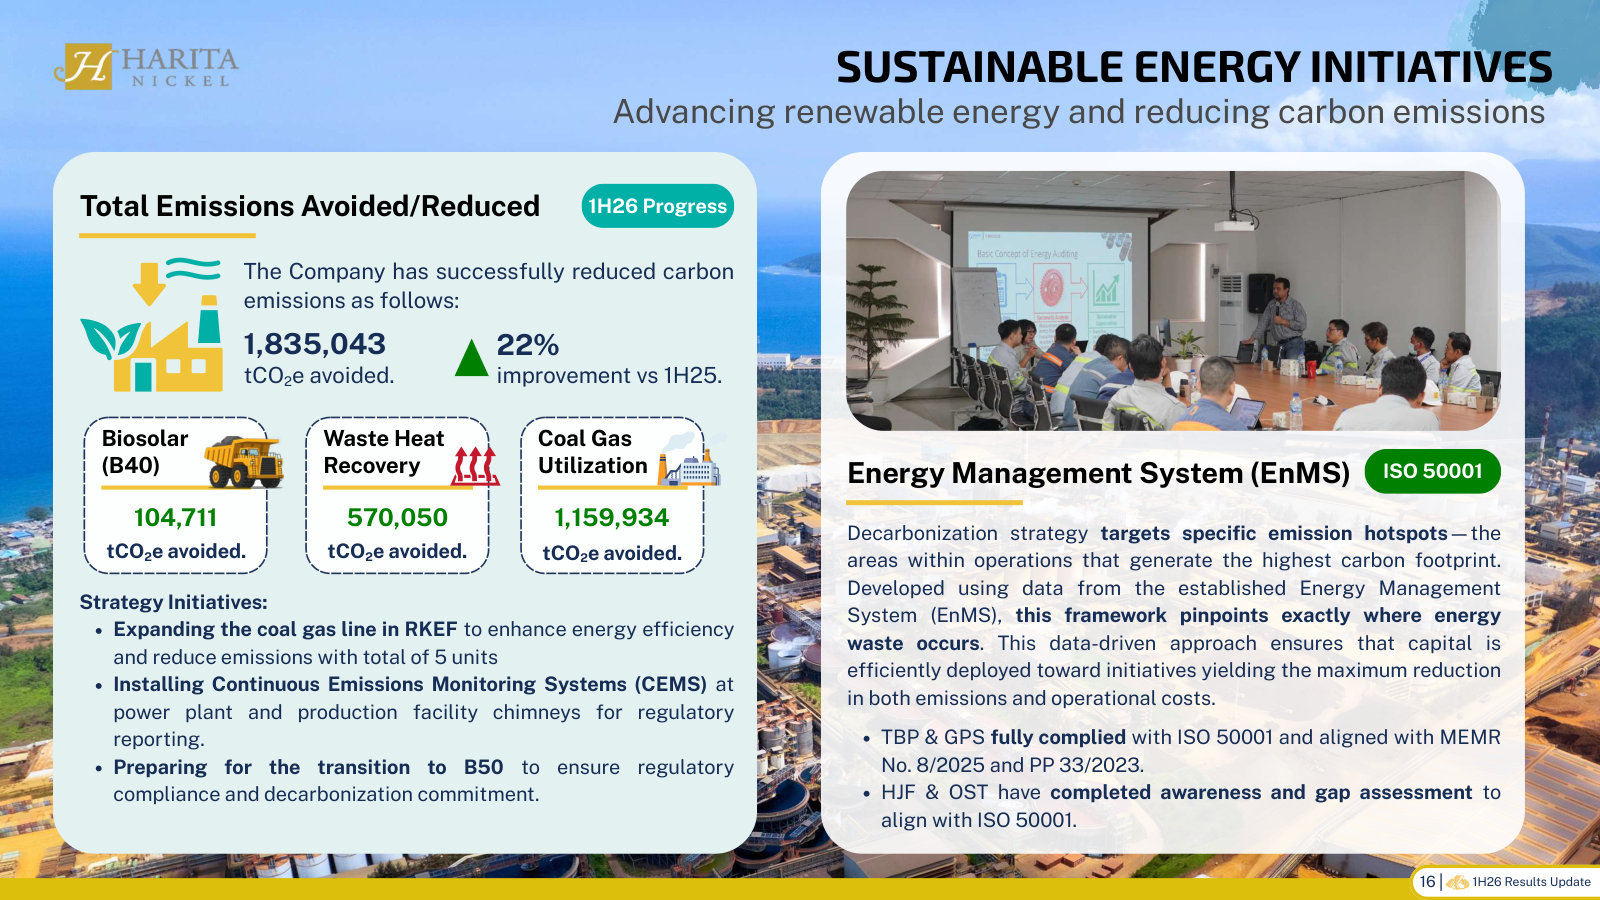
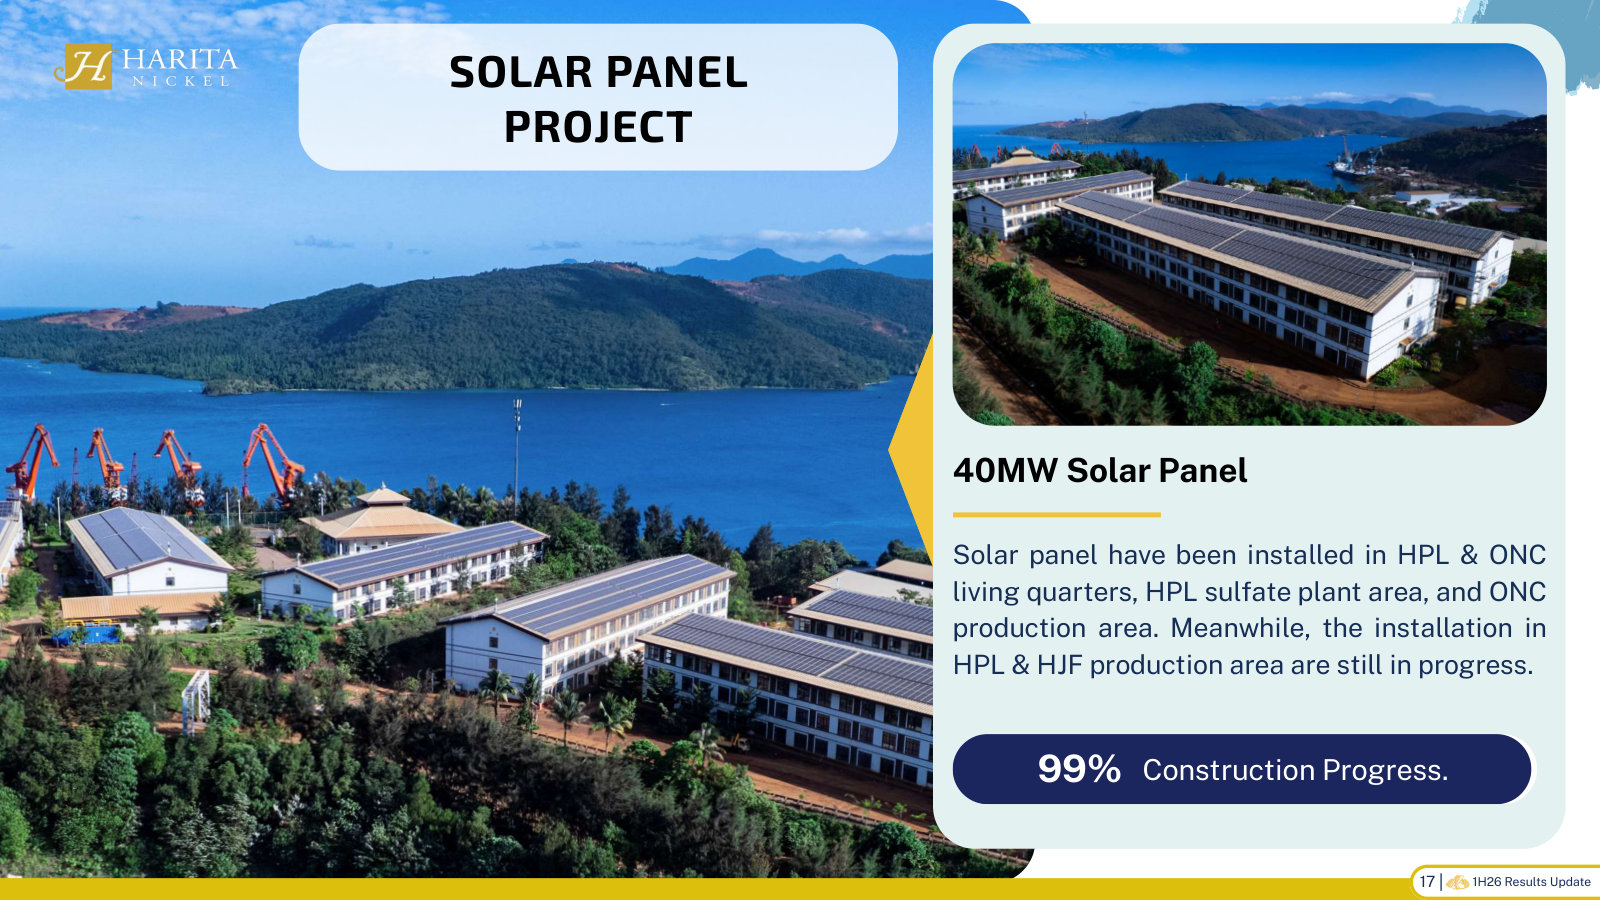
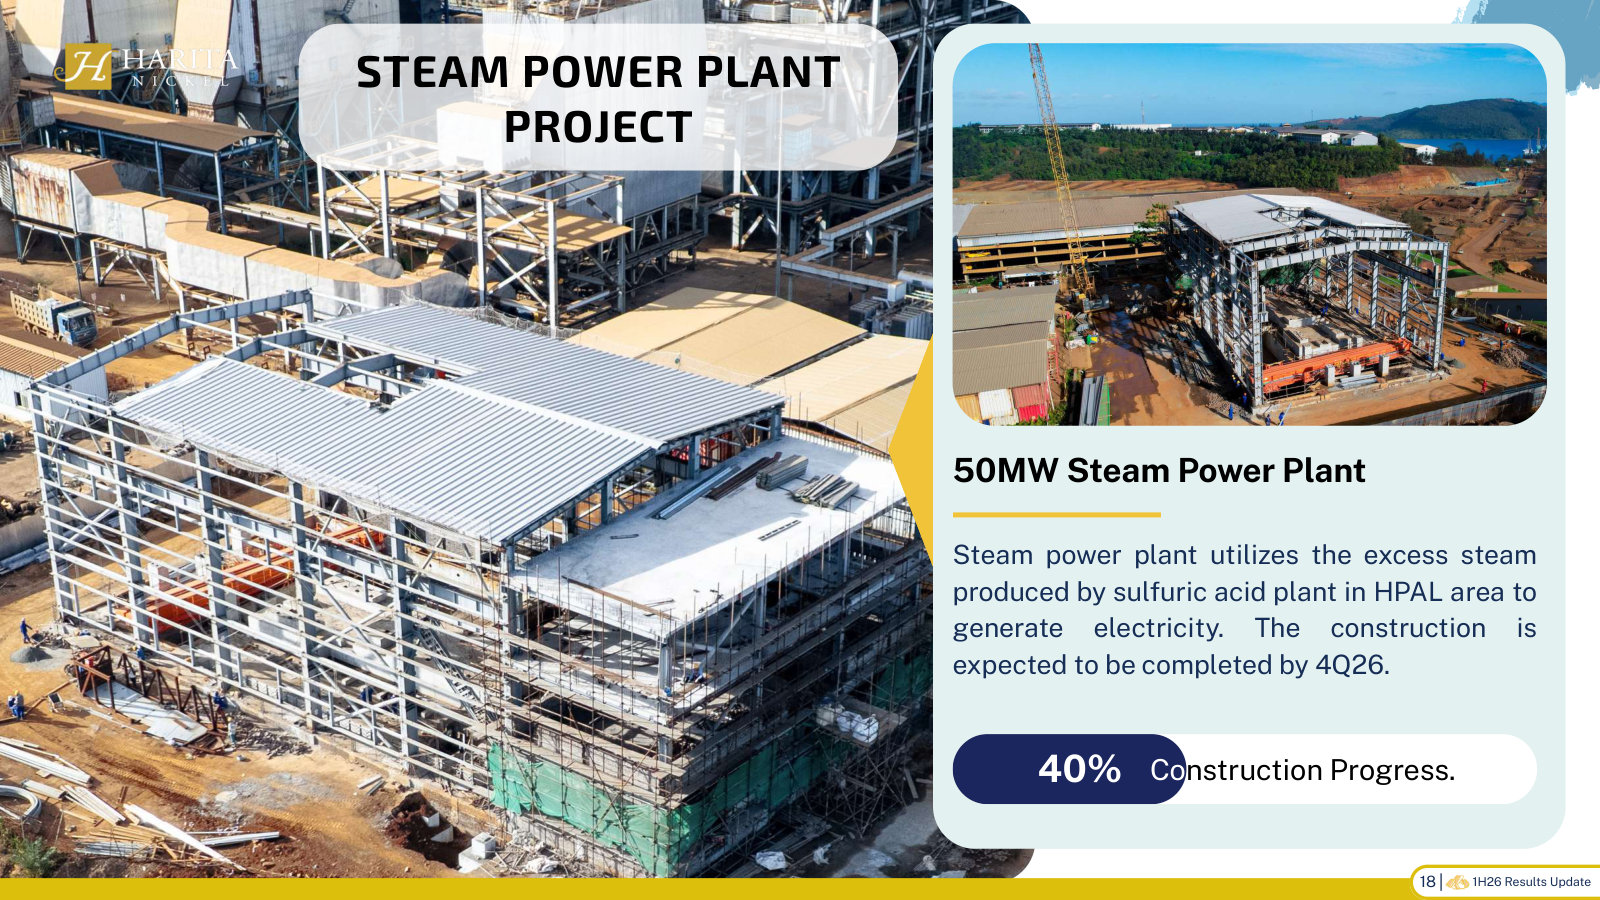
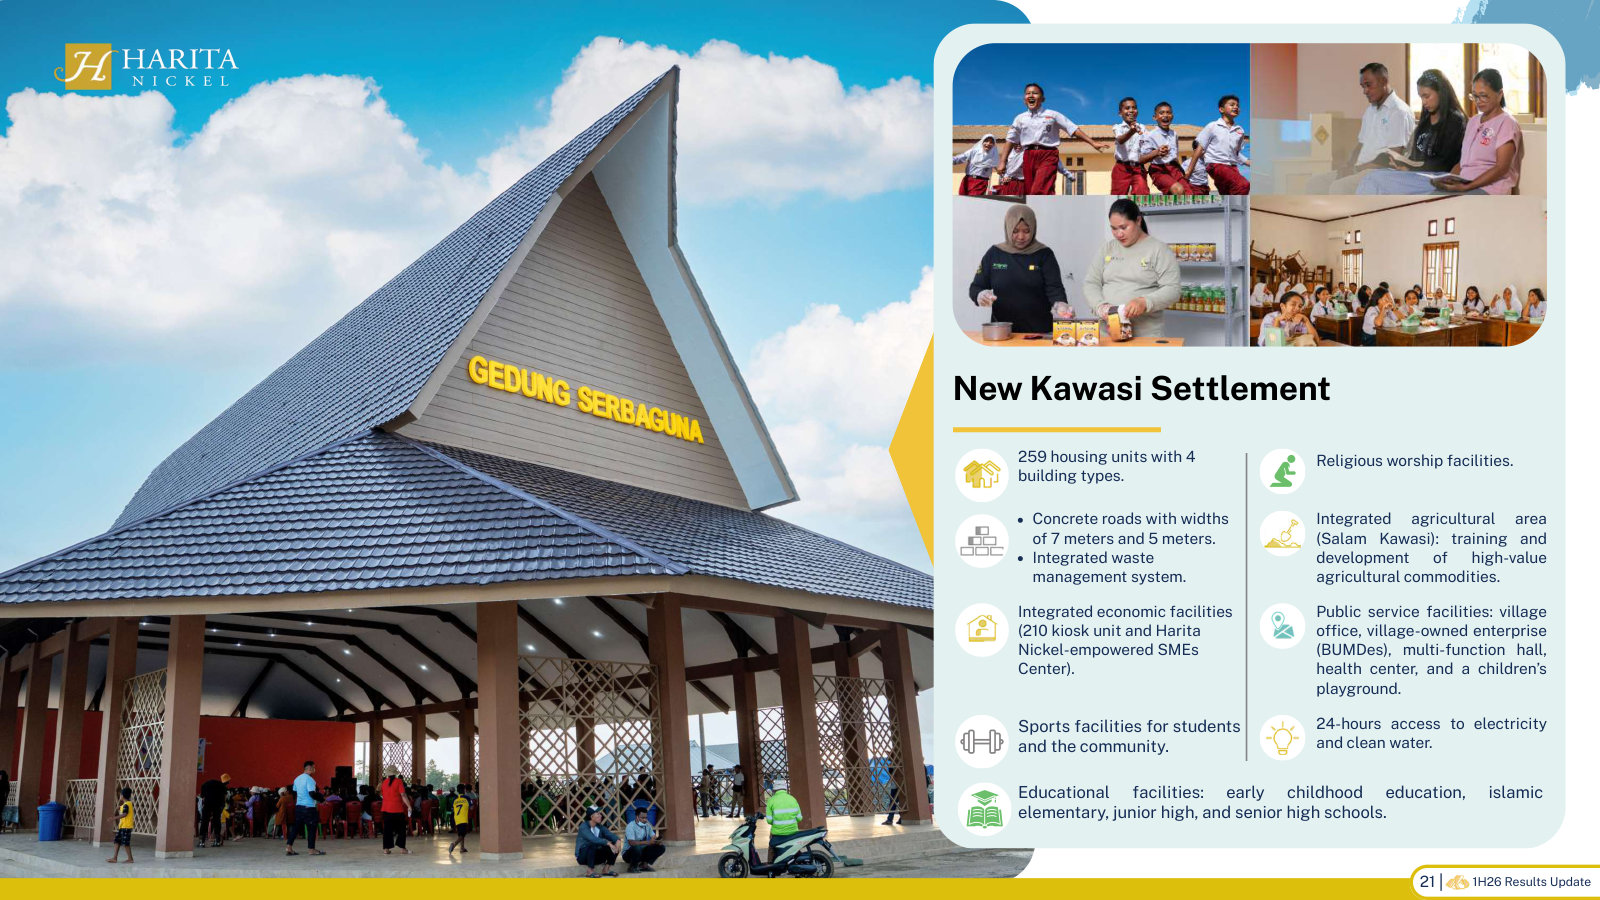
Company Presentation FY23 — Analyst Call — FY2023
The FY23 deck — the clearest look at the physical asset base: concession map, ports, the capacity roadmap and per-product cash margins. · Open the full document →
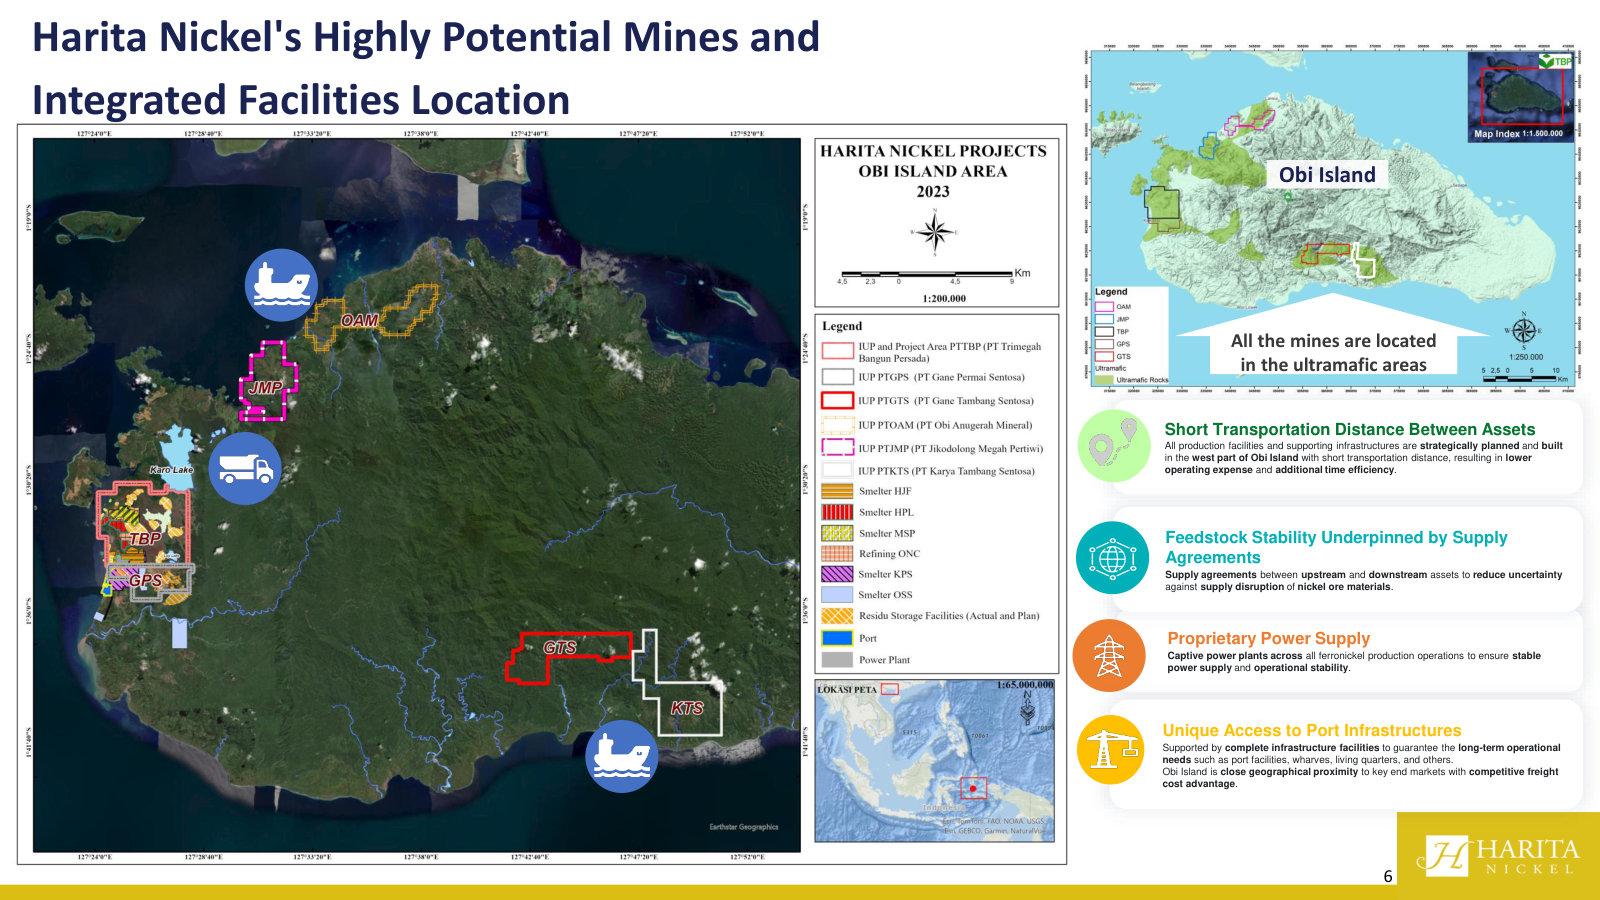
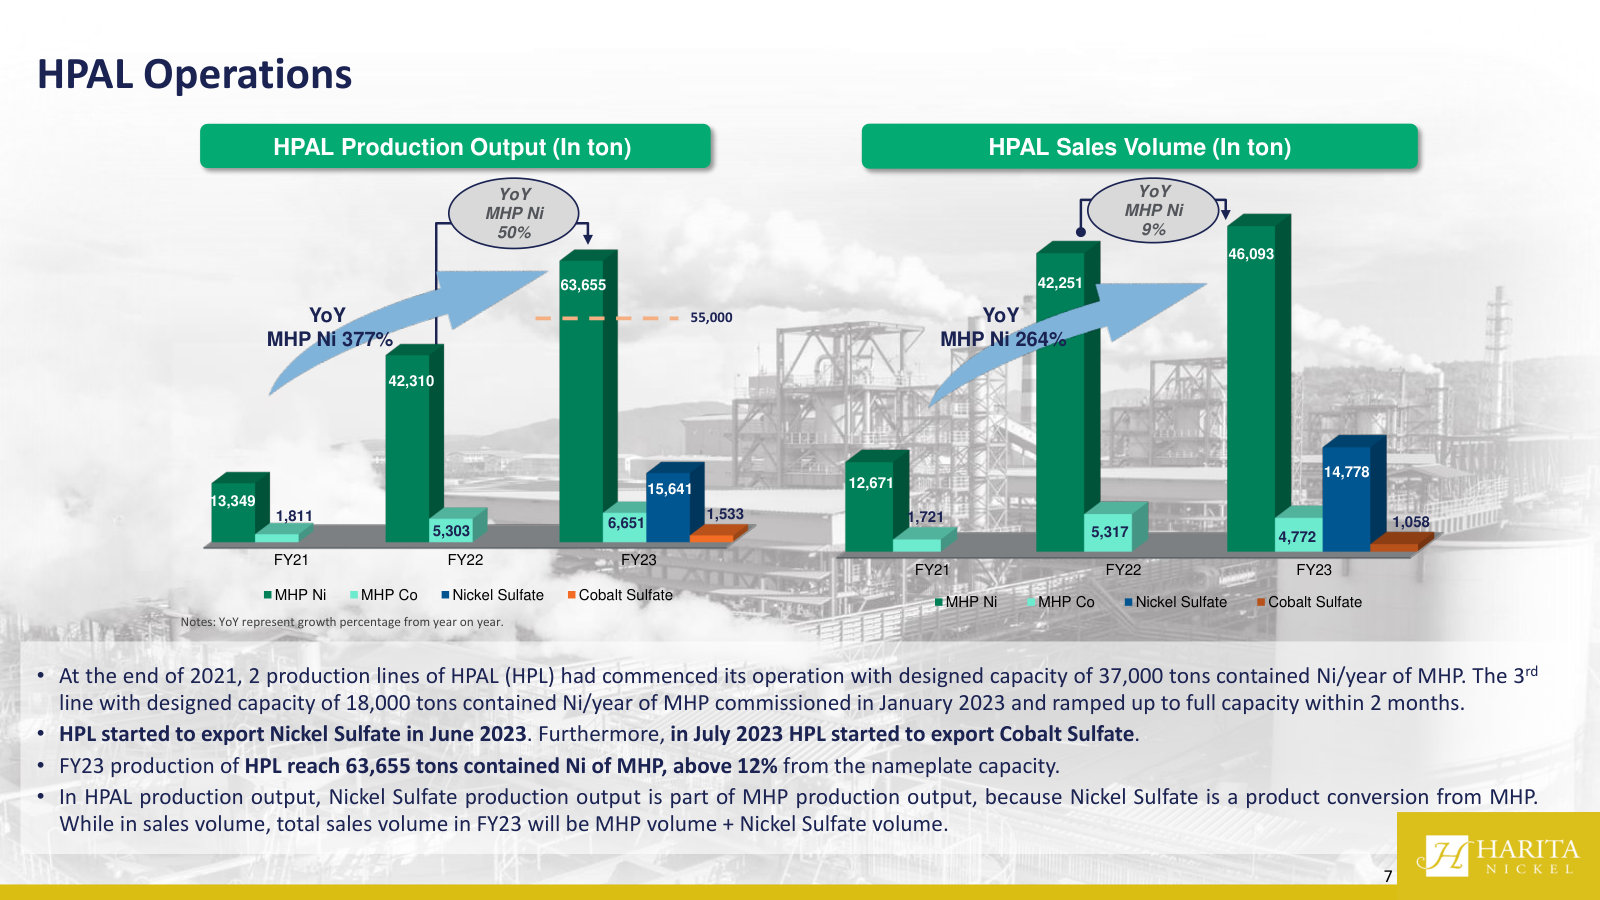
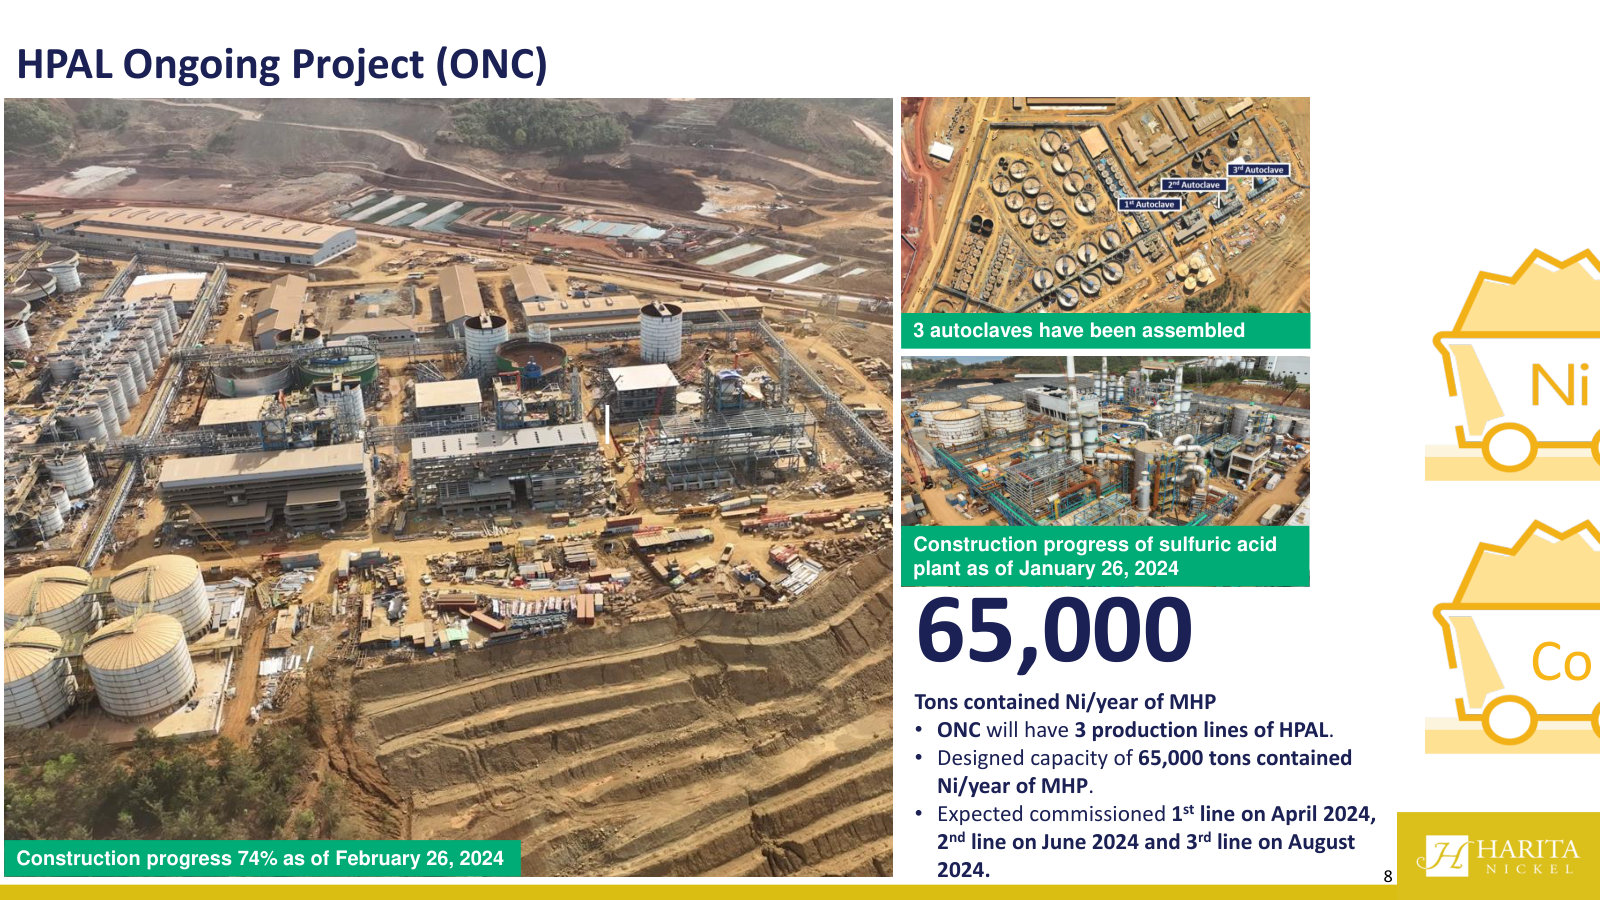
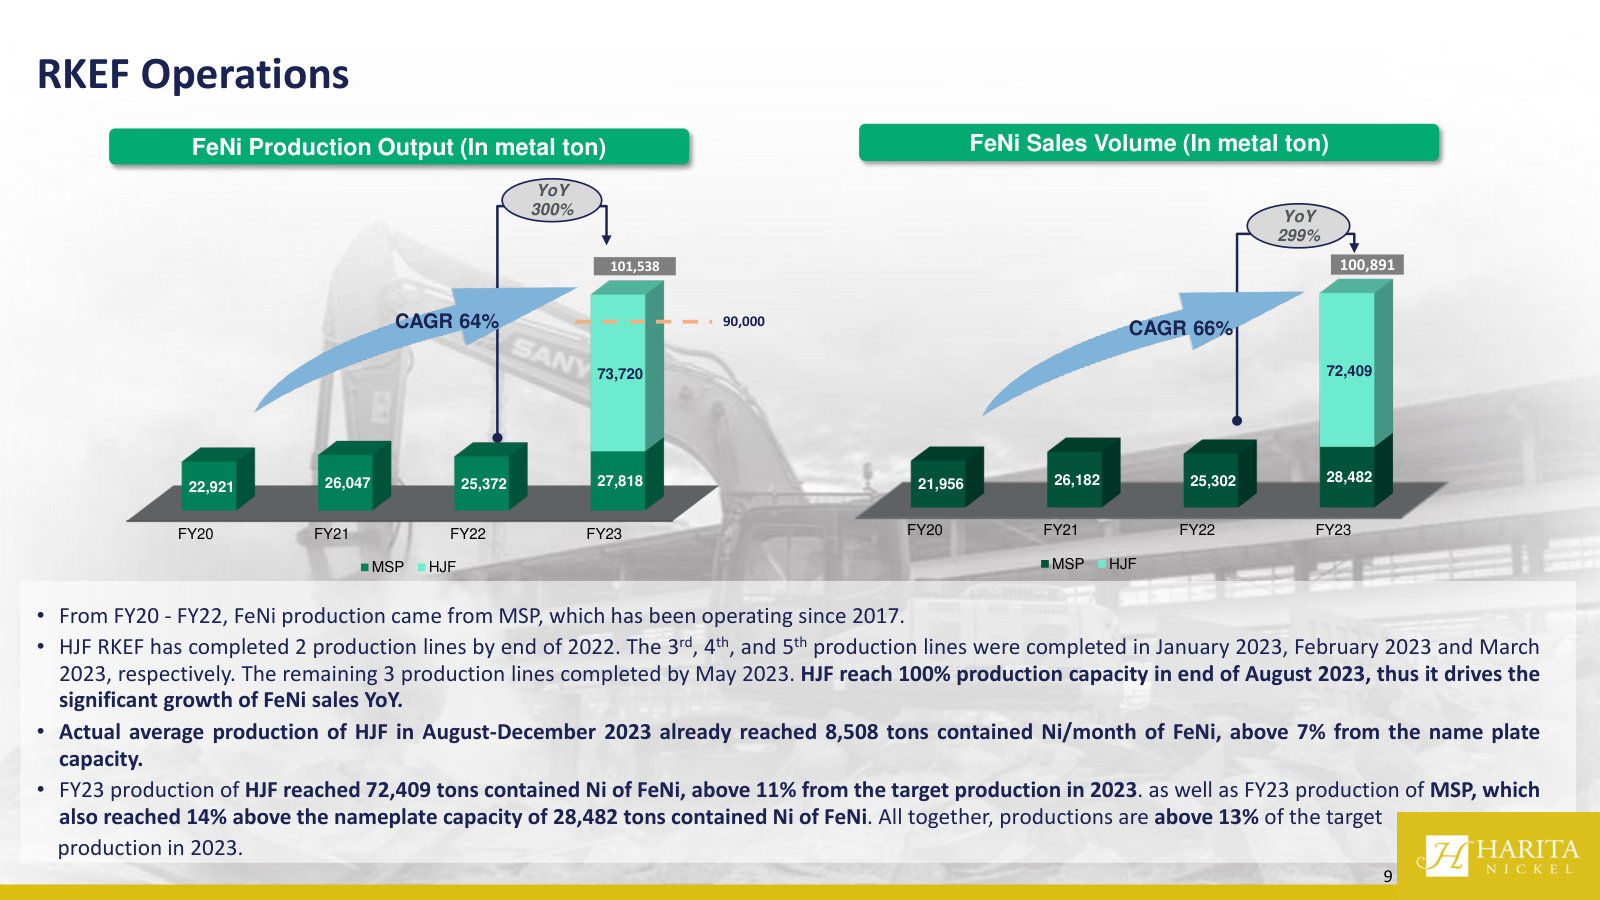
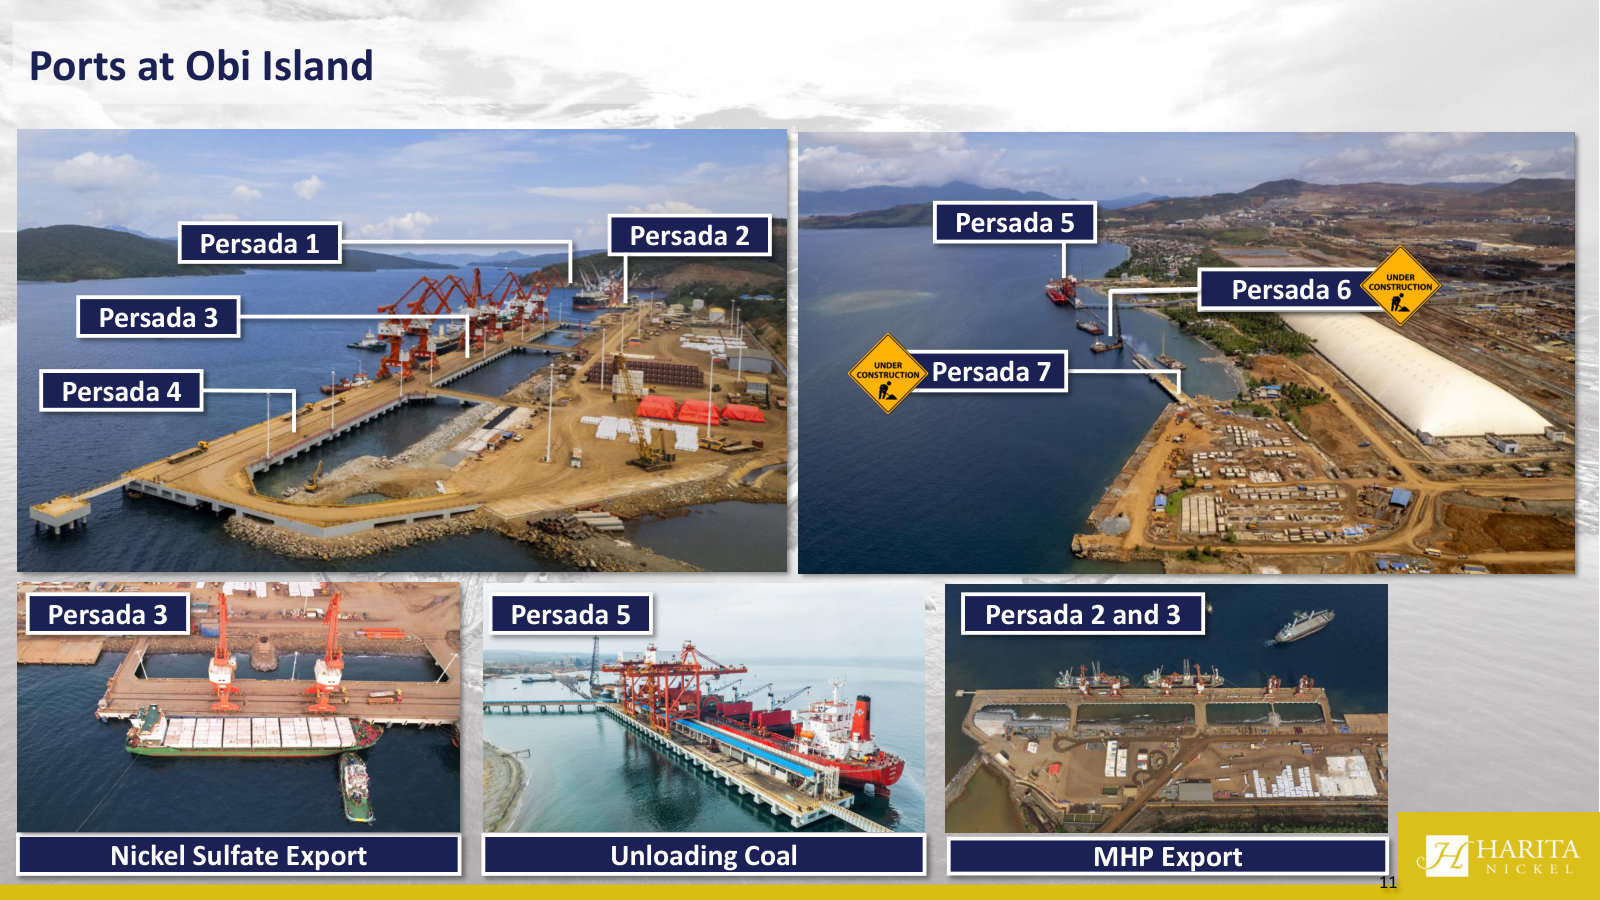
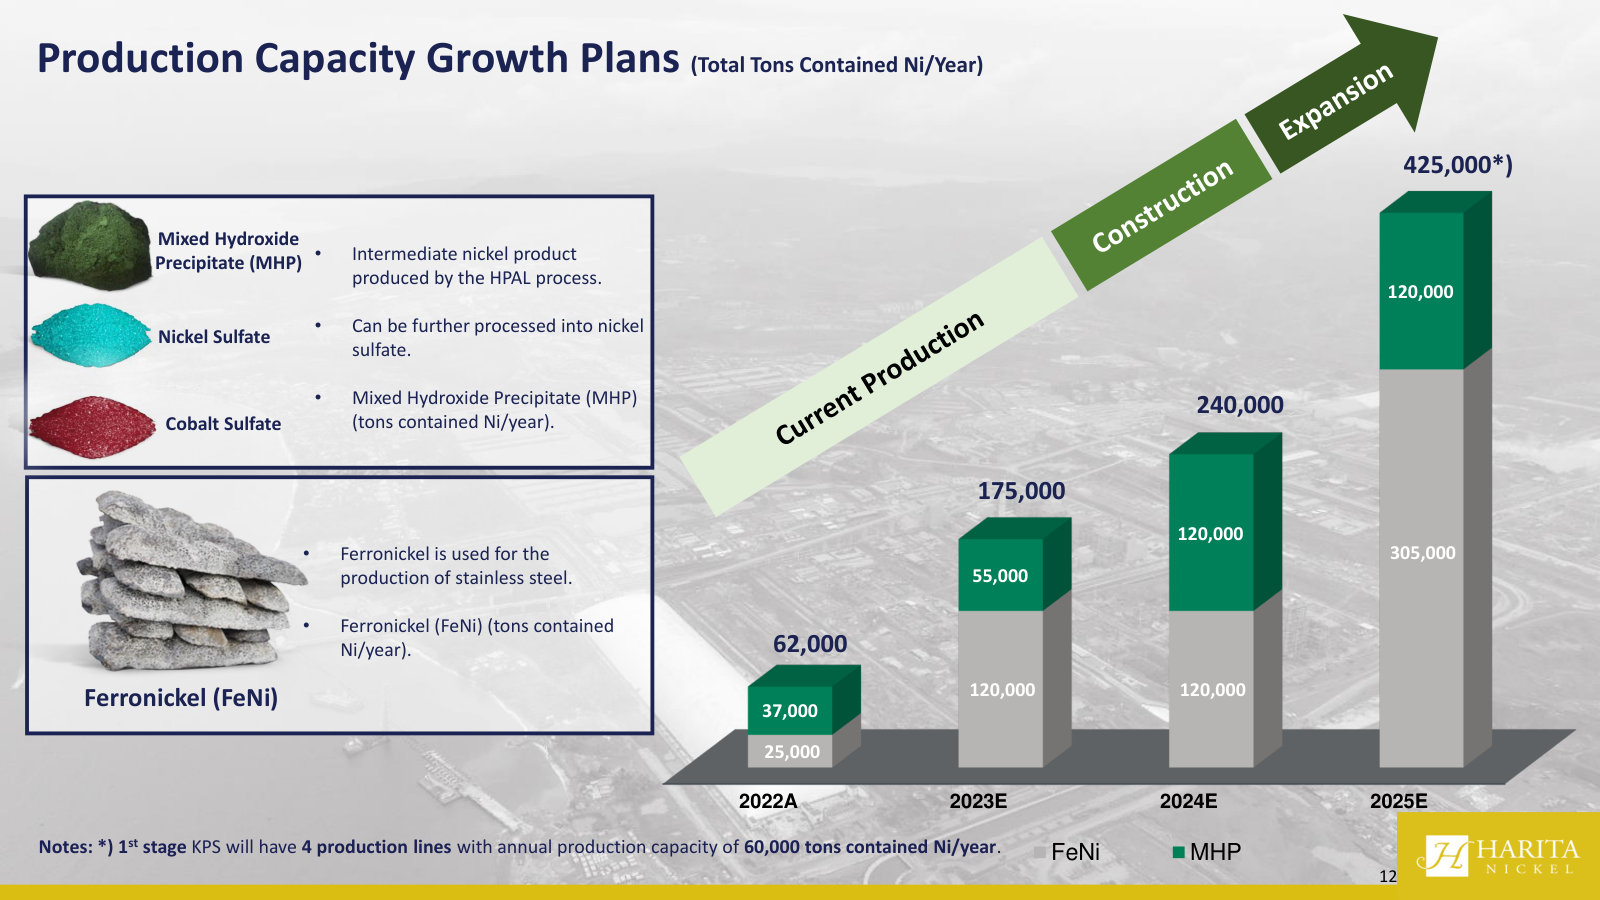
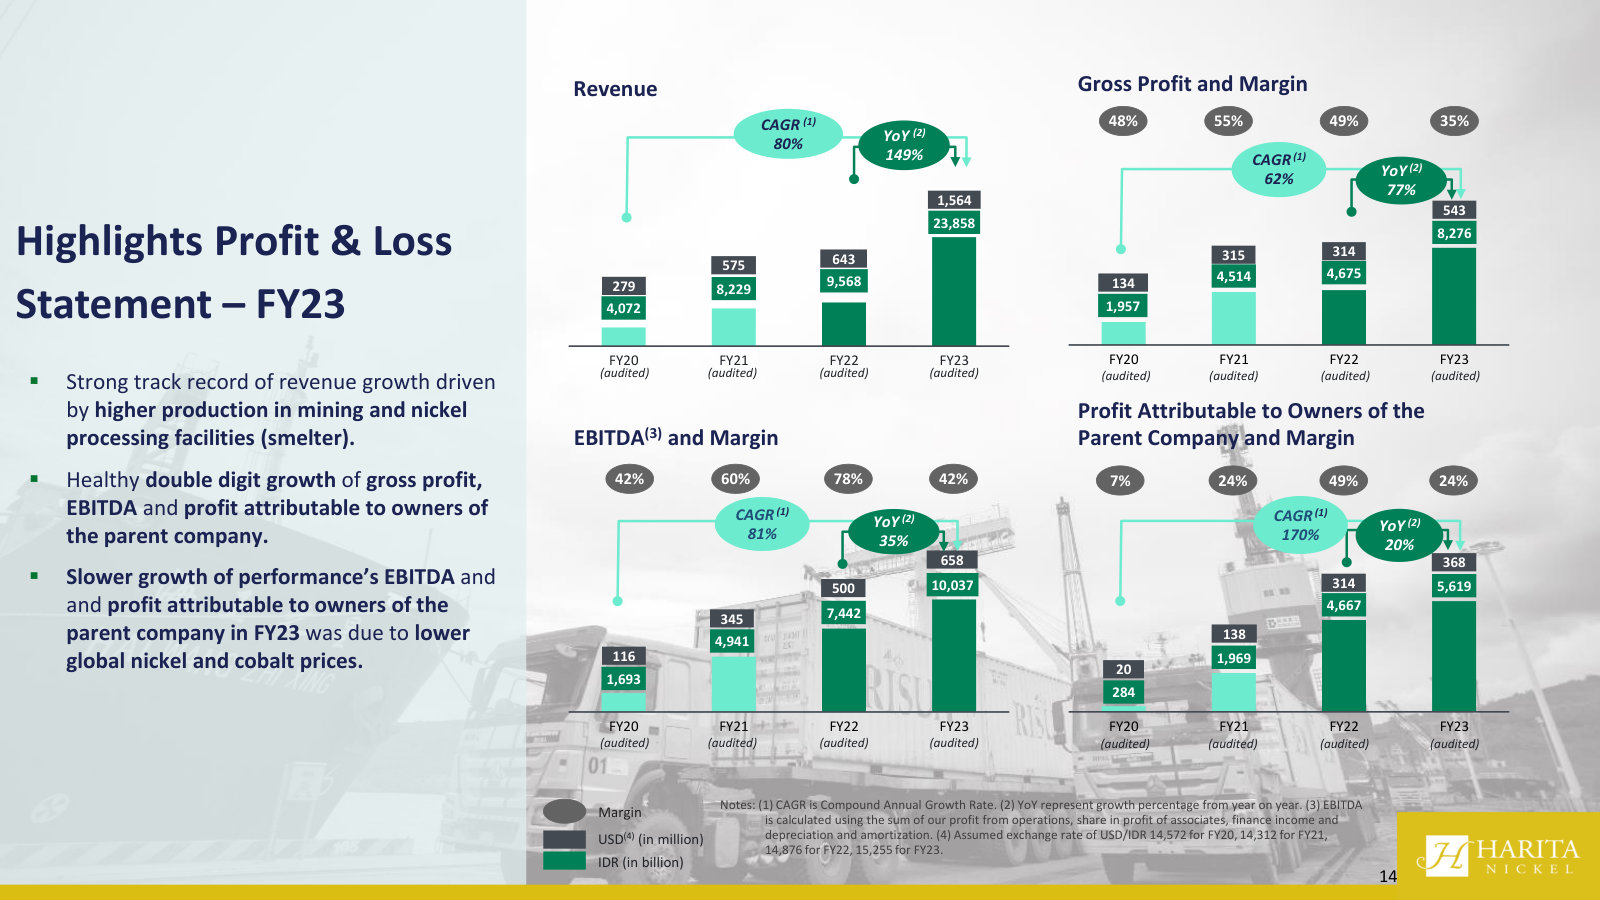
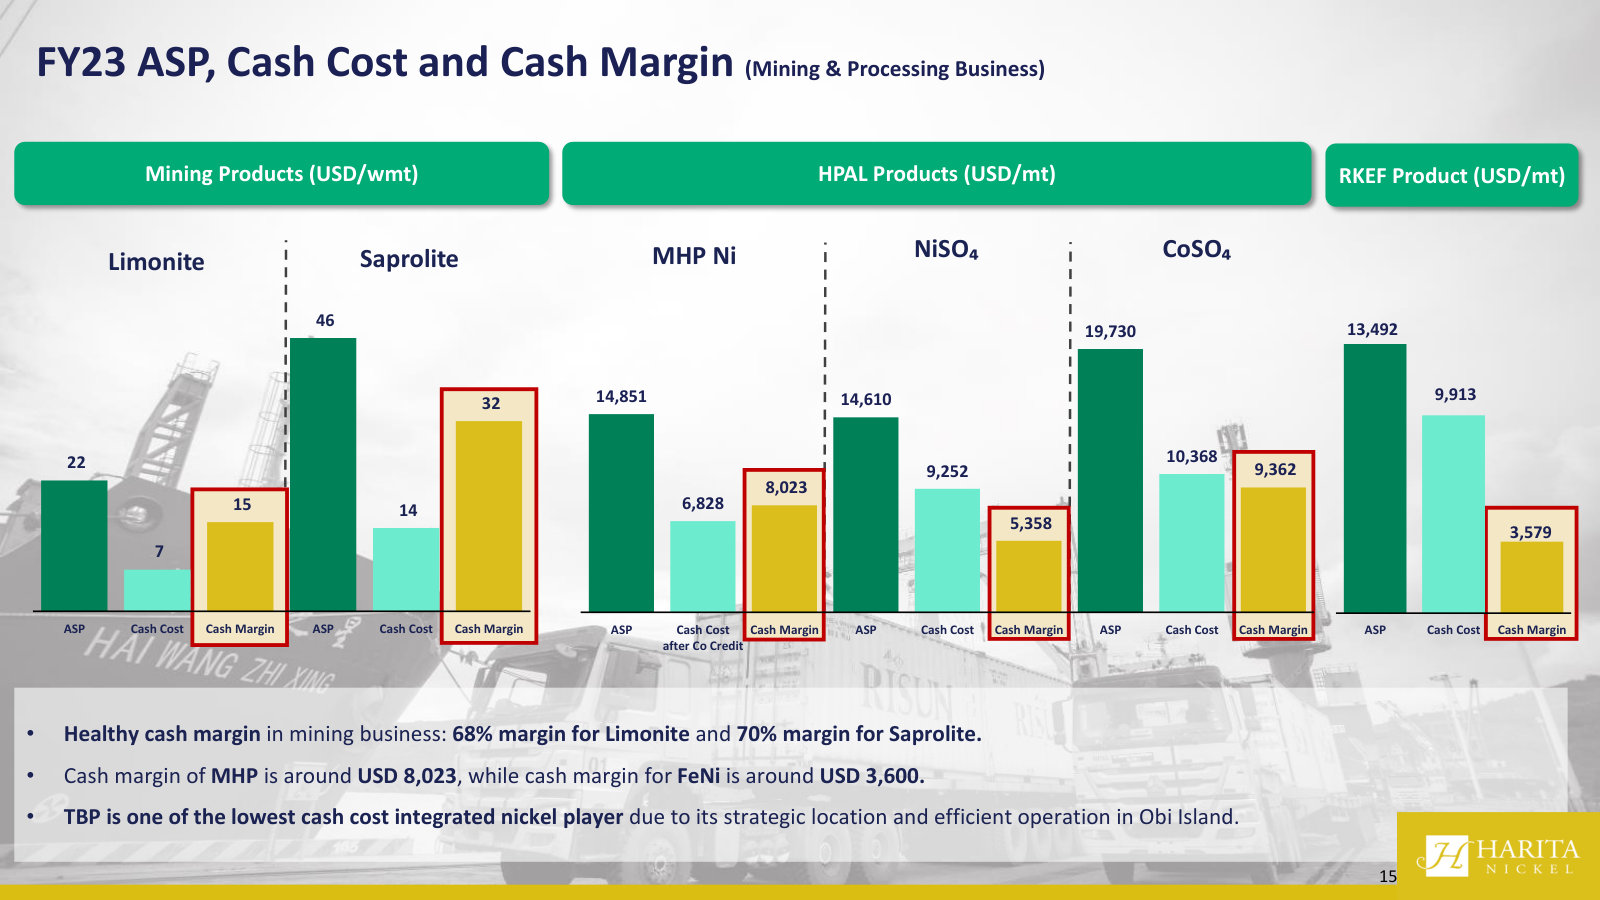
Analyst & Investor Briefing 1H 2023 — 1H2023
The IPO-year briefing, and the only deck that explains the whole company from scratch: structure, value chain, assets and unit economics. · Open the full document →
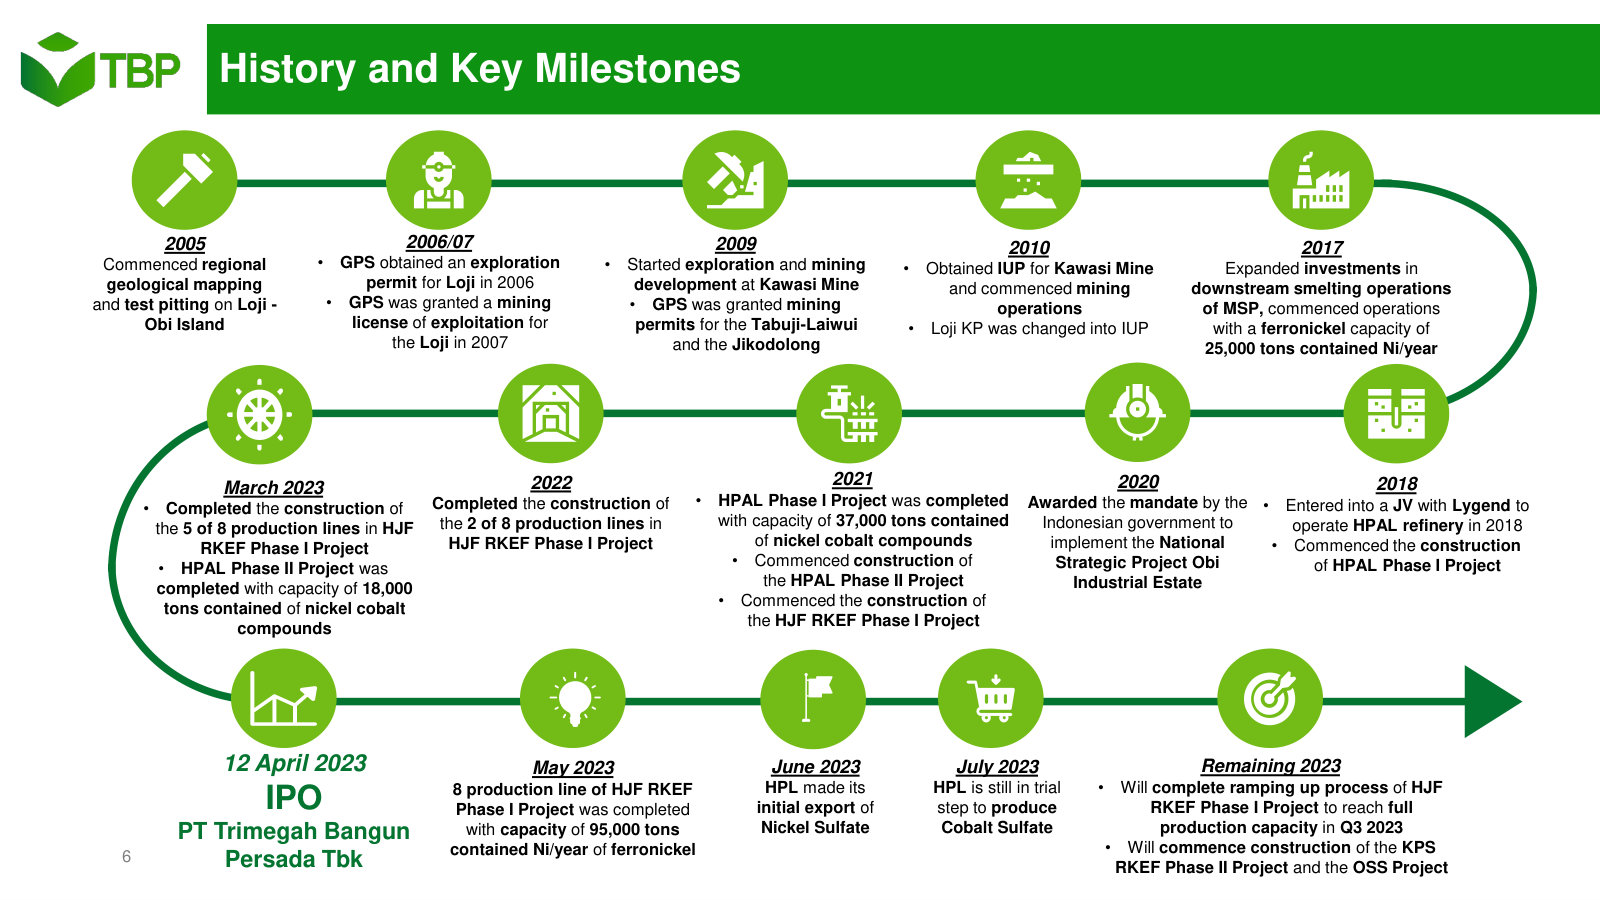
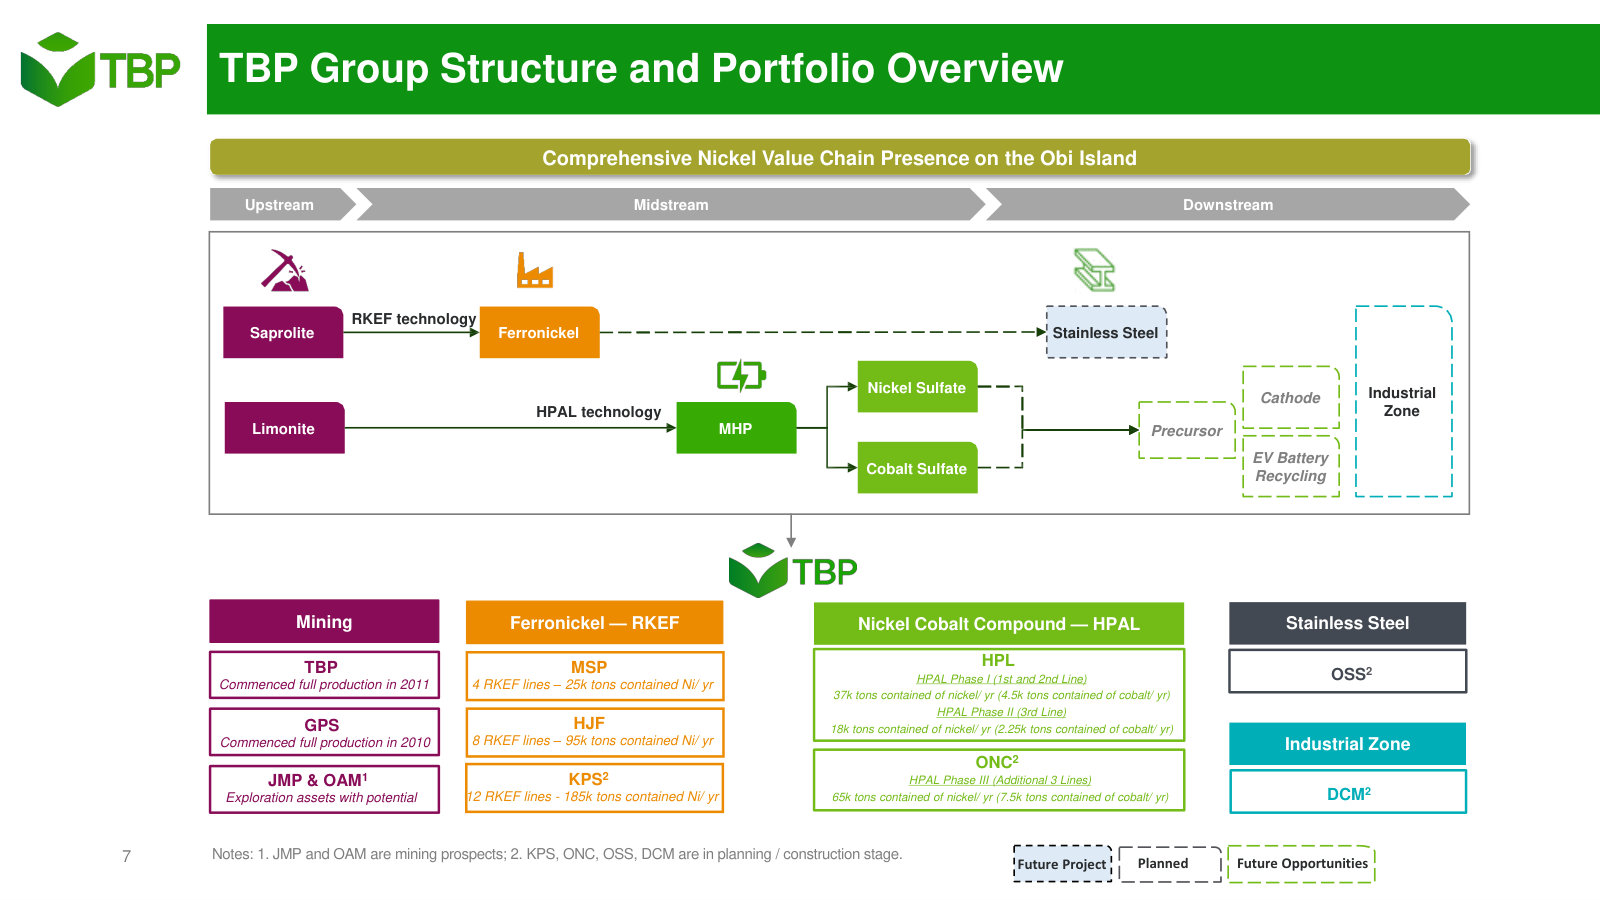
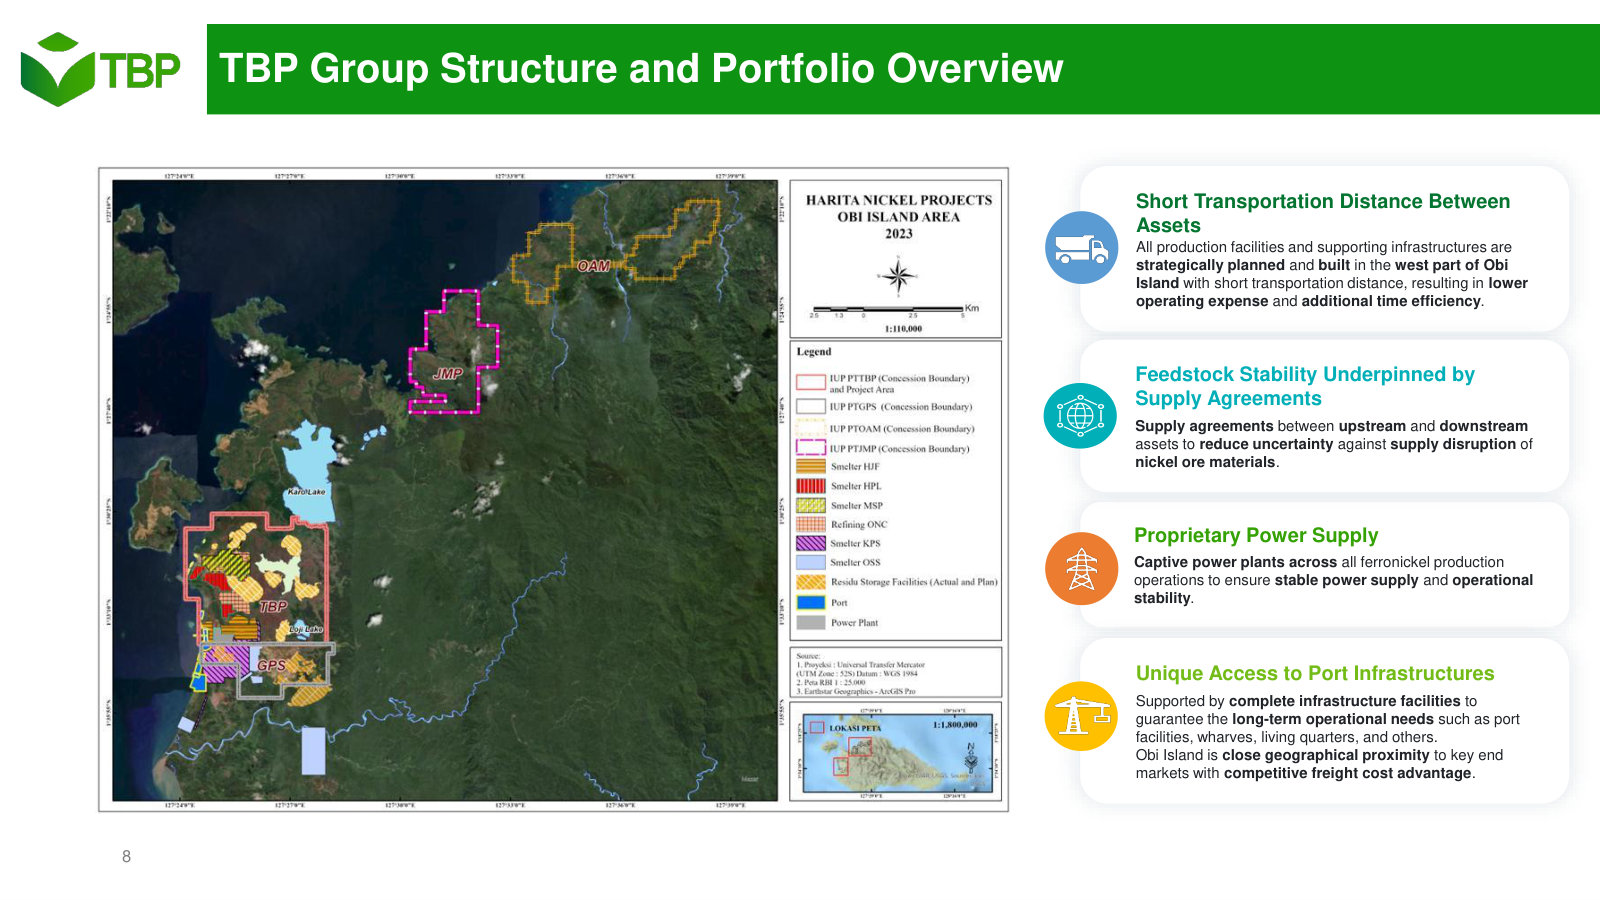
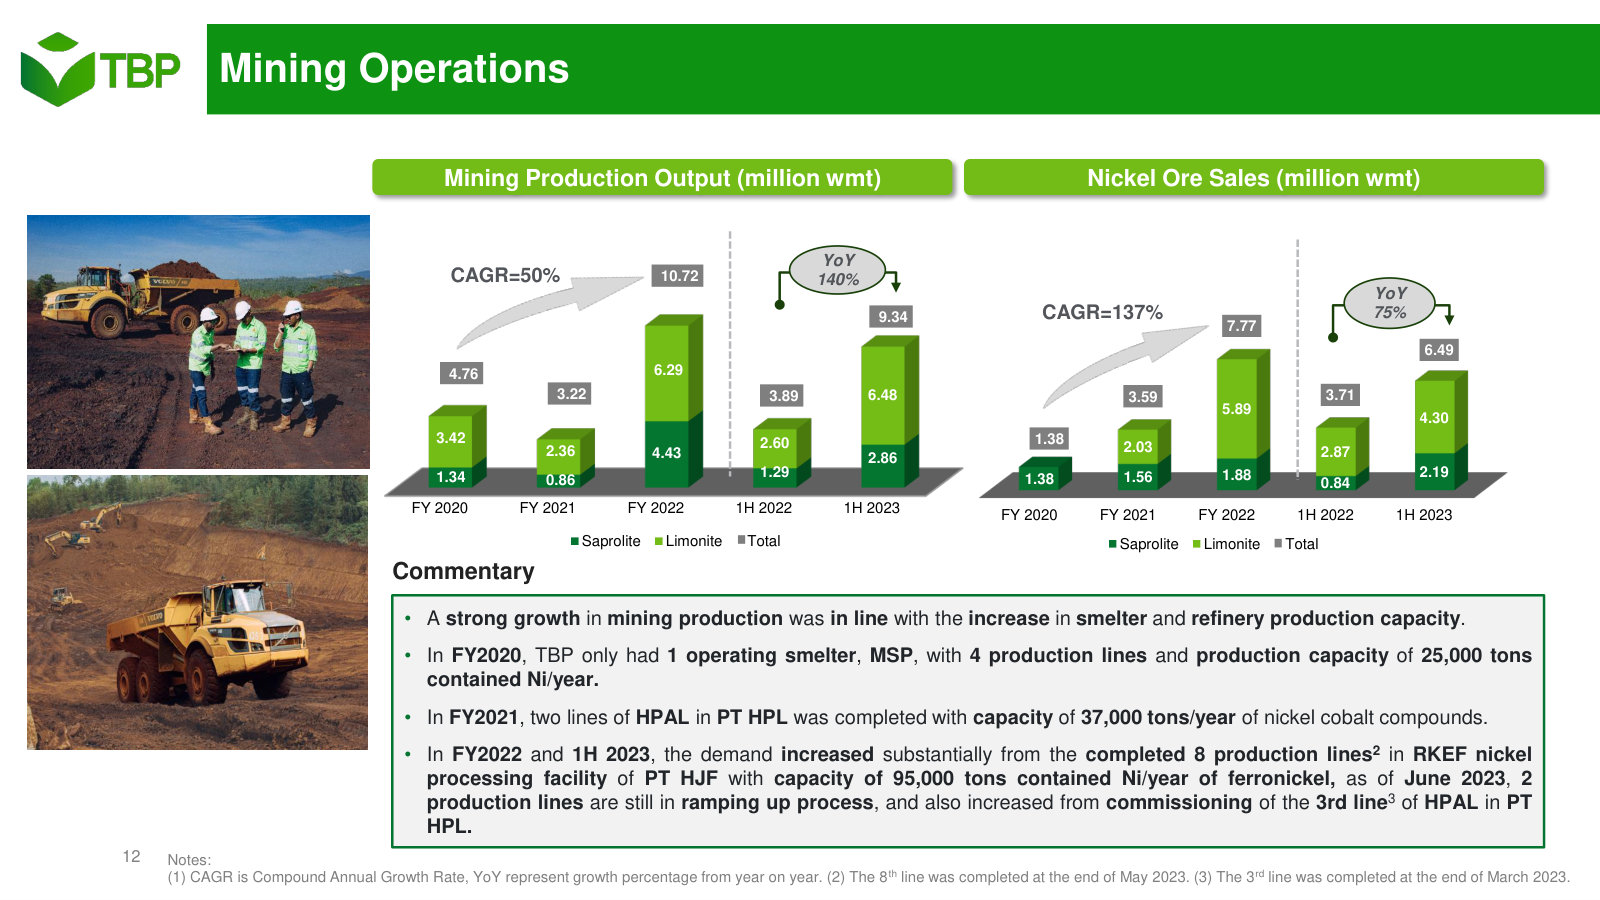
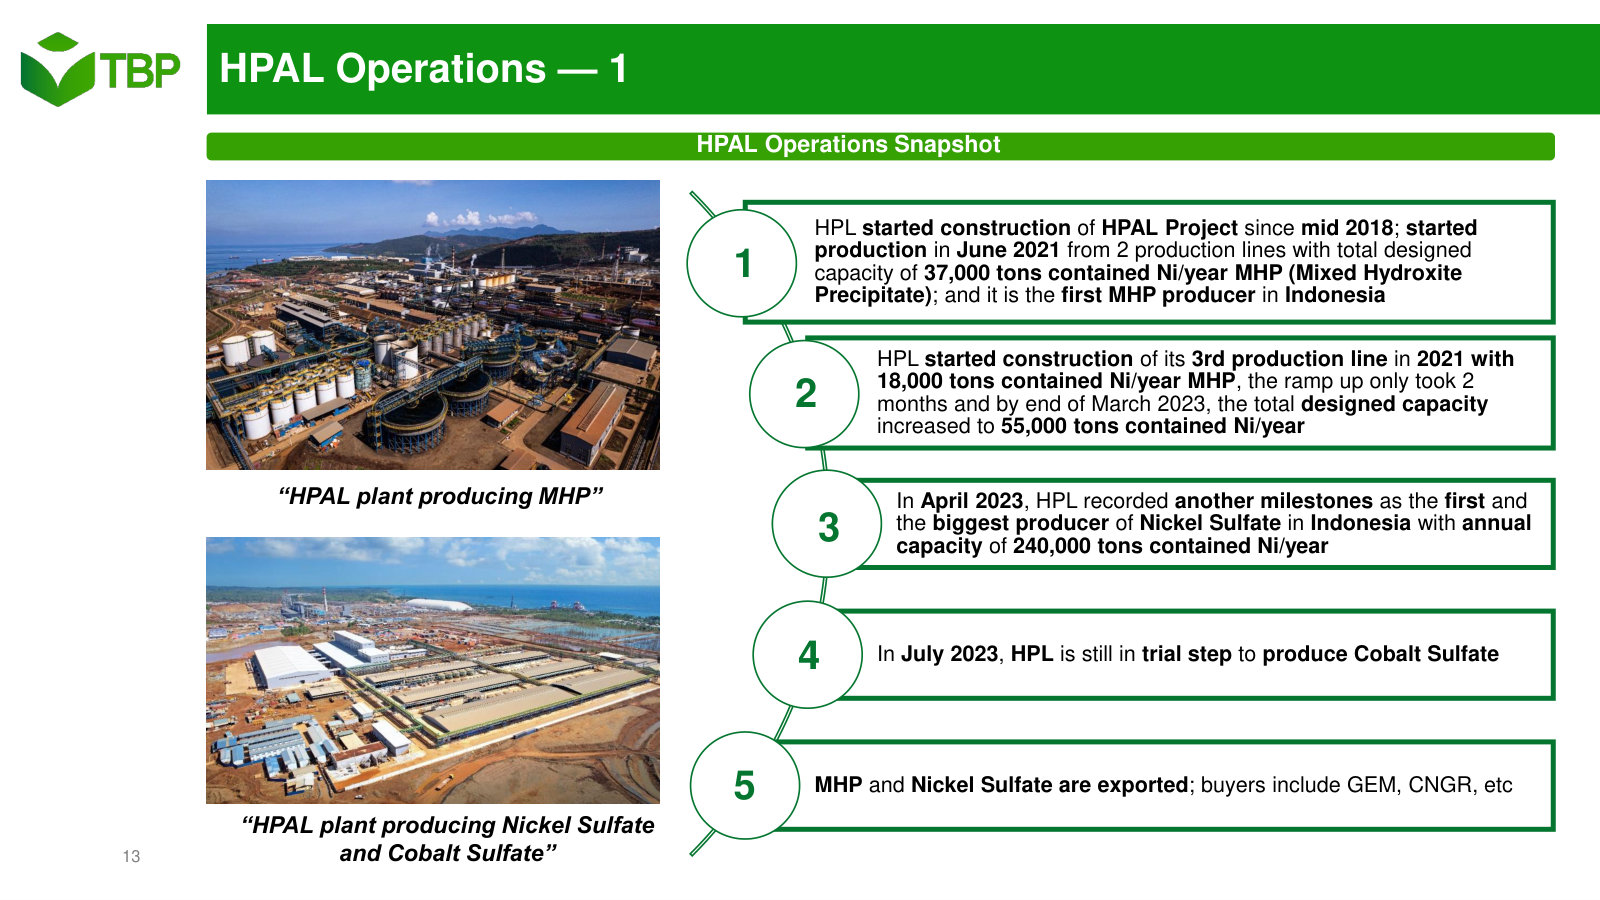
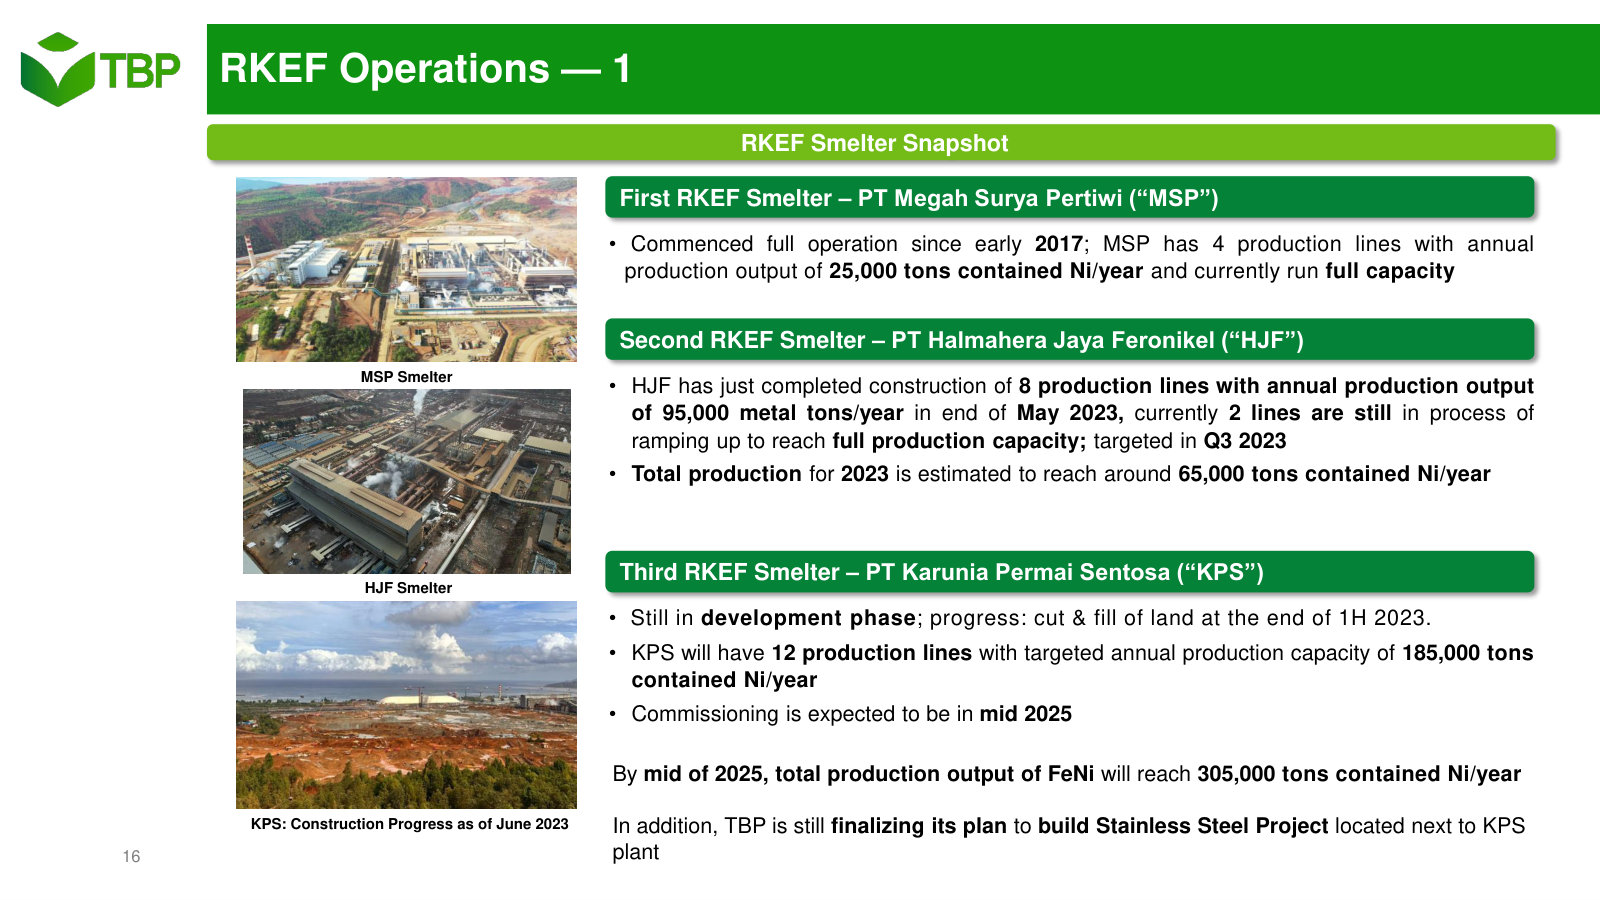
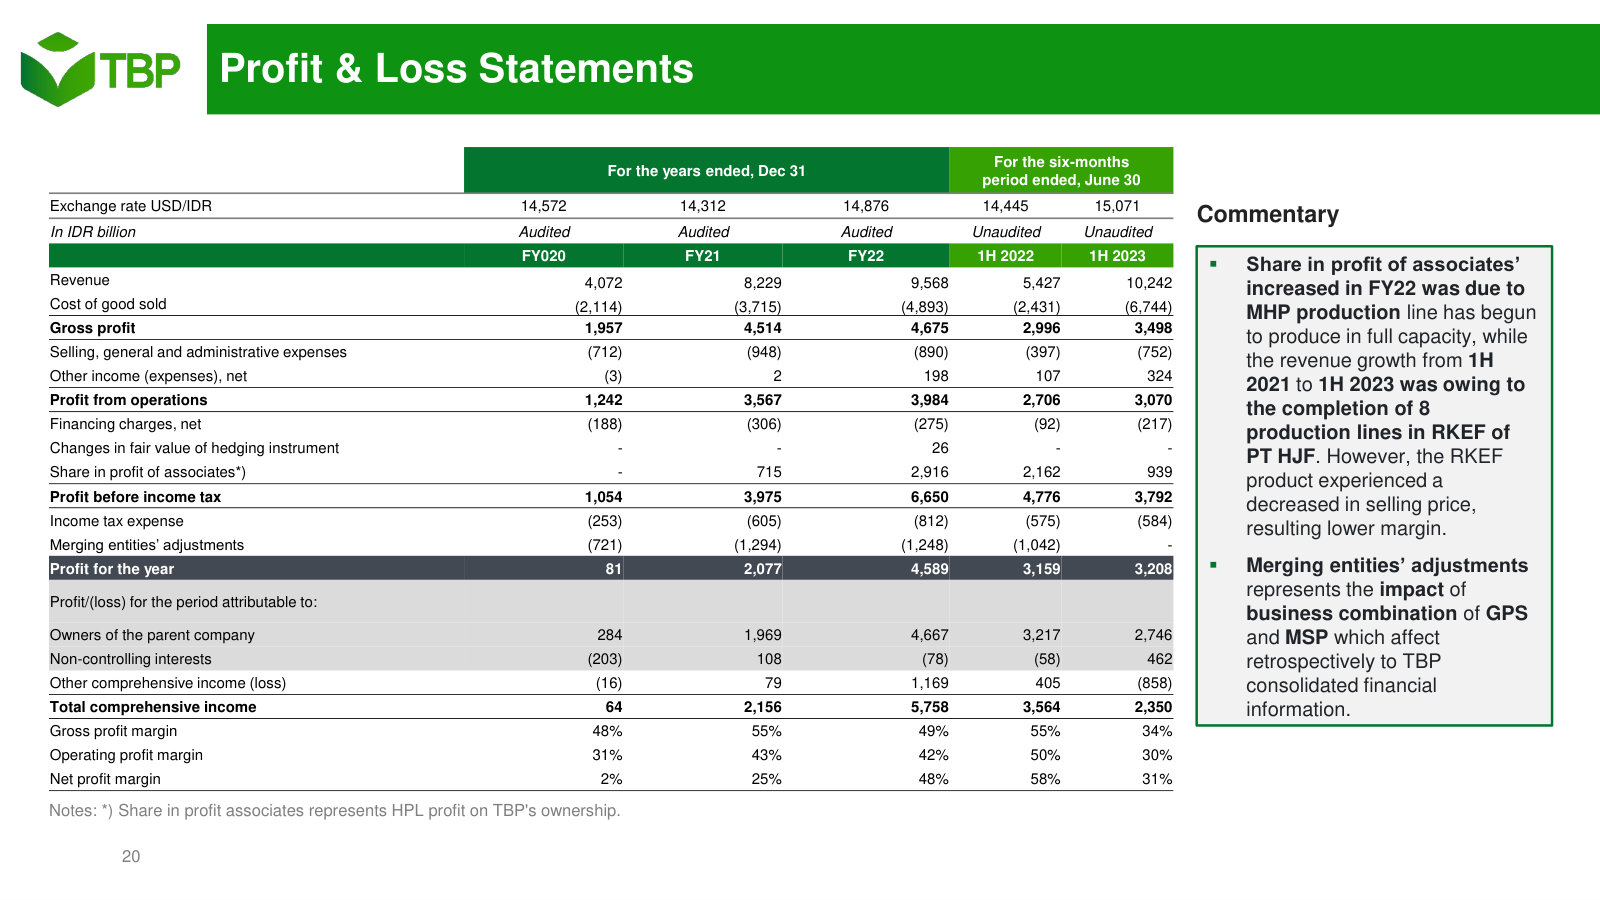
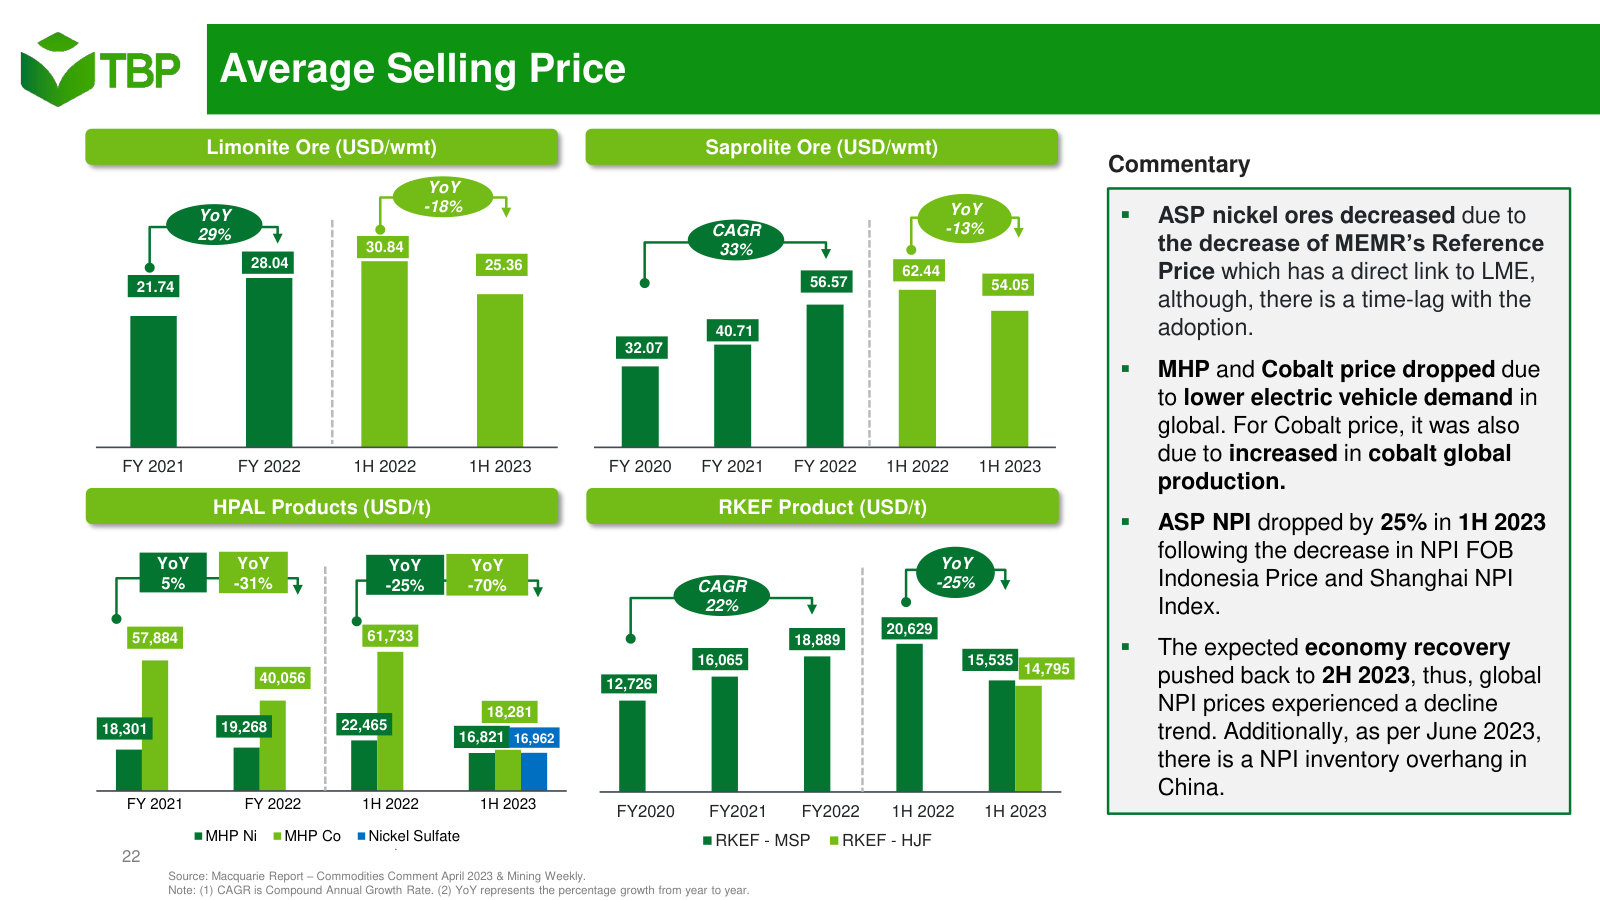
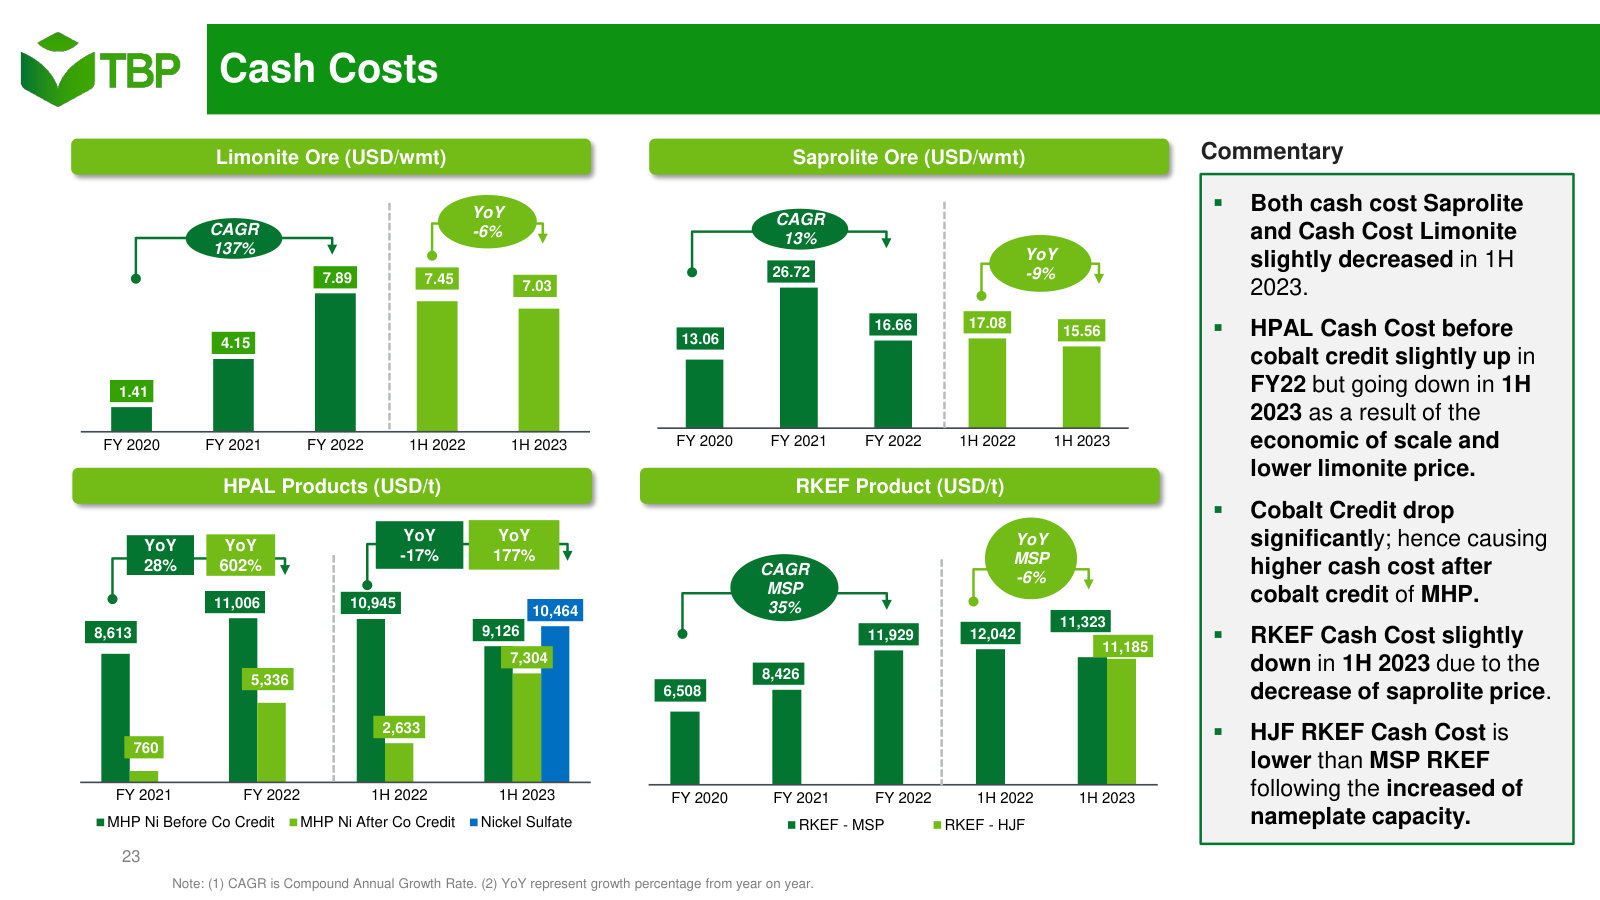
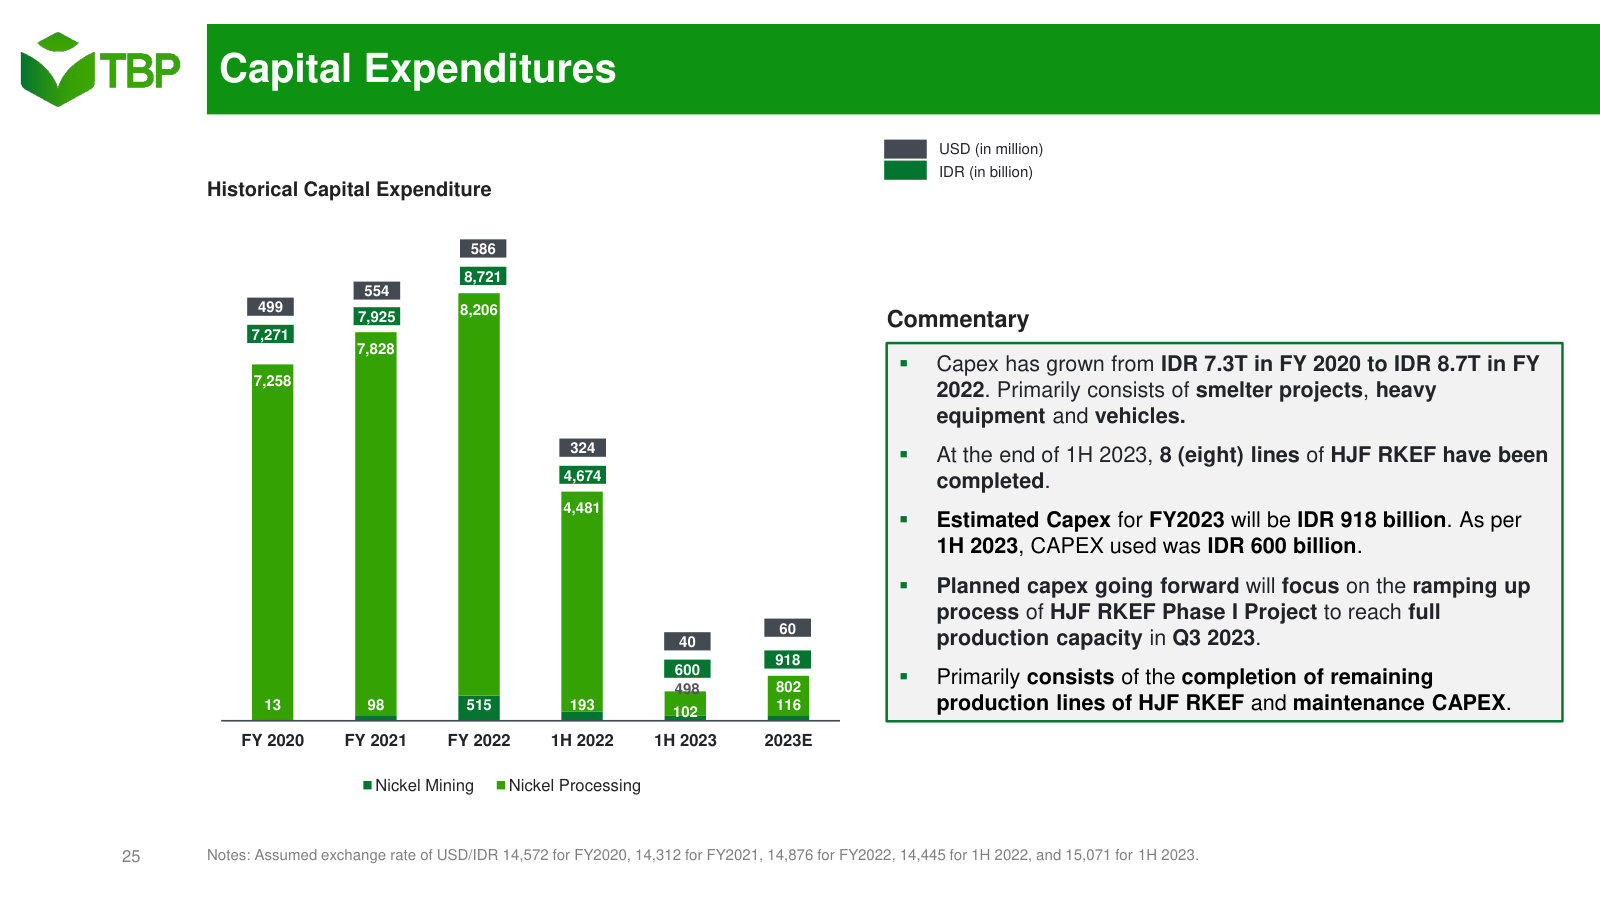
More from management
Public Expose 2026 — 2026 · 23 pages · The annual IDX Public Expose — the same 2026 material presented to retail holders, with the board line-up and a Q&A session. · Open →
Analyst Call FY25 & 1Q26 — FY2025 / 1Q2026 · 28 pages · Audited FY25 results and the FY25 dividend, plus a nature-risk and TNFD readiness slide that appears nowhere else. · Open →
Analyst Call 9M25 — 9M2025 · 22 pages · The 2025 reserve and resource statement — 310.8mn wmt of limonite and saprolite — and the new GTS mine in south Obi. · Open →
Public Expose 2025 (English) — 2025 · 23 pages · The 2025 Public Expose in English: water management and watershed rehabilitation detail, plus a live Q&A. · Open →
Company Presentation FY24 — Analyst Call — FY2024 · 20 pages · FY24 results and the first full description of the CKM quicklime plant, jetties 5a and 7, and the GTS exploration programme. · Open →
Company Presentation 9M23 — Analyst Call — 9M2023 · 30 pages · Reserves as of 2023, the reserve-replacement strategy and the GPS/GTS acquisitions — how the ore base gets extended. · Open →
PT Trimegah Bangun Persada Tbk's management answers for the business every quarter. These are the exchanges that explain it best — verbatim, from the call transcripts preserved in Sources. Each link opens the full transcript at that page in a new tab.
Annual Public Expose 2026 — Q&A Minutes — Public Expose 2026
The most recent management Q&A: the LFP-versus-nickel demand challenge answered head-on, sulfur supply after the Strait of Hormuz closure, and why a higher-margin mining segment still matters less than smelting. · Open the full transcript →
IRMA certification, promised for early 2025 in the 2024 expose, is still in corrective action two years on.
Naufal A (individual investor); PT Trimegah Bangun Persada management: What is a progress update on the IRMA audit process? […] With regard to the IRMA audit process, the Company convey that the audit has been ongoing since 2024 and remains in progress. The Company is currently in the corrective action period, in accordance with the auditor's recommendations provided during the initial audit, in order to carry out improvements and corrections prior to re-verification by the auditor. The Company expects the auditor to conduct a re-verification within this year.
p. 2 · Read in context →
The hardest question of the session: if LFP owns 80% of China, who absorbs Indonesia’s HPAL output?
Bagus Permadi Prayitno (individual investor); PT Trimegah Bangun Persada management: Given that LFP chemistry currently captures roughly 80% of the EV battery market in China, what is the basis for investor confidence that the demand for MHP and nickel sulfate will remain sufficient to absorb the total output from Indonesia’s expanding HPAL capacity? […] With regard to the competitive dynamics between Lithium Ferro Phosphate (LFP)-based batteries and nickel-based batteries, the Company believes that these two battery types essentially serve distinct market segments. Nickel-based batteries are generally used in mid- to upper-class electric vehicles requiring greater energy storage capacity, as commonly found in the European and United States markets, which are characterized by long travel distances and relatively limited charging station infrastructure. Conversely, LFP-based batteries are more widely used in China, which has a greater number of charging stations, allowing vehicles with smaller battery capacities to operate optimally due to the higher frequency of charging that can be performed. Apart from this market segmentation, Nickel Cobalt Manganese (NCM) batteries are also considered advantageous in terms of sustainability due to their higher recyclability, that whereby used NCM batteries can be reprocessed into black mass or black powder for further processing into nickel sulfate. This represents one of the key advantages of nickel-based batteries, which is expected to support a more environmentally friendly (green) production process in the future, considering that within the next 20 (twenty) to 30 (thirty) years, nickel demand for batteries is projected to be met through the recycling of end-of-life nickel-based batteries, without the need for new mining activities.
p. 3 · Read in context →
HPAL’s key consumable after the Strait of Hormuz closure: 3–4 months of stock and a deliberately diversified supplier base.
Zetta Hannany (IDNFinancials); PT Trimegah Bangun Persada management: With regard to the impact of the sulfur supply disruption, the Company convey that since the outbreak of the conflict and the closure of the Strait of Hormuz in 2026, sulfur distribution has experienced minor disruptions. Nevertheless, since the end of 2025, the Company had anticipated the upward trend in sulfur prices by ensuring that sulfur supply and stock at its sites were sufficient to meet production requirements for a minimum period of 3 (three) to 4 (four) months. Furthermore, the increase in sulfur prices subsequently occurred gradually. To date, the Company has not experienced any difficulty in restocking sulfur, given its diversified supplier base, which is not dependent on a single country or the Middle East region alone. Through this strategy, the Company's sulfur stock remains secure, with current reserves estimated to be sufficient to meet requirements for approximately the next 4 months.
p. 4 · Read in context →
Mining carries the higher percentage margin; processing still carries the larger absolute contribution. Both, precisely.
Zetta Hannany (IDNFinancials); PT Trimegah Bangun Persada management: Does this indicate that raw nickel ore sales have become more profitable compared to downstream processing/smelting activities? […] Furthermore, that in percentage terms, the margin of the nickel mining segment is indeed higher than that of the nickel processing segment, given the relatively lower production costs in the mining segment. However, in nominal terms (in both US Dollar and Rupiah), the contribution of the nickel mining segment remains smaller than that of the nickel processing segment, as despite the large sales volume of nickel ore, the selling price per ton of nickel ore is significantly lower than the selling price of nickel processing products.
p. 4 · Read in context →
Why an IDR reporter is economically dollarised: exports in USD, and domestic ore priced off LME then converted.
Nurul21 (individual investor); PT Trimegah Bangun Persada management: What is the impact of the strengthening USD on the Company’s operations? […] With regard to the impact of the strengthening of the United States Dollar (USD) against the Rupiah, the Company convey that this condition does not have a negative impact on the Company. This is because the Company's revenue from the nickel processing segment is derived entirely from export activities, with sales proceeds conducted in USD. Meanwhile, with respect to the nickel mining segment, although sales payments are received in Rupiah, the selling price of nickel ore is essentially benchmarked to the US Dollar, given that the mineral reference price follows the London Metal Exchange (LME) price, which is subsequently converted into Rupiah.
p. 5 · Read in context →
Annual Public Expose 2025 — Q&A Minutes — Public Expose 2025
The clearest single account of the resource base and the low-cost-producer strategy: six IUPs on Obi, backward integration into quicklime, and the KPS RKEF build-out schedule. · Open the full transcript →
Guidance philosophy: no revenue or profit number, only the volume drivers — mature RKEF flat, new assets ramping.
Sabrina Rhamadanty (Kontan); PT Trimegah Bangun Persada management: What are the Company’s revenue and profit targets for this year, considering the global decline in nickel prices? Is there an increase compared to last year? […] In general, the revenue and profit will be contributed by nickel demand and supply globally. The management is striving to remain focus on efficiency programs and completion on the ongoing projects and expect these initiatives will provide enhanced contributions, particularly driven by improved operational performance in the nickel ore mining sector. The Company will increase the production through its subsidiary i.e PT GTS that has commenced operations in 2025. On the operation of nickel processing of PT Megah Surya Pertiwi (“PT MSP”) and PT Halmahera Jaya Feronikel (“PT HJF”) are expected to remain stable, as both facilities have reached full production capacity. […] Additional contributions are anticipated from the Company’s associated entities i.e PTHalmahera Persada Lygend (“PT HPL”), PT Obi Nickel Cobalt (“PT ONC”) and PTKarunia Permai Sentosa (“PT KPS”) which also impacted by nickel prices. However, in 2025, PT KPS and PT ONC are expected to increase, as PT ONC has reached full capacity and PT KPS has commenced production in 2025.
p. 3 · Read in context →
How the cost curve is defended when volume cannot grow: bring the HPAL reagent in-house rather than buy it.
Jeffrey Angkasa (Tuntun Sekuritas); PT Trimegah Bangun Persada management: What are the Company’s long-term strategies to maintain its position as a lowcost nickel producer, considering that many smelters face challenges in expanding production beyond existing capacity? […] To date, The Company is undertaking several cost-efficiency initiatives to remain competitive in production costs, including starting the construction of PT Citra Kemakmuran Mitra (“PT CKM”). PT CKM will process limestone into quicklime. During this time, we buy the quicklime from the external party at a higher cost. […] With the construction of a quicklime facility, the production or operational costs are expected to be more efficient, especially in nickel ore refining process using HPAL technology.
p. 4 · Read in context →
Management’s working price assumption — roughly USD 15,000/t Ni, taken as near the floor.
Zeta (IDN Financials); PT Trimegah Bangun Persada management: What is the Company’s projection on nickel prices for the remainder of the year? Is there any specific impact on the domestic nickel industry? […] The Company views the current nickel price as relatively stable. Based on LME data, the price hovers around USD 15,000/ton Ni and has occasionally lower below that level. Under current conditions, as a low-cost producer and efficiency initiatives implemented, the Company remains quite optimistic about its operational performance this year.
p. 5 · Read in context →
The growth pipeline dated and sized: KPS phases 2 and 3, to 185,000 t of nickel in ferronickel.
Zeta (IDN Financials); PT Trimegah Bangun Persada management: When will the construction of the remaining 8 (eight) RKEF lines at PT KPS be completed? What will the total production capacity be once completed? […] The 8 (eight) production lines at PT KPS are divided between Phase 2 and Phase 3, with four (4) lines each. Phase 2 is expected to proceed on schedule, with will be commencing in Q3 or Q4. The next phase is expected to begin in early 2026. Upon completion, PT KPS is projected to reach an installed capacity of 185,000 tons of nickel in FeNi.
p. 5 · Read in context →
Annual Public Expose 2024 — Q&A Minutes — Public Expose 2024
The call where the thesis was tested — BASF had just walked away from the Obi project and nickel was in surplus; it also contains the only public unit economics for the HPL HPAL plant. · Open the full transcript →
The Obi value-chain logic first laid out: tailings turned into product, limestone turned into HPAL reagent.
Godang Sitompul (Ruang Energi); PT Trimegah Bangun Persada management: In general, the purpose of PT BBS’s establishment is to reduce the tailings from HPAL. Currently, PT BBS is still under feasibility study, but roughly, contribution for reducing tailings from HPAL annually can reduce 1.5 tons of tailings. In addition, we hope the recycling process for the tailings from HPAL will be able to push the profitability of the Company, whereas the tailings with no value can be recycled into products that have added value. The efficiency from PT CKM through the processing of limestone to quicklime (the main raw material in the HPAL process) is still under feasibility study; therefore, we don’t have the number yet. The main point is that PT CKM will optimize the value chain in Obi Island, hence the operations are more efficient and can reduce production costs.
p. 3 · Read in context →
The IRMA timetable as originally given; set against the 2026 answer, it has slipped by well over a year.
Godang Sitompul (Ruang Energi); PT Trimegah Bangun Persada management: The Company’s target for ESG is carry out the certification for NCKL, whereas the internationally recognized certification body, namely IRMA. The Company expect that this certification will be completed soon and we will be […] certified no later than approximately in early 2025. If the certification is completed, we are the second company in Indonesia to be certified by IRMA after Vale.
p. 3 · Read in context →
The only public unit economics for HPL: 55,000 t/yr nameplate, US$1.2bn capex, ~30% MHP cash margin.
Ghaffur (Investor Daily); PT Trimegah Bangun Persada management: The Company is not in a position to answer the question of why BASF cancelled the project. We know that they have published a statement that can be directly checked by the public. We want to emphasize that the main point of sustainability for a project is the initial investment. We may say that project HPL, with nameplate capacity of 55,000 tons of nickel containedper year in MHP, has a total investment of US$1.2 billion. The second thing is that the higher cash margin and we may say that our cash margin of MHP is around 30%.
p. 4 · Read in context →
The surplus answered on demand grounds — stainless, not EVs, is the swing factor, and cost position is the defence.
Ghaffur (Investor Daily); PT Trimegah Bangun Persada management: Currently, nickel is oversupplied due to the increase of the nickel production in Indonesia. After we met several analysts and securities outside the country, they said that the oversupply is not as bad as predicted. […] By industry, the use of nickel from Indonesia is dominated by stainless steel, and growth for stainless steel has increased by 8%. It shows the oversupply has the potential to decrease. On the other hand, China government has taken an initiative to boost the economy for their country, including increasing the incentive for property, which will be able to push the demand for stainless steel and reflect the demand for nickel. Electric Vehicles (EV) batteries are currently growing, although the growth percentage is not as high as predicted by the market. We can say that every year’s growth is still double digits. We believe that nickel prospect in the future are still good. However, the most important things at this time is become a low cost producer. In the event of low nickel price, Indonesia nickel producers still can be make a profit.
p. 4 · Read in context →
Capital allocation for the rights issue: more capacity, more reserves, and larger stakes in the smelters it already runs.
Ghaffur (Investor Daily); PT Trimegah Bangun Persada management: Use of proceed of Right Issue will be use to increase the capacity production and nickel reserves of the Company. Furthermore, the Company also plans to increase shares ownership in the smelter and refinery facilities.
p. 5 · Read in context →
PT Trimegah Bangun Persada Tbk's annual reports contain management's most considered account of the business. These are the sections, passages and visual pages worth opening in the originals preserved in Sources.
PT Trimegah Bangun Persada Tbk (Harita Nickel) — 2025 Annual Report — FY2025
Latest edition: first full year with the KPS smelter and ONC refinery running, and the year associate earnings reached a third of profit. · Open the full document →
Laporan Direksi / The Board of Directors Report — p. 38 · Read the full section →
Management's own account of the year: volumes by ore type and product, and why FeNi and MHP margins behave differently.
2025 volumes: 30.59m wmt of ore, 188,581t Ni in FeNi, and installed capacity by route.
From a mining perspective, the Company recorded total nickel ore sales volume of 30.59 million wmt, representing a 28.8% increase compared to the previous year. This growth was largely driven by a significant sales of saprolite ore, which reached 12.09 million wmt, in line with higher demand from RKEF smelters, particularly following the commencement of operations at PT KPS. Meanwhile, limonite ore sales reached 18.50 million wmt, supported by feedstock requirements for HPAL facilities, including the full-year contribution from PT ONC. […] In the RKEF segment, through PT MSP, PT HJF, and PT KPS, the Company achieved an installed capacity of approximately 240,000 tons of nickel metal per year, with additional significant capacity contribution from PT KPS, which has operated 8 (eight) production lines. Correspondingly, FeNi sales volume in 2025 reached 188,581 tons of nickel content in FeNi, compared to 126,344 tons of nickel content in FeNi from previous year. […] On the other hand, in the HPAL segment, the Company, through PT HPL and PT ONC, recorded an installed capacity of approximately 120,000 tons of nickel-cobalt metal per year. […] From a profitability perspective, these two segments exhibit distinct yet complementary margin characteristics. The RKEF (FeNi) segment, which is based on saprolite ore, generally has a more stable and relatively lower cost structure, serving as a margin stabilizer under pressured pricing conditions.
p. 42 · Read in context →
Why the two processing routes are run as a pair: FeNi for stability, MHP for cobalt credits and mix.
Meanwhile, the HPAL (MHP) segment provides exposure to higher value-added products, particularly within the EV battery supply chain. Although the HPAL cost structure is relatively more complex and sensitive to input price fluctuations such as sulfur, the segment benefits from cobalt by-product credits, which, under certain price conditions, help offset cost pressures and sustain competitive margins. […] Therefore, the Company’s portfolio mix of FeNi and MHP provides a balance between short-term cash flow stability and long-term margin expansion potential. In a volatile market environment, this strategy enables the Company to maintain profitability while remaining wellpositioned in structurally growing segments of the global nickel industry.
p. 43 · Read in context →
Struktur Korporasi / Corporate Structure — p. 96 · Read the full section →
Shows what the income statement does not: Harita holds 81.3%, Glencore 7.2%, and the HPAL plants are minority stakes.
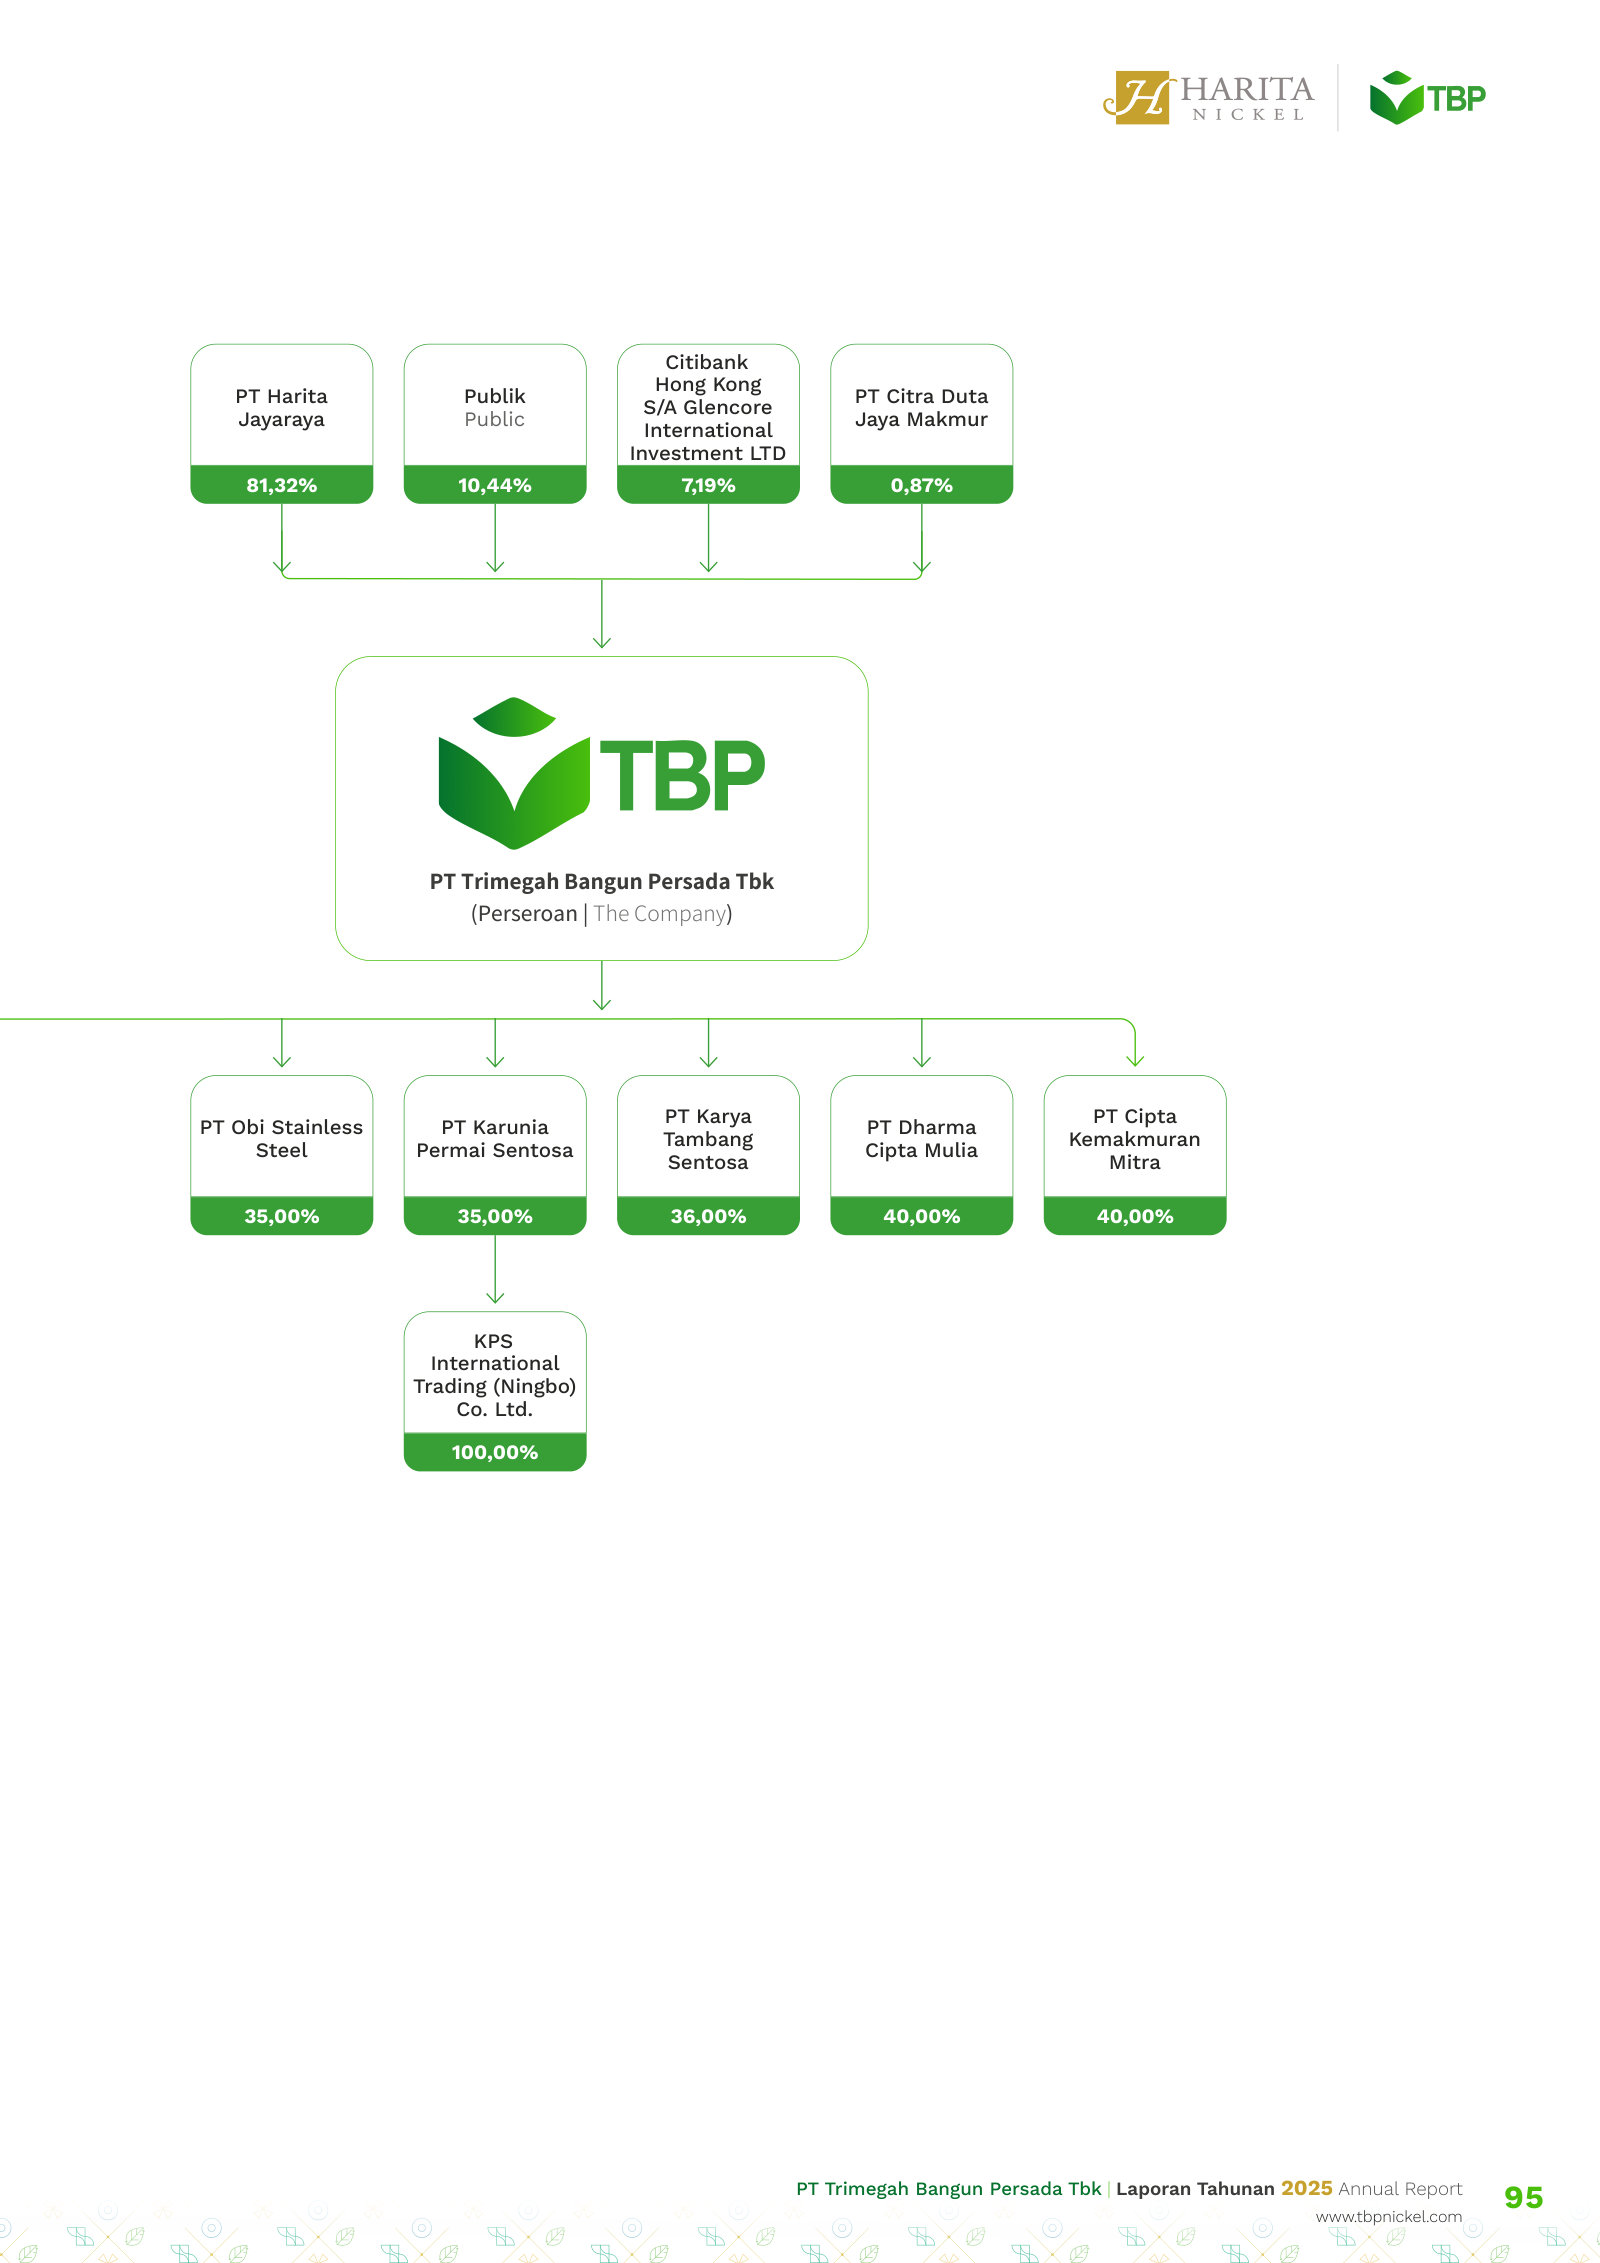
Tinjauan Kondisi Eksternal / View on External Conditions — p. 104 · Read the full section →
The price backdrop the whole year is judged against — a third year of surplus and a 19% lower average LME price.
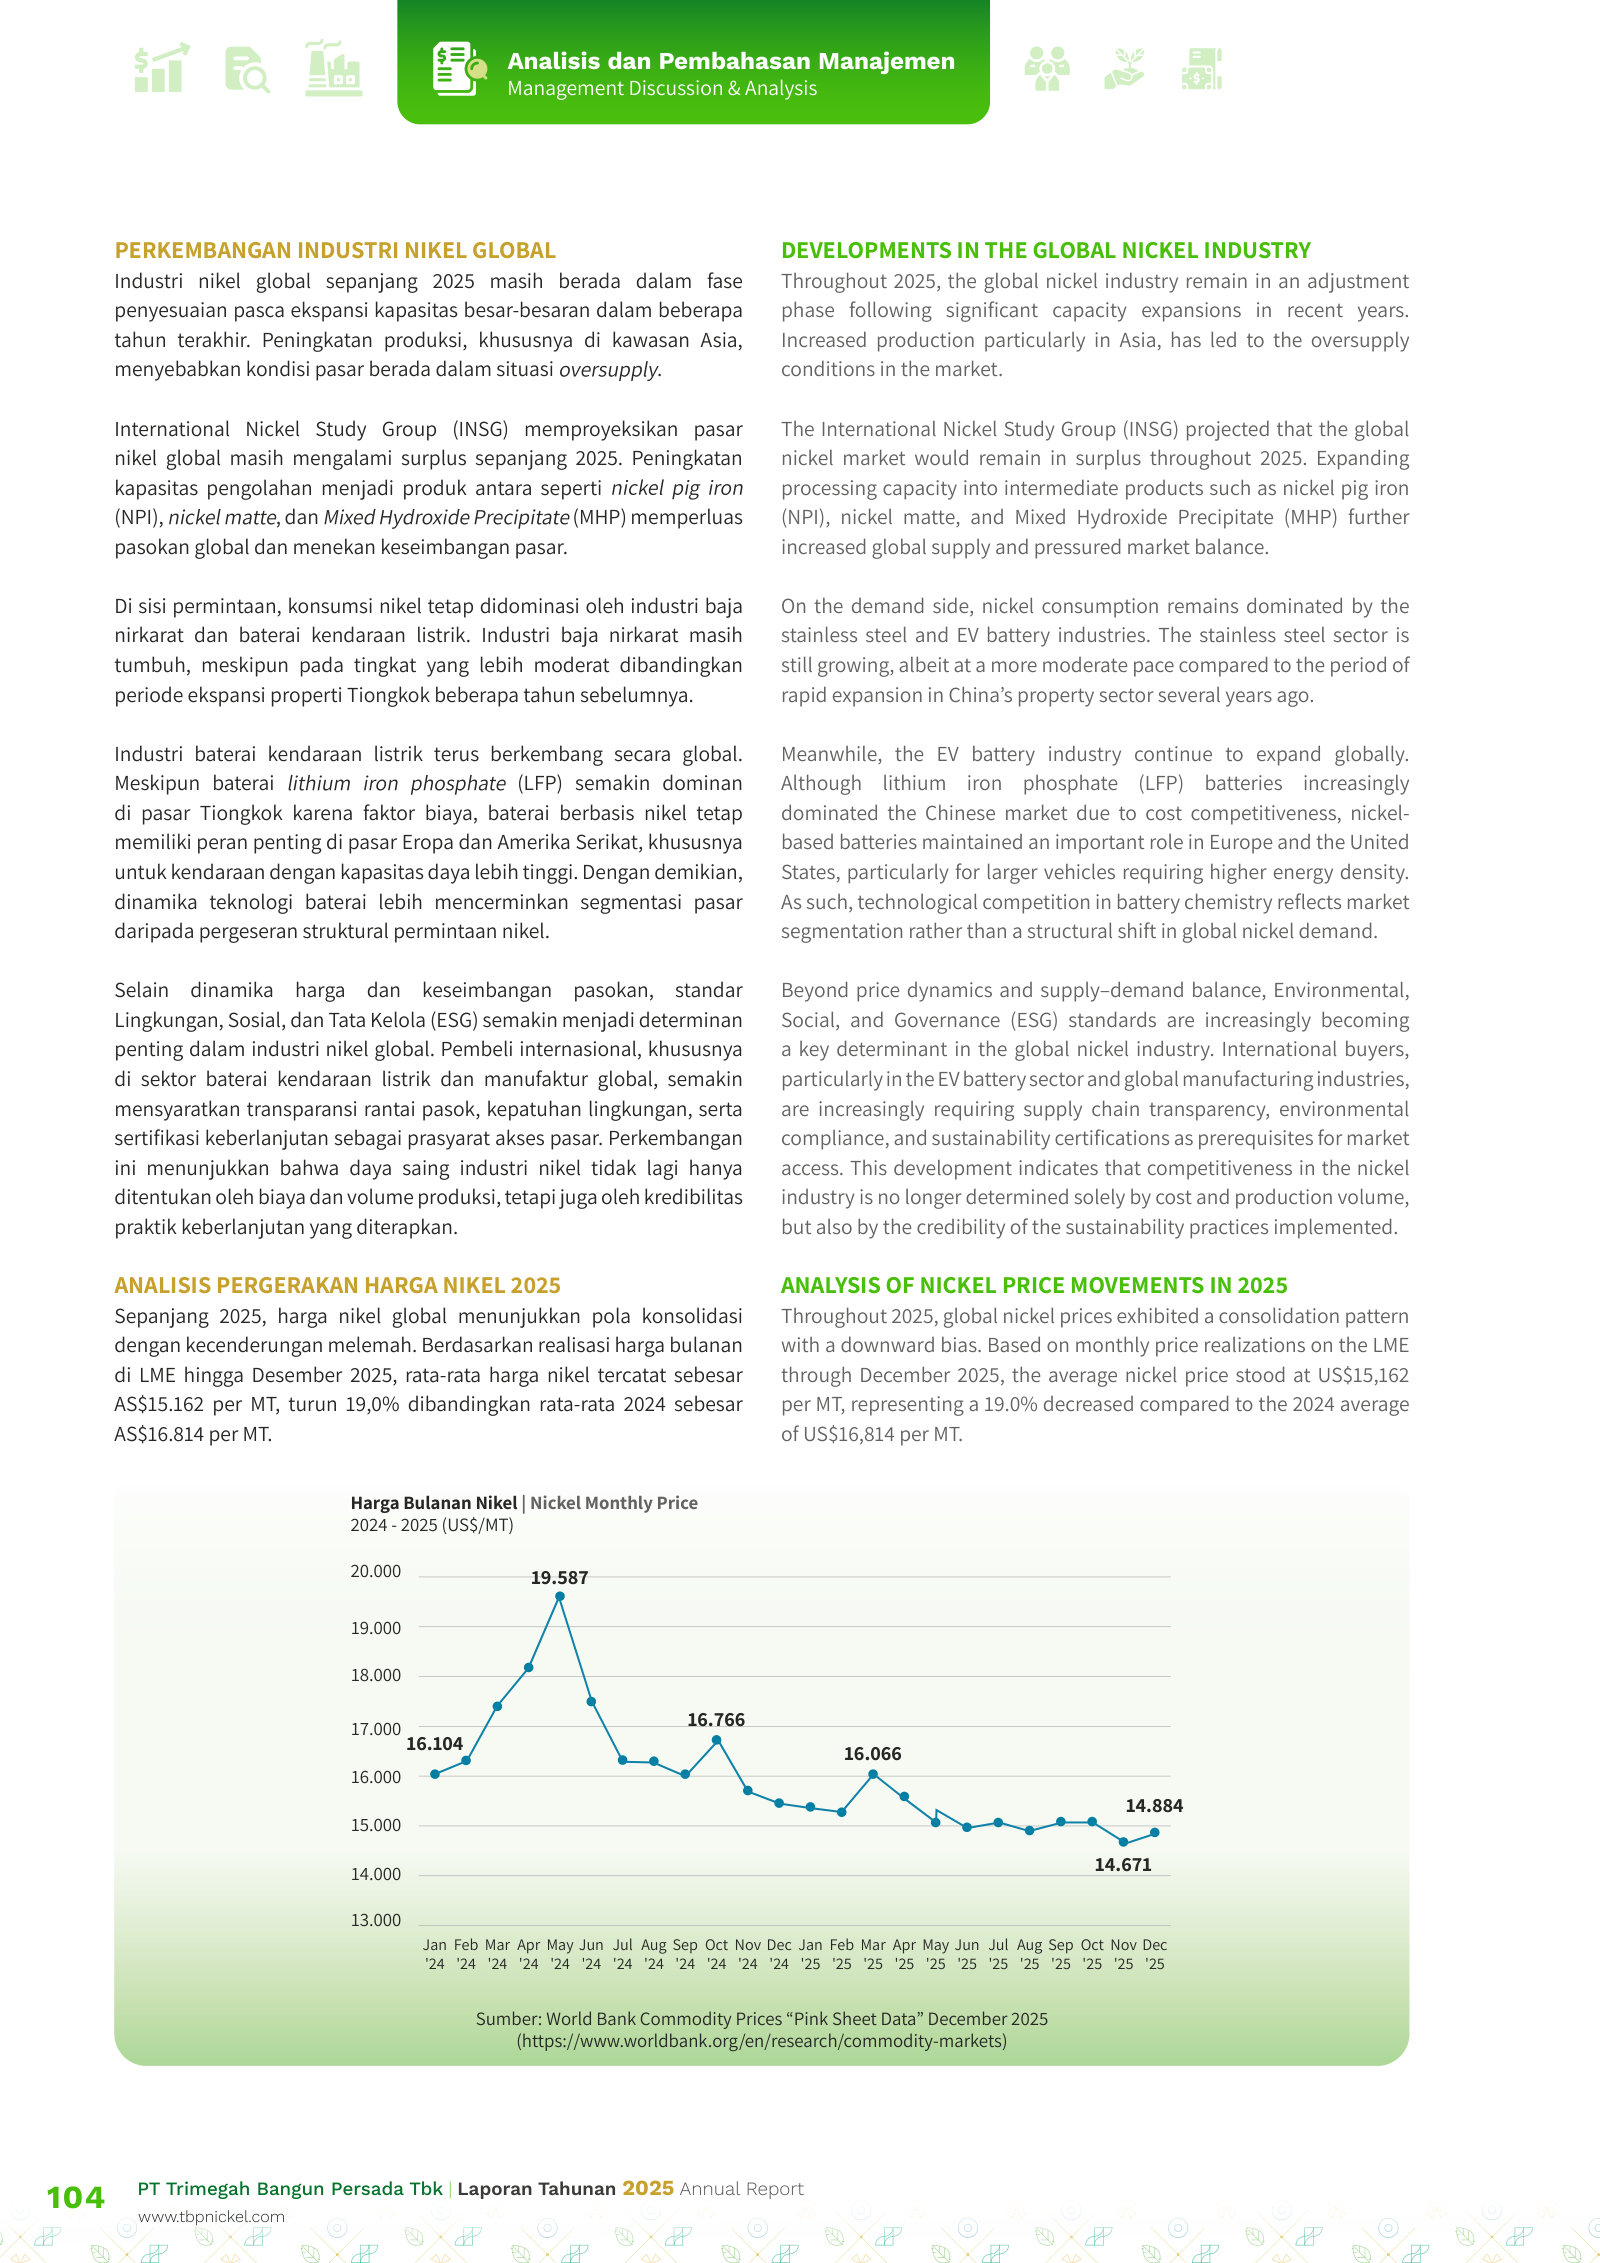
Tinjauan Kinerja Operasional / Operational Performance Review — p. 108 · Read the full section →
The clearest statement of how the business actually works: two ore types, two technologies, one island.
Limonite and saprolite, RKEF and HPAL, and why co-location on Obi Island matters.
The Company operates an integrated nickel business model spanning mining through processing activities. Its primary products are derived from laterite nickel ore, which consists of two main types: limonite and saprolite. Limonite ore typically contains approximately 1.1%–1.2% nickel content and is located closer to the surface. Beneath this layer lies saprolite ore, which generally contains higher nickel grades. […] All mined ore, both limonite and saprolite, were processed at downstream facilities owned by the Company’s Subsidiaries and Associated Entities located on Obi Island. The integration of mining sites and processing facilities within a single industrial cluster provides operational advantages, particularly in terms of logistics efficiency and supply reliability. […] Through its Subsidiaries, PT MSP, PT HJF, and Associated Entity, PT KPS, the Company operates smelter utilizing Rotary Kiln Electric Furnace (RKEF) technology to process saprolite ore into ferronickel (FeNi), which is subsequently used as a key raw material in stainless steel production.
p. 108 · Read in context →
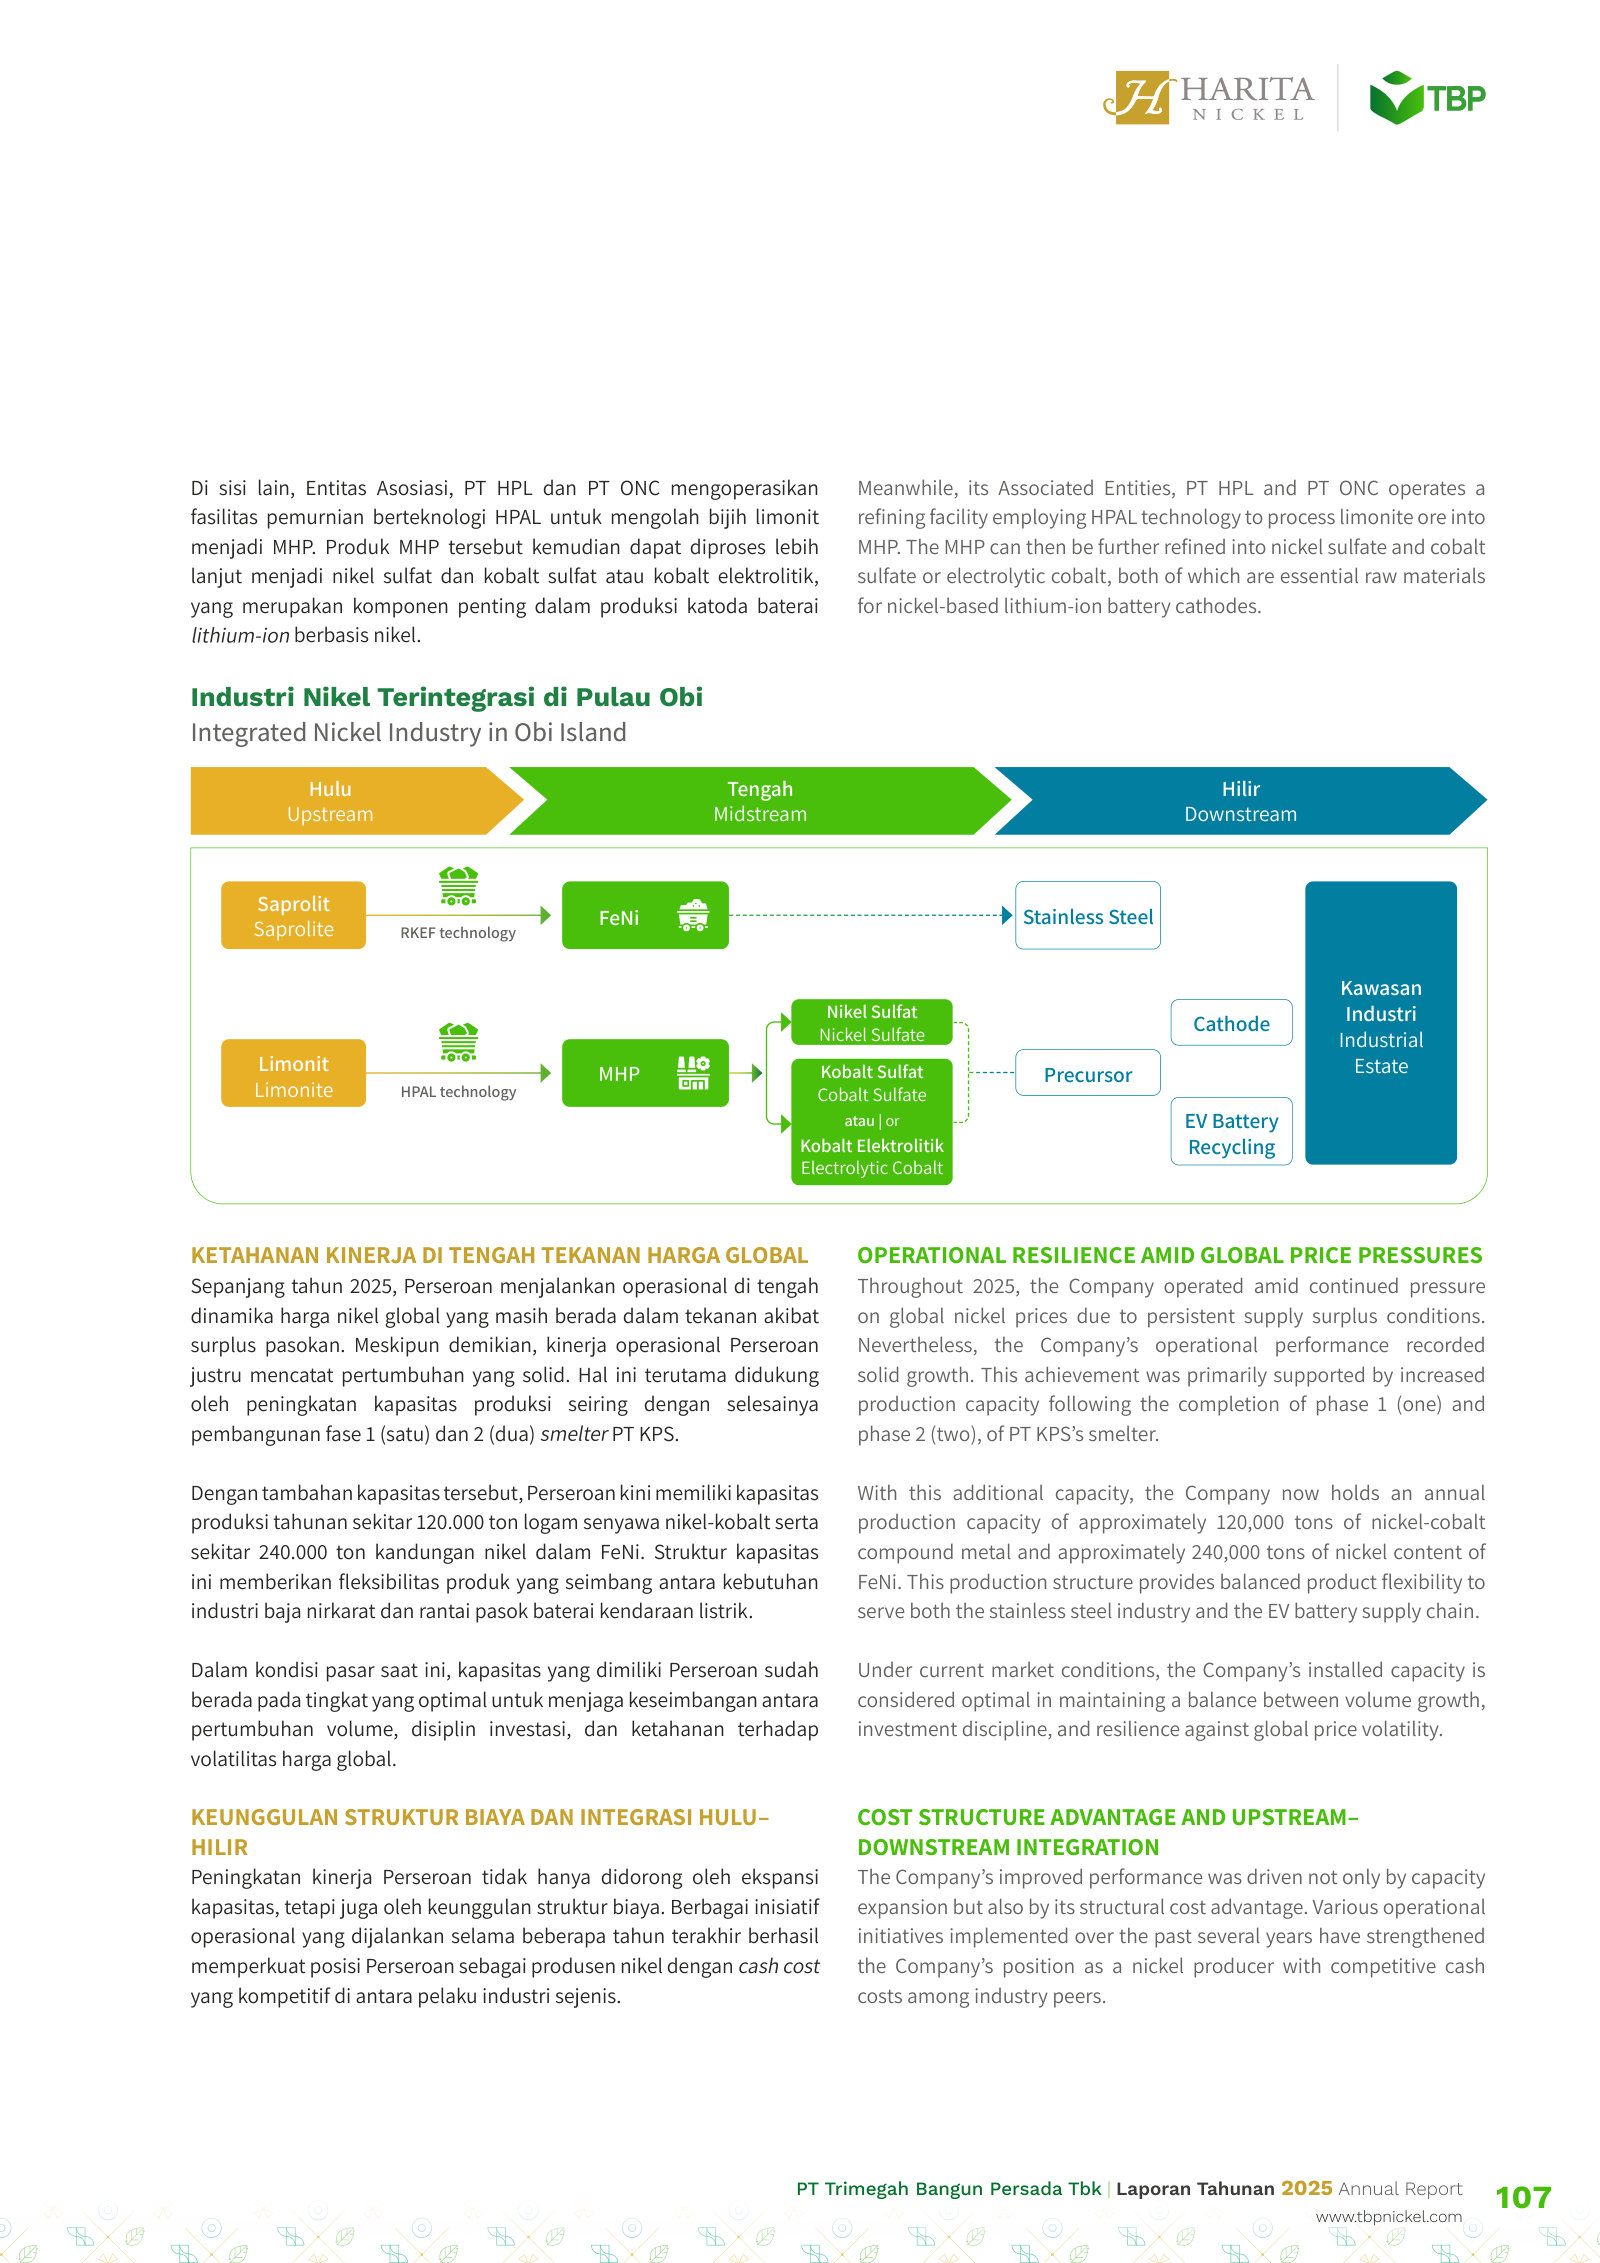
Tinjauan Keuangan / Financial Overview — p. 118 · Read the full section →
Where the growth came from: mining segment revenue up 88.8% while processing revenue fell, and associate profit doubled.
FY2025 revenue split: nickel mining IDR7,178bn (+88.8%), nickel processing IDR22,455bn (-3.1%).
The Company recorded revenue from contracts with customers of IDR29,633 billion in 2025, representing a 9.9% increase compared to IDR26,965 billion in 2024.
This revenue was contributed by the nickel mining segment amounting to IDR7,178 billion, an increase of 88.8% compared to IDR3,801 billion, meanwhile the nickel processing segment amounting to IDR22,455 billion, a decrease of 3.1% compared to IDR23,164 billion in 2024.
p. 121 · Read in context →
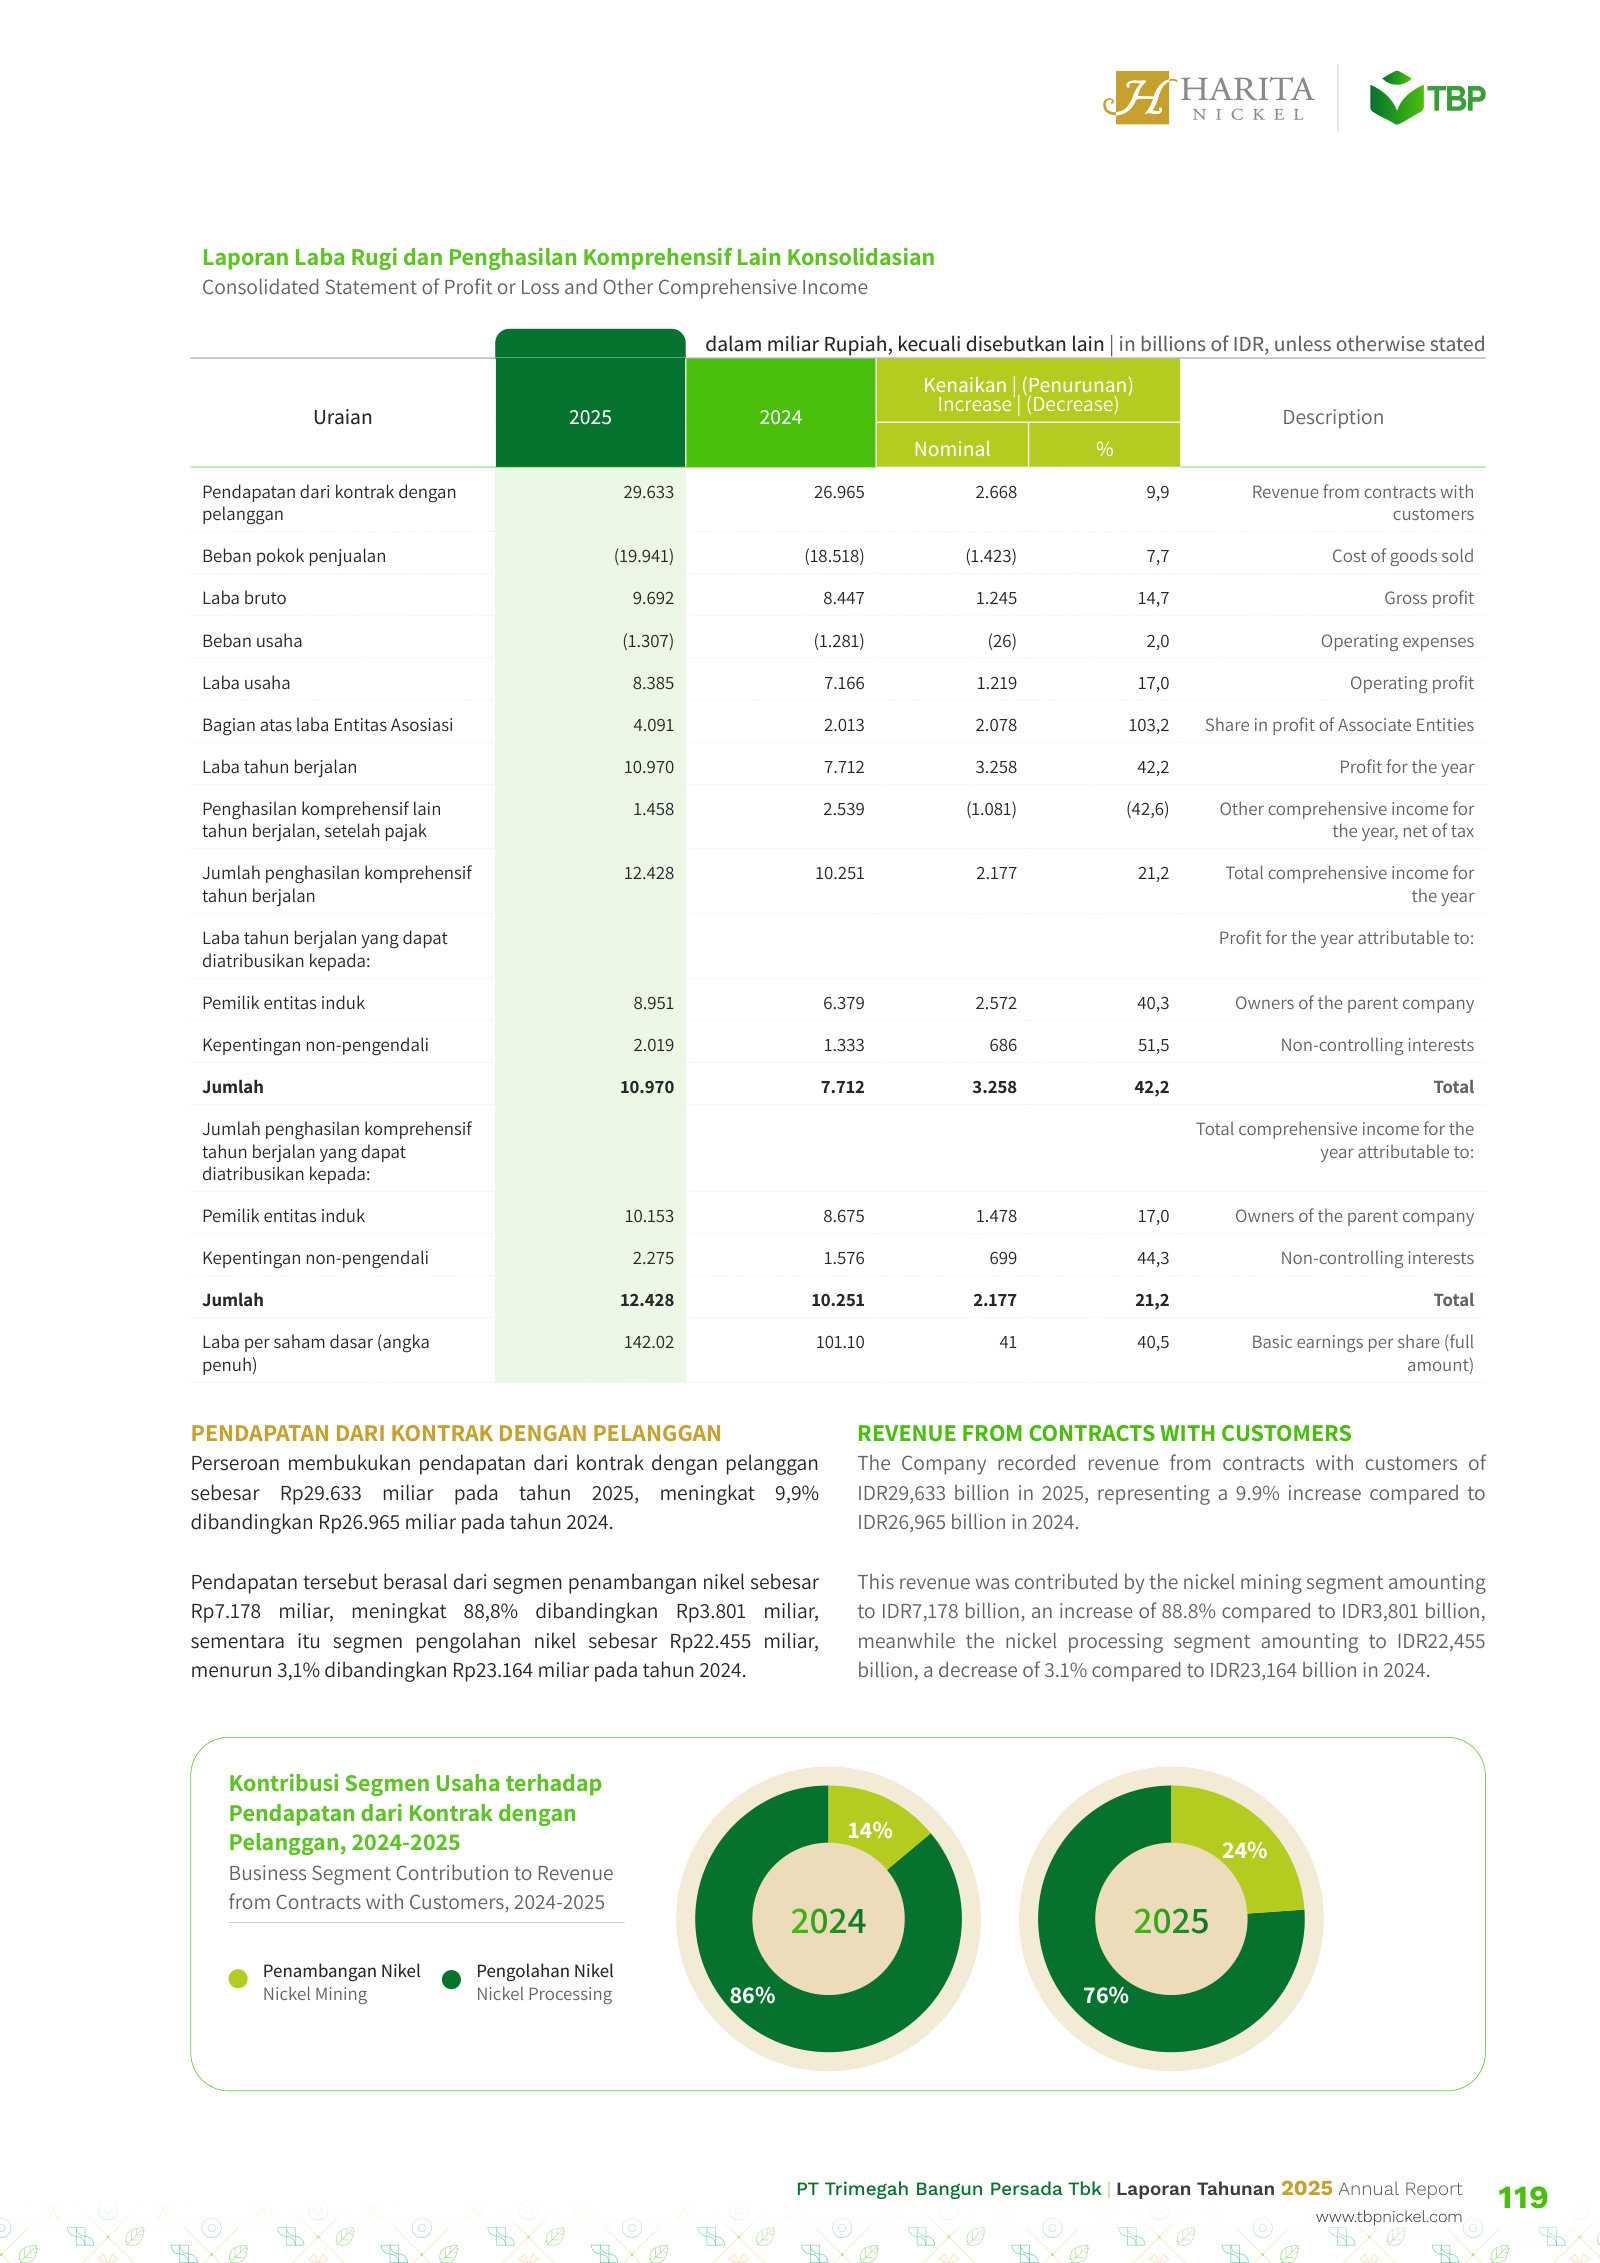
Manajemen Risiko / Risk Management — p. 208 · Read the full section →
The only risk disclosure in the report; the production-disruption and community rows are the ones tied to a single-island operation.
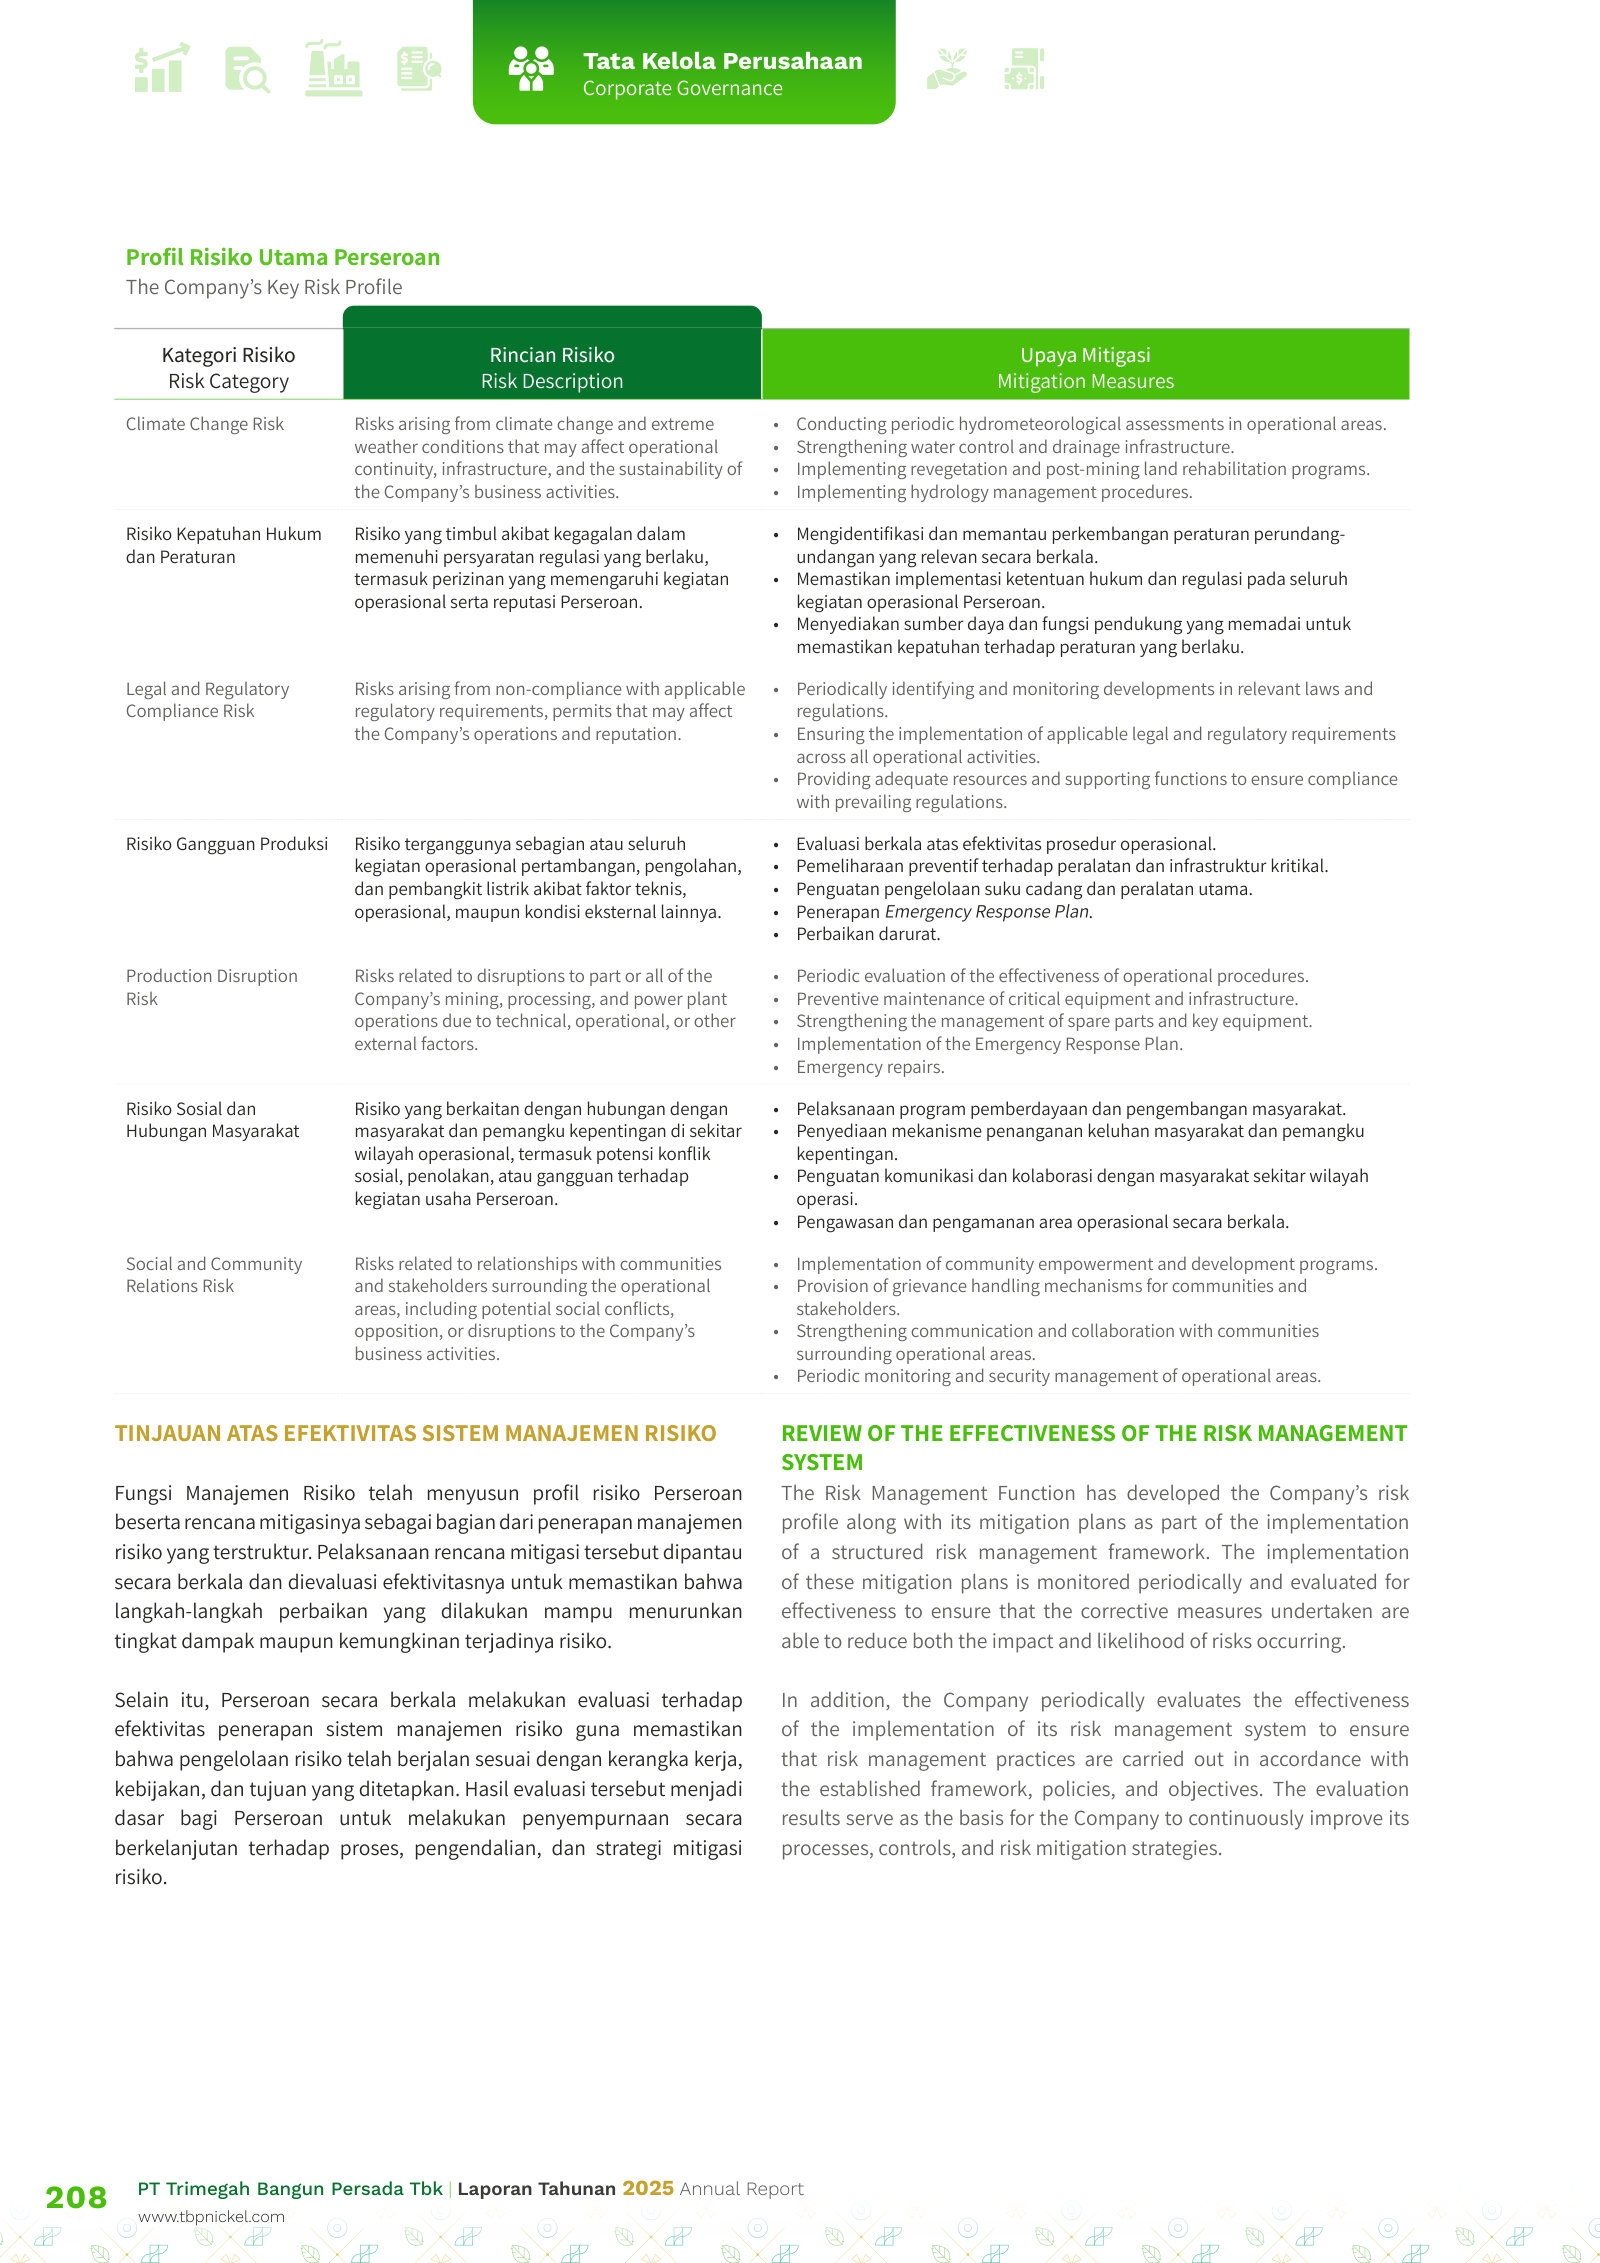
Catatan 10. Investasi pada Entitas Asosiasi / Note 10. Investment in Associates — p. 343 · Read the full section →
The structural fact of NCKL: the HPAL refineries are 45.1%/40% associates, equity-accounted and absent from revenue.
HPL, ONC and KPS are private, unquoted and carried on the equity method.
The material associates of the Group are HPL, ONC and KPS. All associates are private companies in which there are no quoted market share prices available. The Group’s interests in all associated are accounted for using the equity method in the consolidated financial statements.
p. 343 · Read in context →
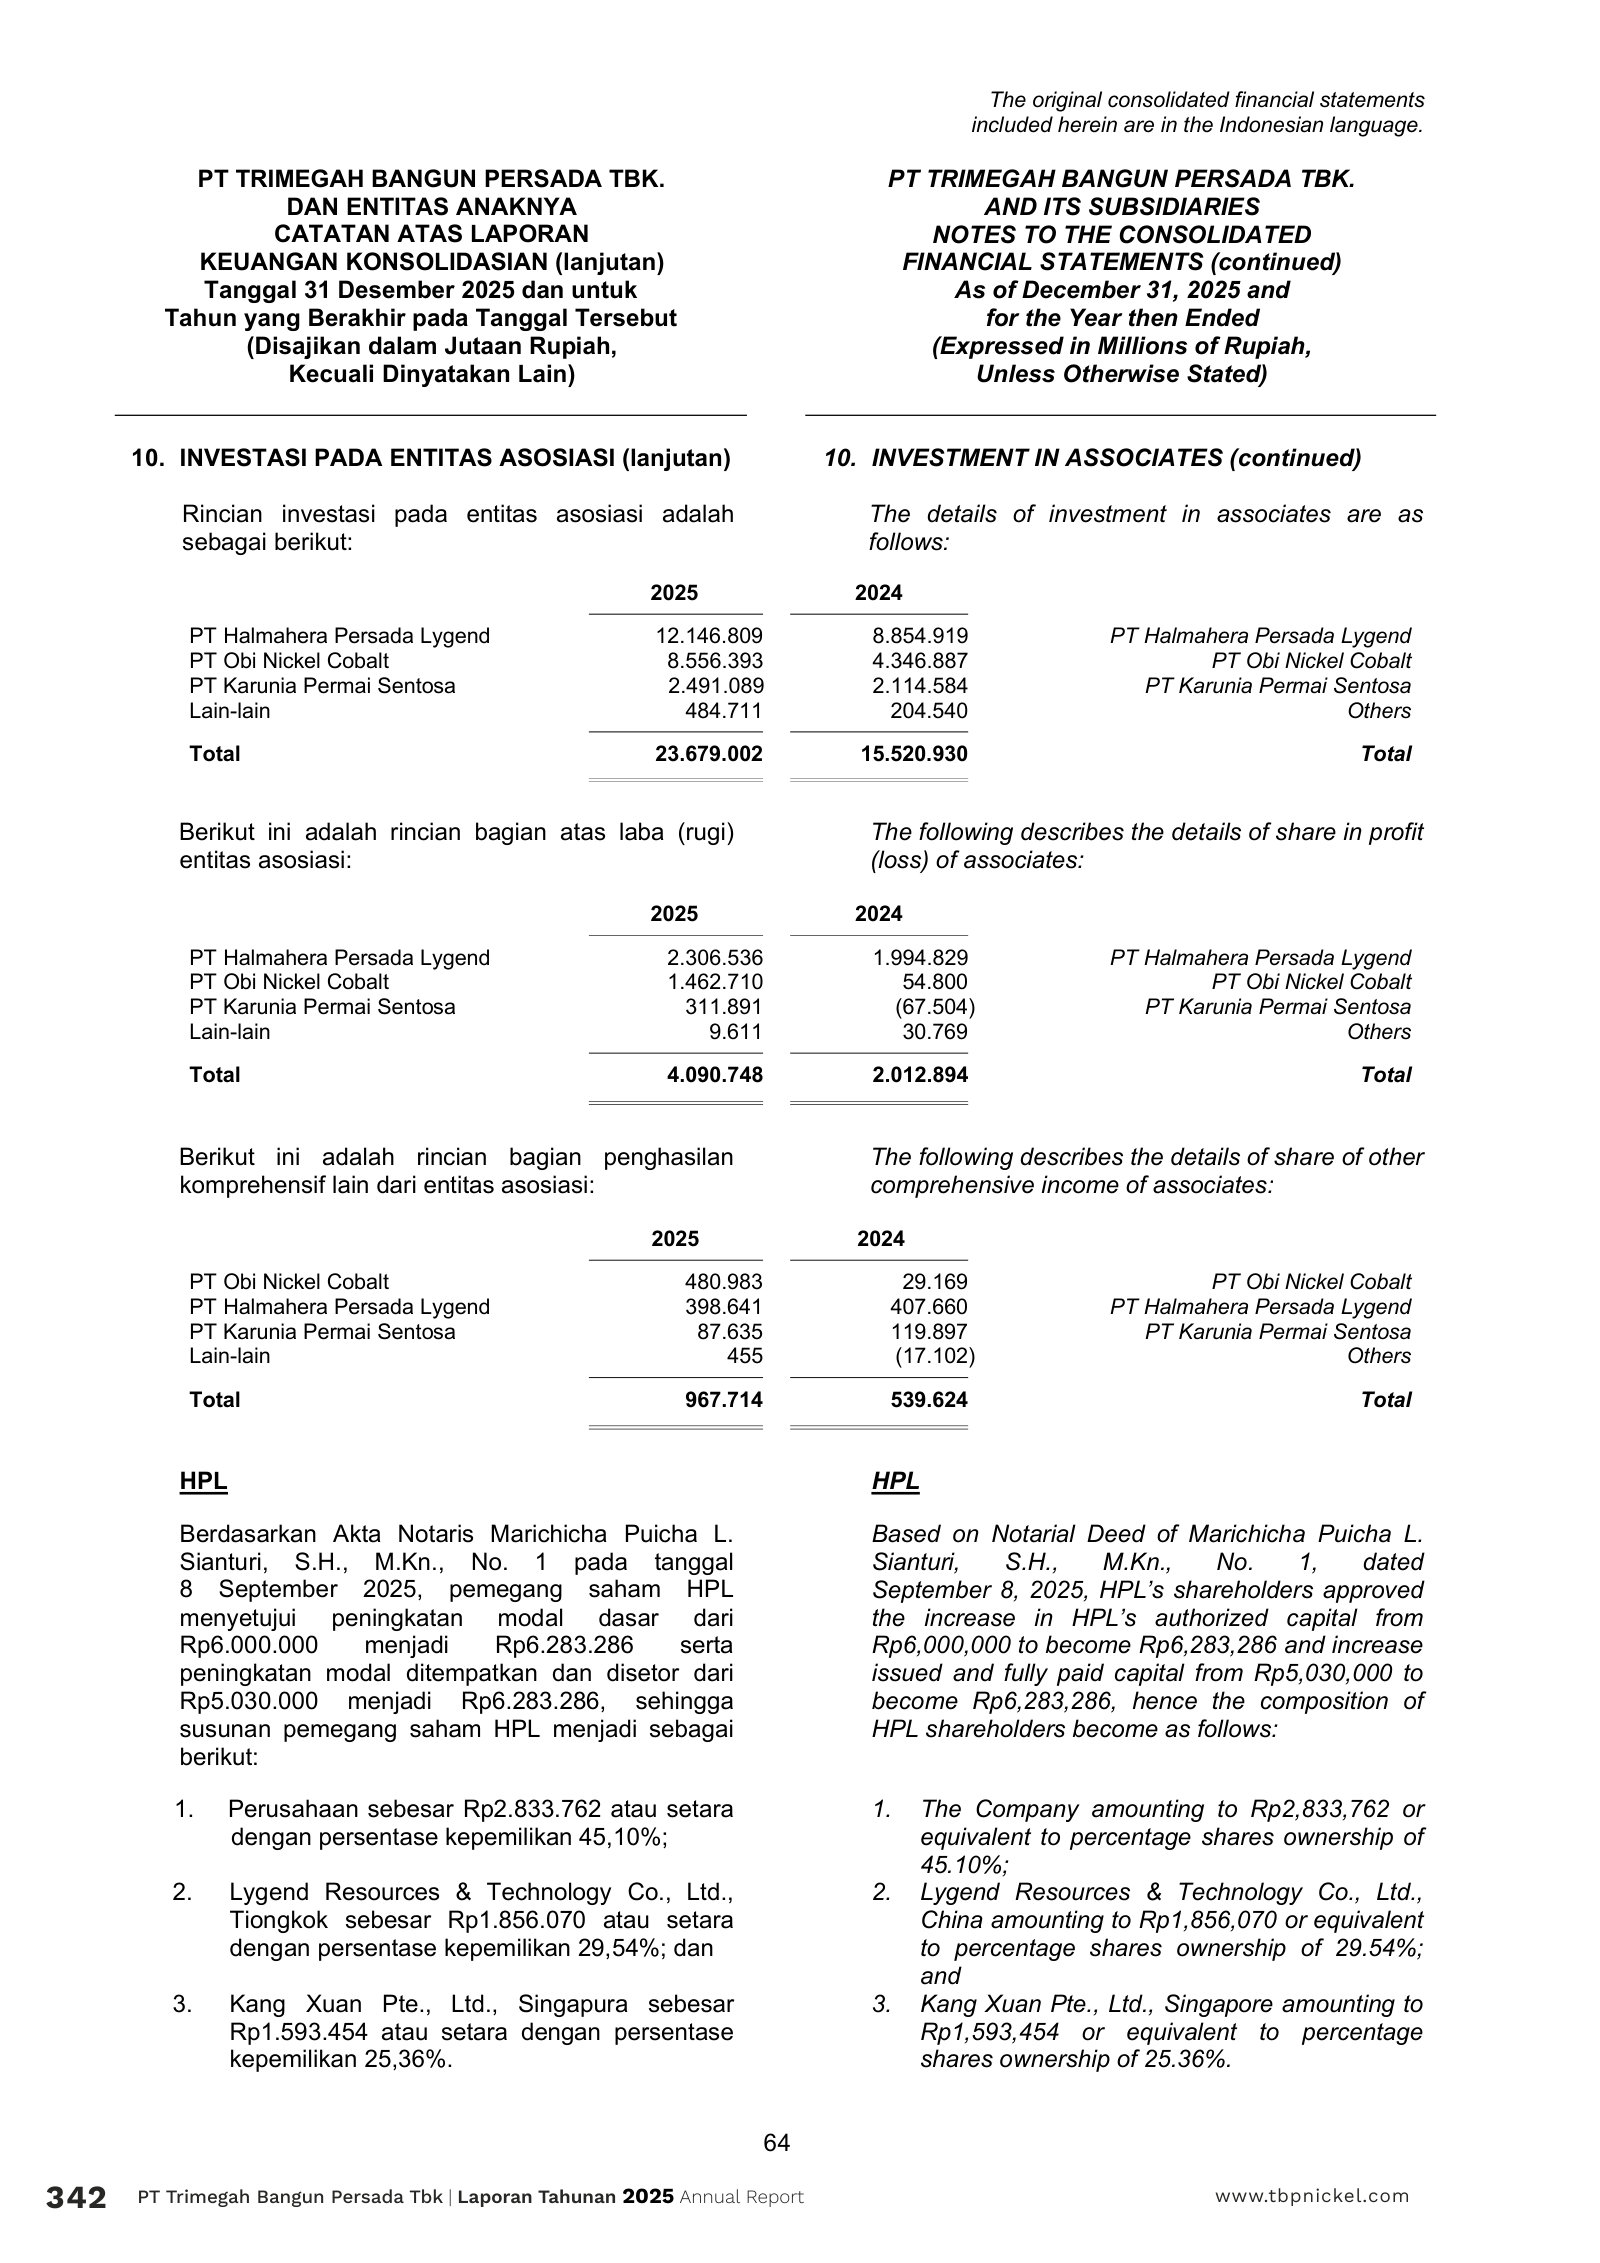
Catatan 37. Informasi Segmen / Note 37. Segment Information — p. 395 · Read the full section →
Defines the two reportable segments and shows that associate profit and the IDR23.7tn investment sit outside both.
Two reportable segments; financing and tax are managed group-wide and not allocated.
For management purposes, the Group is organized into business units based on their products and services and has two reportable operating segments as follows: […] Management monitors the operating results of its business units separately for the purpose of making decisions about resource allocation and performance assessment. Segment performance is evaluated based on operating profit or loss and is measured consistently with operating profit or loss in the consolidated financial statements. However, the Group financing (including finance costs and finance income) and income taxes are managed on a group basis and are not allocated to operating segments.
p. 395 · Read in context →
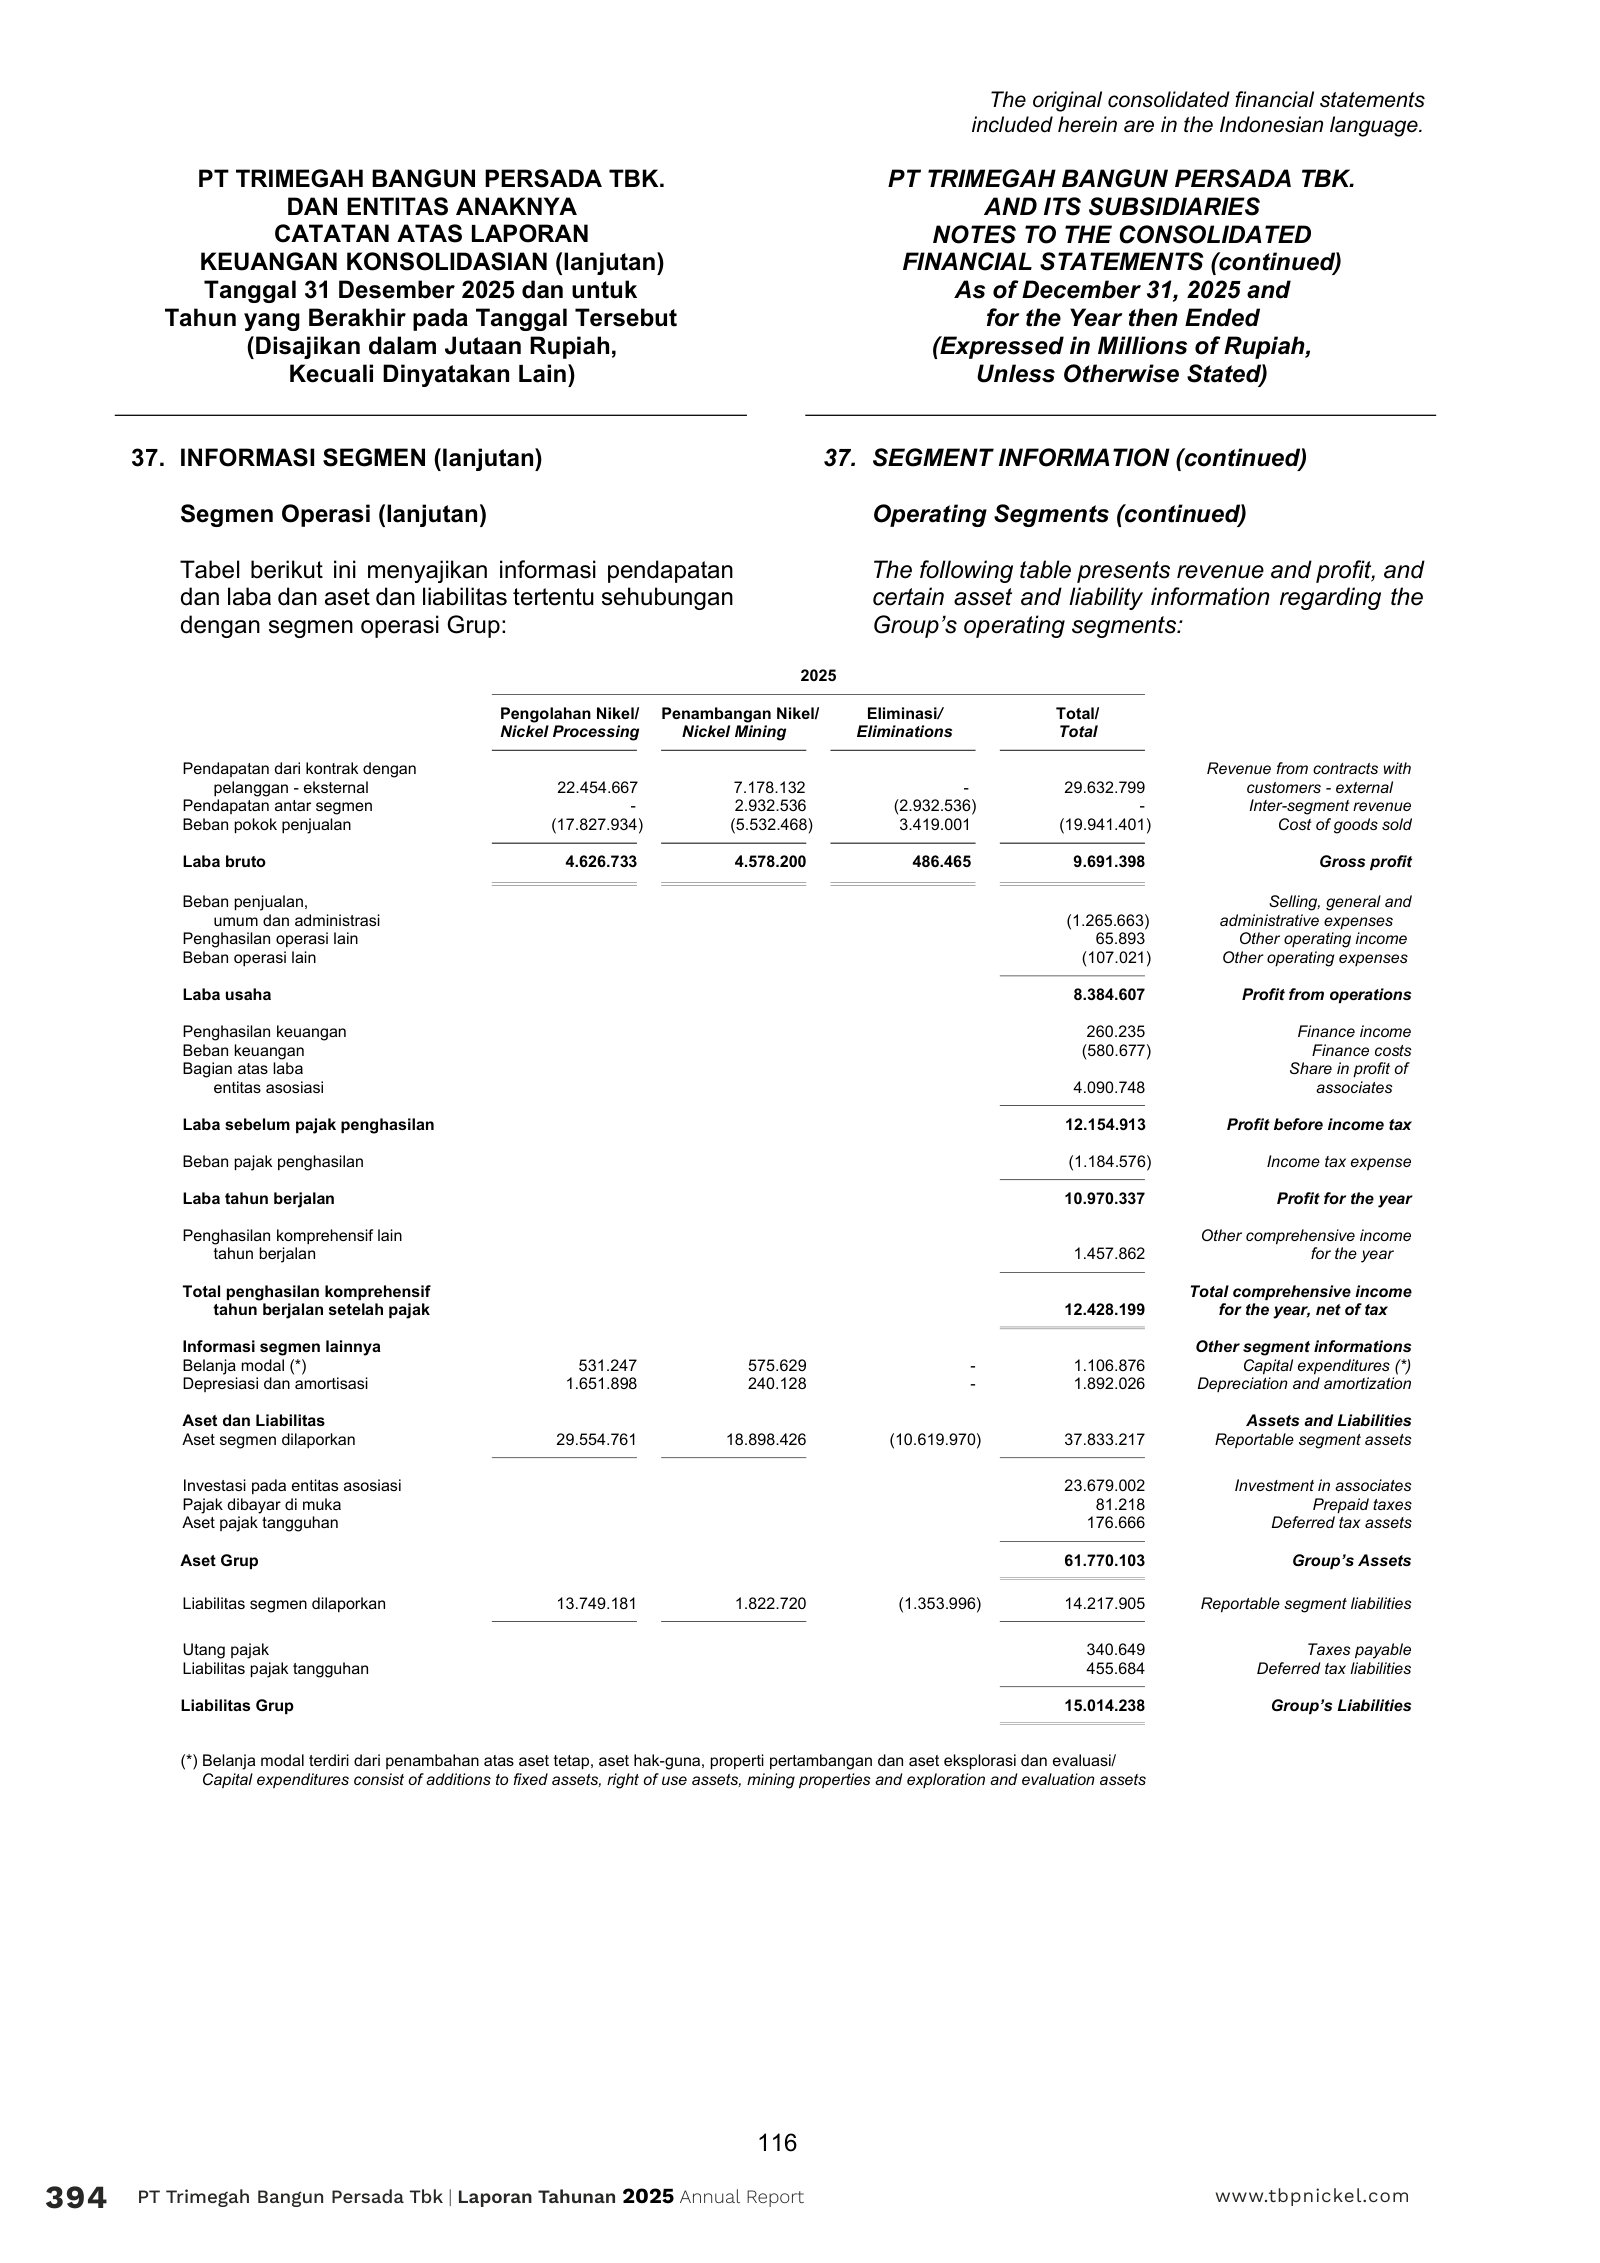
PT Trimegah Bangun Persada Tbk (Harita Nickel) — 2023 Annual Report — FY2023
The first post-IPO edition, whose business chapter is written at half today's capacity and before ONC and KPS existed as associates. · Open the full document →
Tinjauan Segmen Usaha / Business Segment Review — p. 101 · Read the full section →
How the company framed itself in 2023 — mining plus an industrial estate, two active pits, 301.9m wmt of reserves and resources.
2023 framing: two segments, two producing concessions, 301.9m wmt versus 310.8m wmt in 2025.
The Company operates 2 (two) main segments, namely nickel ore mining and establishment as well as the operation of an industrial estate on Obi Island, North Maluku Province. […] The Company estimates nickel ore reserves approximately 301.9 million wet metric tons (wmt) from 2 (two) active nickel laterite mining projects originating from the concessions of PT Trimegah Bangun Persada Tbk (“PT TBP”) and PT Gane Permai Sentosa (“PT GPS”), and 2 (two) mining concessions for nickel mining prospectus namely PT Jikodolong Megah Pertiwi (“PT JMP”) and PT Gane Tambang Sentosa (“PT GTS”).
p. 101 · Read in context →
Keunggulan Kompetitif / Competitive Advantages — p. 102 · Read the full section →
The technical explanation of RKEF and HPAL that later editions dropped, with the capacity base that has since roughly doubled.
End-2023 HPAL base: three lines, 55,000t MHP a year — against 120,000t of nickel-cobalt metal in 2025.
The Company is the first to develop and operate a refinery using HPAL technology in Indonesia, boasting the world’s largest capacity for nickel and cobalt production. […] The Company has an HPAL refinery through investment in PT Halmahera Persada Lygend (“PT HPL”) which has 3 (three) production lines with a total capacity of 55,000 tons of MHP per year produced from raw materials of 7.7 million wmt limonite.
p. 104 · Read in context →
More annual reports
PT Trimegah Bangun Persada Tbk (Harita Nickel) — 2024 Annual Report — FY2024 · 446 pages · The year ONC started up and NCKL took its stake to 20%, moving the second HPAL plant onto the equity method. · Open →
PT Trimegah Bangun Persada Tbk (Harita Nickel) — 2022 Annual Report — FY2022 · 410 pages · First annual report, covering the pre-IPO year and the common-control reorganisation that assembled the group. · Open →
Competitors describe PT Trimegah Bangun Persada Tbk's market in their own filings and calls. These verified passages and visual pages show where their strategies meet, using source documents preserved in Sources.
PT Merdeka Battery Materials Tbk (MBMA)
The closest structural analogue to Harita Nickel: the other IDX-listed integrated nickel group running a laterite mine (SCM), RKEF smelters and an HPAL-to-MHP build-out under the same Indonesian permitting regime, backed by domestic sponsors and run head-to-head against NCKL in local broker comparisons. Its annual report is also the only peer document that states a nickel-market view in the same regulatory vocabulary NCKL uses. Only the nickel chain is drawn on here; the AIM I pyrite/copper facility and the IKIP industrial estate are left out.
Two passages from the Nickel Industry Overview of MBMA's 2025 annual report (pp. 106-107). The characterisation is MBMA's; the demand figures are attributed to the International Nickel Study Group and the share figures carry no source. The part that matters for a Harita reader is that a direct competitor is publicly calling 2025 a significant surplus year driven by Indonesian and Chinese supply, with demand growth running behind supply growth - the price environment behind NCKL's realised FeNi and MHP prices in the same year. Treat the share claims as characterisation rather than measurement: page 107 carries both "more than one-third of the global nickel supply" and "around 50% of total global nickel output" within a few paragraphs of each other, and Eramet's country tables further down this tab put Indonesia at roughly 62% of ore production (INSG data) and 52% of finished primary nickel in 2024.
The combination of global economic slowdown, trade pressures, and oversupply caused the nickel industry to weaken, both in terms of prices and growth prospects. In 2025, the global nickel market was dominated by a surge in production, particularly from Indonesia and China, resulting in a significant surplus. Although demand for stainless steel and EV batteries continued to grow, the increase in demand was not proportional to the rise in supply, leading to downward pressure on nickel commodity prices throughout the year. In this regard, nickel continues to be regarded as a strategic metal for industrial and clean energy components, however, the market is facing structural challenges arising from oversupply and shifts in battery technology.
Based on projections from the International Nickel Study Group (INSG) meeting, global primary nickel demand grew by 4.8% in 2024 and is projected to increase further by 5.7% in 2025. Globally, China will continue to be the largest consumer of primary nickel, with its consumption expected to account for 63.5% of total global demand in 2025, followed by Indonesia, which is projected to contribute 12.2%. […] Approximately 42% of the world’s nickel reserves are located in Indonesia with its production accounts for around 50% of total global nickel output. The combination of abundant reserves and high production levels provides Indonesia with significant strategic leverage over the global supply chain, ranging from EV batteries to stainless steel.
p. 106 · Read in context →
MBMA's HPAL pipeline in its own words: PT ESG produced 25,994 tonnes of nickel in MHP in its first year of commercial sales, MNEM runs at 25,000 tpa of nickel in MHP, and a third plant, SLNC, is under construction at 90,000 tpa targeted for 2026. Set against NCKL's own 2025 disclosure of roughly 120,000 tonnes per year of installed HPAL nickel-cobalt capacity and 130,551 metal tonnes of MHP and nickel sulphate sold, MBMA is currently a fraction of Harita's MHP scale but has roughly 145,000 tpa of nameplate either running or in build - ESG at 30 ktpa NiEq and MNEM at 25 ktpa running, SLNC at 90 ktpa under construction (nameplates from p. 70). These are stated nameplate and production figures, not utilisation or cost, and SLNC's 2026 start is a target rather than a commissioned plant.
President Director's Report: In 2025, the MBMA Group reached a key milestone through PT ESG with the commencement of initial MHP sales after receiving its IUI in February 2025. During 2025, PT ESG produced 25,994 tons of nickel in MHP, while the FPP and slurry pipeline to IMIP had commenced operation in Q4 2025. This achievement reflects the operational readiness of the HPAL facility and strengthens MBMA Group’s position within the rapidly growing global battery materials supply chain.
The HPAL plant operated by MNEM, with an annual production capacity of 25,000 tons of nickel in MHP is currently operating and has transitioned to the new FPP at the SCM Mine site since Q4 2025. Meanwhile, the third HPAL facility, SLNC, with a planned capacity of 90,000 tons of nickel in MHP per year, was currently under construction and targeted to begin operations in 2026.
p. 45 · Read in context →
The competing RKEF cost line. MBMA reports 73,871 tonnes of nickel in NPI and LGNM for 2025 at a cash cost of US$9,406 per tonne of nickel, from three smelters with 19,000 / 19,000 / 50,000 tpa NiEq nameplate in which it holds 50.1%. NCKL's comparable disclosure for 2025 is roughly 240,000 tonnes per year of installed RKEF capacity and 188,581 tonnes of nickel contained in ferronickel sold. MBMA defines RKEF cash cost as direct cost per tonne of nickel produced including transport; NCKL does not publish a cash cost on that definition, so this is a benchmark for the level the basin operates at rather than a like-for-like margin comparison. Note also the product differs - MBMA sells NPI, NCKL sells higher-grade ferronickel.
The MBMA Group holds a 50.1% ownership in the RKEF Smelter located at IMIP. The RKEF Smelter facilities consist of several units such as CSID, BSID, and ZHN, which process saprolite nickel ore from the SCM Mine to produce NPI.
The CSID and BSID smelters commenced NPI production in 2019 and early 2020, respectively. Both smelters have a production capacity of 19,000 tpa NiEq and has consistently operated at utilization rates exceeding 100%, reflecting high operational efficiency and optimised production capacity. The third smelter, ZHN, began operations in 2023 with an installed capacity of 50,000 tpa NiEq.
Currently, the RKEF Smelter have undergone scheduled maintenance, and NPI production guidance has been revised to 70,000–80,000 tons. In 2025, the MBMA Group produced 73,871 tons of nickel in NPI and LGNM, comprising 72,106 tons of nickel in NPI and 1,765 tons of nickel in LGNM. This production was achieved at a cash cost of US$9,406/tNi.
p. 120 · Read in context →
Nickel Industries Limited (NIC)
ASX-listed but wholly Indonesia-operating, and running the same product straddle as Harita: RKEF nickel units plus a growing HPAL/MHP position, fed by its own laterite mine. It is by some distance the most disclosure-rich peer, publishing per-tonne cash costs, realised contract prices, ore price movements and RKAB quota outcomes - the level at which NCKL's economics can actually be benchmarked. Only the Indonesian nickel operations are used here; the group's financing, remuneration and ESG-award material is left out.
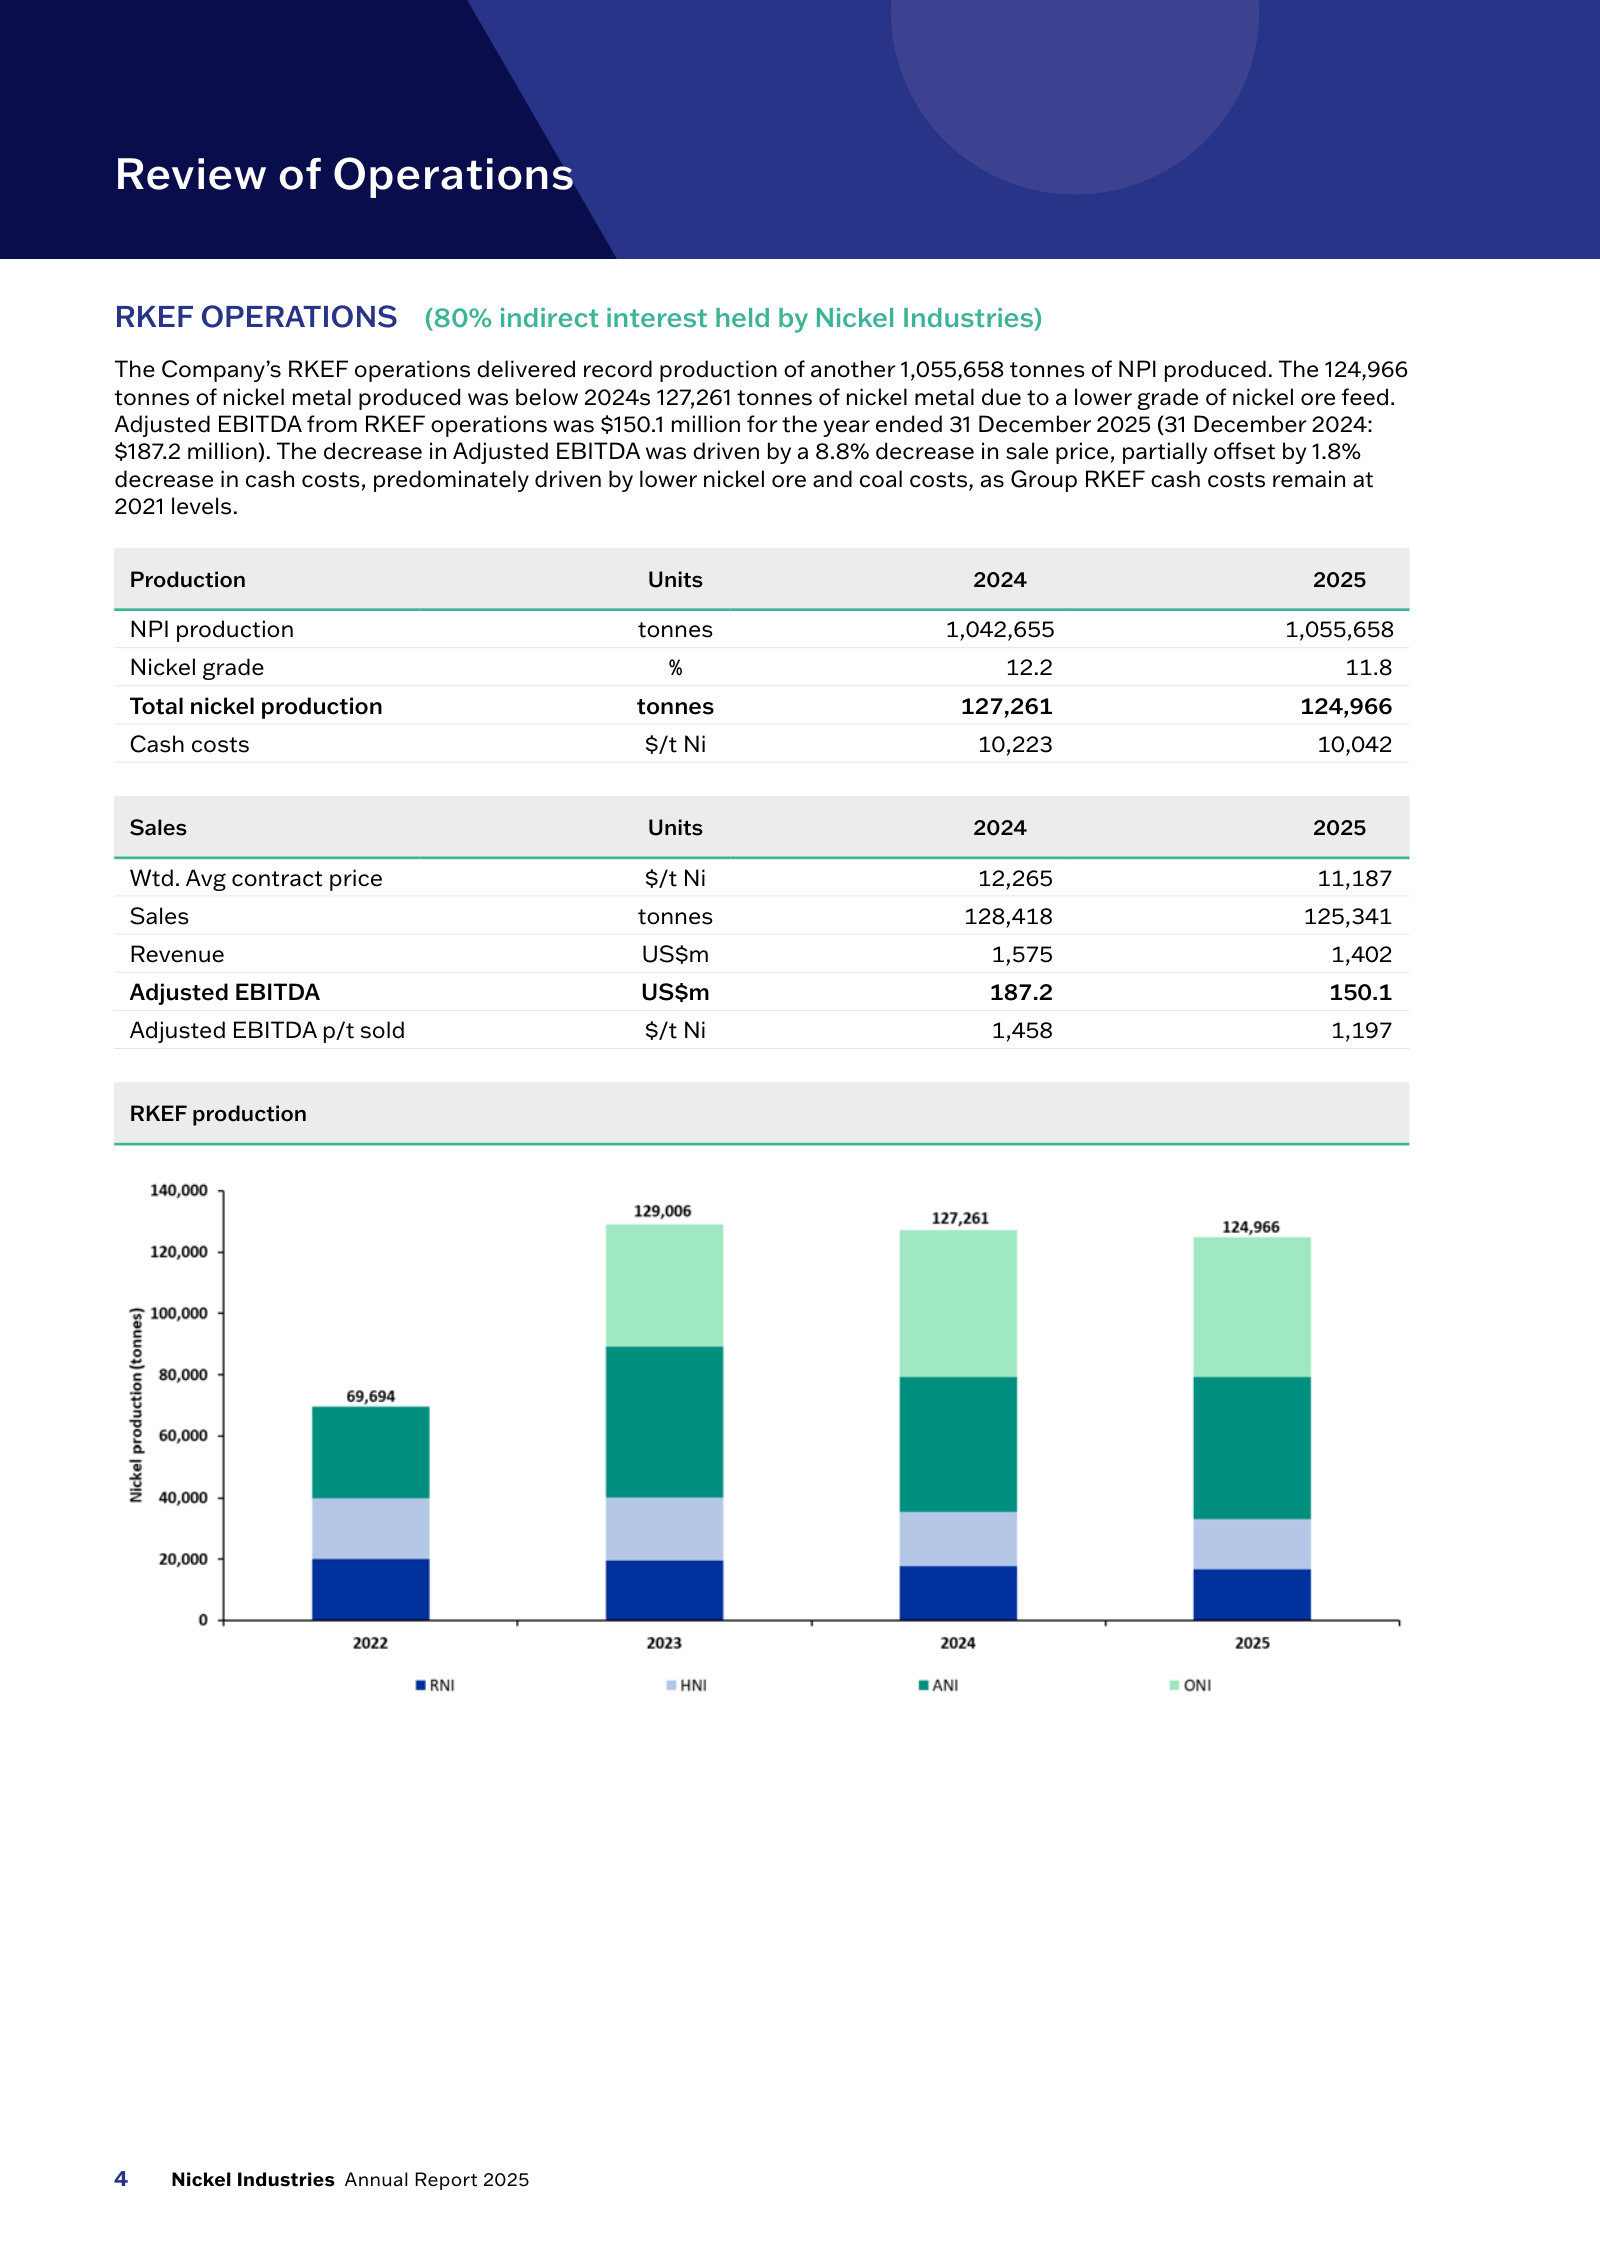
A competitor's operating economics for an Indonesian HPAL plant, at the level NCKL does not disclose. The Huayue plant, in which NIC holds 10%, produced 85,031 tonnes of nickel and 8,023 tonnes of cobalt in MHP - 42% above its 60,000 tpa nameplate on NIC's arithmetic - at cash costs of US$7,765/t Ni, up 9% on higher sulphur costs, against a realised MHP price of US$14,990/t Ni. Sulphur is the input NCKL's own management flags as the swing factor in HPAL cost, and the cobalt credit of about US$1,900/t Ni quantifies the by-product economics that both companies rely on. Cash costs here exclude by-product credits, and the figures are the plant's, reported through a 10% holder.
During the year, the Huayue Nickel Cobalt (HNC) Project produced 85,031 tonnes of nickel and 8,023 tonnes of cobalt in mixed hydroxide precipitate (MHP), outperforming nameplate capacity (60,000 tonnes of nickel per annum) by 42%. Combined operating cash costs increased by 9% year on year, primarily due to higher sulfur costs.
MHP contract prices increased by 8% to US$14,990/t Ni year on year supported by higher metal payability and stronger cobalt prices with the cobalt byproduct increasing to \~US$1,900/t Ni. Adjusted EBITDA for the year of US$6,677/t Ni was 12% higher than US$5,693/t in 2024.
p. 8 · Read in context →
The ore market NCKL sells into and buys from, described by a mine operator in it. Two things are visible: the price divergence - saprolite down 30% on a shrinking local premium while limonite rose 31% because Indonesian HPAL projects are bidding for feed - and the cost of the RKAB quota system, with US$21.3 million of standby charges because the 2025 quota extension did not arrive until 12 December. NCKL sold 30.59 million wmt of nickel ore in 2025 (12.09 saprolite, 18.50 limonite) against Hengjaya's 9.9 million wmt, and is exposed to the same annual quota cycle, though most of NCKL's ore moves to its own plants rather than to third parties. Prices are contract realisations at one mine, not a published index.
The Company’s Hengjaya Mine delivered another year of record production of 19.2 million wmt of nickel ore (15.1 million wmt of limonite and 4.1 million wmt of saprolite), and record sales of 9.9 million wmt under the existing Rencana Kerja dan Anggaran Biaya (RKAB) annual mining quota. The saprolite contract price is based on the Indonesian benchmark price plus a local premium. During the year, the saprolite contract price decreased 30%, driven by a reduction in the local premium. Despite the limonite nickel grade decreasing during the year, the limonite contract price increased 31% due to the increased demand for limonite ore from Indonesian HPAL projects. During the year, the Company experienced substantial downtime and $21.3 million in standby charges at the Hengjaya Mine as the RKAB extension was not granted until 12 December 2025 and consequently the Adjusted EBITDA decreased from $100.9m in 2024 to $91.6m in 2025. Subsequent to the end of the year the Company received an increase in its RKAB quota for 2026 to 14.3 million wmt.
p. 10 · Read in context →
Zhejiang Huayou Cobalt Co., Ltd. (603799)
The largest producer of Indonesian HPAL intermediate - the same product NCKL's HPL and ONC plants make - through the Huayue and Huafei plants at IMIP, with Pomalaa and Sorowako in construction alongside Vale Indonesia. It is also the refining and cathode-material buyer at the other end of the chain, so its disclosures show both how much MHP supply is arriving in the market and who ultimately consumes it. Only the nickel and Indonesia parts of the group are used here; the cobalt, lithium, copper and precursor/cathode businesses appear only where they set demand context.
How the largest Indonesian MHP producer sizes its own market: INSG-sourced global nickel supply of 3.81 million tonnes against demand of 3.6 million tonnes in 2025, a surplus of roughly 210,000 tonnes, with prices in the bottom of the range for most of the year. The competitively significant sentence is the last one - Huayou attributes the late-year price rebound and, more broadly, the global supply-demand balance to expectations around Indonesia's RKAB quota policy. That is a Chinese processor stating that the regulatory mechanism governing NCKL's own mining volumes is now the principal swing variable in the world nickel price.
According to INSG, the global nickel supply was 3.81 million tons and the demand 3.6 million tons in 2025. The nickel price throughout the year was mainly fluctuating within the bottom range due to the mismatch between supply and demand. At the end of the year, it rebounded significantly under the expectation of the tightening of Indonesia’s RKAB quota policy. From the supply side, global nickel production was highly concentrated in Indonesia. Its policy trends such as the RKAB quota have become key variables affecting the global nickel supply and demand balance.
p. 15 · Read in context →
Huayou's stated Indonesian position at the end of 2025: over 1.4 billion wet tonnes of nickel resource locked up through equity and offtake, MHP shipments of 235,000 tonnes from Huayue and Huafei (up 30%), a 120,000 t/yr Pomalaa HPAL plant expected to complete within the year, 60,000 t/yr at Sorowako and a 40,000 t/yr Huaxing RKEF project under construction - plus a whole-chain agreement with ANTAM and IBC. Against NCKL's 130,551 metal tonnes of MHP and nickel sulphate sold in 2025, this is the scale the MHP market is being supplied at by a single competitor. The unit basis of the 235,000-tonne figure is not restated here and the 2024 report used "metal tons" for a comparable intermediates line, so the two years are not a clean like-for-like; the project completion dates are company targets.
In the upstream resource sector, in Indonesia, efforts were made to intensify the development of mining resources. To date, a total of over 1.4 billion wet tons of nickel resources in Indonesia were locked in through various means such as investment, equity participation and underwriting, further consolidating the reserves of nickel and cobalt resources. The two HPAL projects, Huayue and Huafei, maintained stable and exceeded production capacity, achieving an annual MHP shipment of 235,000 tons, a 30% increase compared to the same period of the previous year. The Pomalaa HPAL project with an annual output of 120,000 tons of nickel metal progressed steadily as planned and is expected to be completed before the end of this year. The preparatory work for the Sorowako HPAL project with an annual output of 60,000 tons of nickel metal is proceeding in an orderly manner. The Huaxing RKEF project with an annual output of 40,000 tons of nickel metal has started construction. The construction of the Pomalaa Industrial Park is progressing smoothly and it has been awarded the title of “Important National Industrial Project of Indonesia”. The Company has reached strategic cooperation with ANTAM and IBC to carry out cooperation in the entire industrial chain of new energy vehicle batteries in Indonesia.
p. 18 · Read in context →
The same disclosure one year earlier, which is what makes it useful: plant-by-plant nameplate for the Indonesian HPAL build - Huafei at 120,000 t of MHP, Huayue at 60,000 t, Huake at 45,000 t of nickel matte - and nickel intermediate shipments of nearly 230,000 tonnes, up about 50% year on year. Note the slurry pipeline connecting the SCM mine to Huayue: that is MBMA's mine feeding Huayou's plant, an illustration of how tightly the Sulawesi ore-to-HPAL chain is interlocked compared with NCKL's fully self-supplied Obi Island complex. Both years' shipment figures are Huayou's own and include internally supplied volumes.
At the upstream resource end, in Indonesia, the Company invested in AJB, WKM and TMS mines, further enriching its nickel ore reserves. For the Huafei’s HPAL project with an output of 120,000t mixed hydroxide precipitate, it reached the target output by the end of the first quarter in 2024, the production capacity was gradually improved to achieve stable and over production; for the Huayue’s HPAL project with an output of 60,000t mixed hydroxide precipitat, it continuously exceeded the target output, and pulp pipeline connecting the SCM mine and Huayue project ran through the whole line, further reducing the production cost; Huake’s nickel matte project with an output of 45,000t nickel matte was operated stably; the shipment of nickel intermediates was nearly 230,000t, an increase of 50% over the same period last year.
p. 13 · Read in context →
Eramet SA (ERA)
Through a 38.7% indirect interest in PT Weda Bay Nickel, Eramet is partner in what it calls the world's largest nickel mine, on Halmahera - NCKL's own province of North Maluku - selling saprolite and limonite to the same class of Indonesian processors NCKL feeds internally, and constrained by the same RKAB quotas. Its Universal Registration Document is also the most methodical public account of how the nickel market is structured, with INSG country production tables and explicit MHP and matte volumes that size the market NCKL's HPAL segment sells into. Only the nickel chapters are used; manganese, mineral sands and lithium are excluded.
The clearest public definition of the two markets NCKL straddles, from a producer in both. Class 1 - pure nickel metal and the sulphates made from MHP and matte - was about 26% of 2024 primary nickel production; Class 2 ferroalloys, NPI and ferronickel, about 74%. The figure to carry is 350 kt of MHP produced in 2024 via HPAL in Indonesia, against 140 kt of nickel matte, with both intermediates mainly refined in China. NCKL sold 130,551 metal tonnes of MHP and nickel sulphate in 2025; the comparison is indicative only, since Eramet's number is 2024, is a production rather than sales figure, and NCKL's includes downstream sulphate. Eramet's stated MHP specification - 20 to 25% nickel and 5 to 10% cobalt - is also the payability basis on which NCKL's MHP is priced.
There are two categories of primary nickel:
• Class 1, pure nickel metal: mainly includes electrolytic nickel, powders and nickel briquettes. […] This class is usually associated with nickel salts, including nickel sulphates (NiSO ), which are mainly used in the production of precursors for active materials for the cathodes of lithium-ion batteries. With the boom in the electric vehicles sector, production of the above has expanded significantly. These are mainly manufactured from intermediate products such as MHP (Mixed Hydroxyde Precipitate) and nickel matte, and marginally by the dissolution of briquettes.
MHP is an intermediate product containing 20 to 25% of nickel and 5 to 10% of cobalt, and its production uses the HPAL (High Pressure Acid Leach) hydrometallurgical process, which is growing strongly in Indonesia, with 350 kt produced in 2024. The production of nickel matte has also increased in recent years, thanks to the NPI (Nickel Pig Iron) conversion process in Indonesia, representing 140 kt in 2024. These two intermediates are mainly refined in China.
In 2024, Class 1 represented around 26% of total primary nickel production;
• Class 2, nickel ferroalloys: this category mainly includes NPI and ferronickel, produced by pyrometallurgy and intended for the stainless steel market. These products are not qualified to be delivered in LME warehouses. In 2024, this class represented around 74% of global production of primary nickel, following the exponential growth of NPI in Indonesia and the dominance of stainless steel in the end use of nickel.
p. 76 · Read in context →
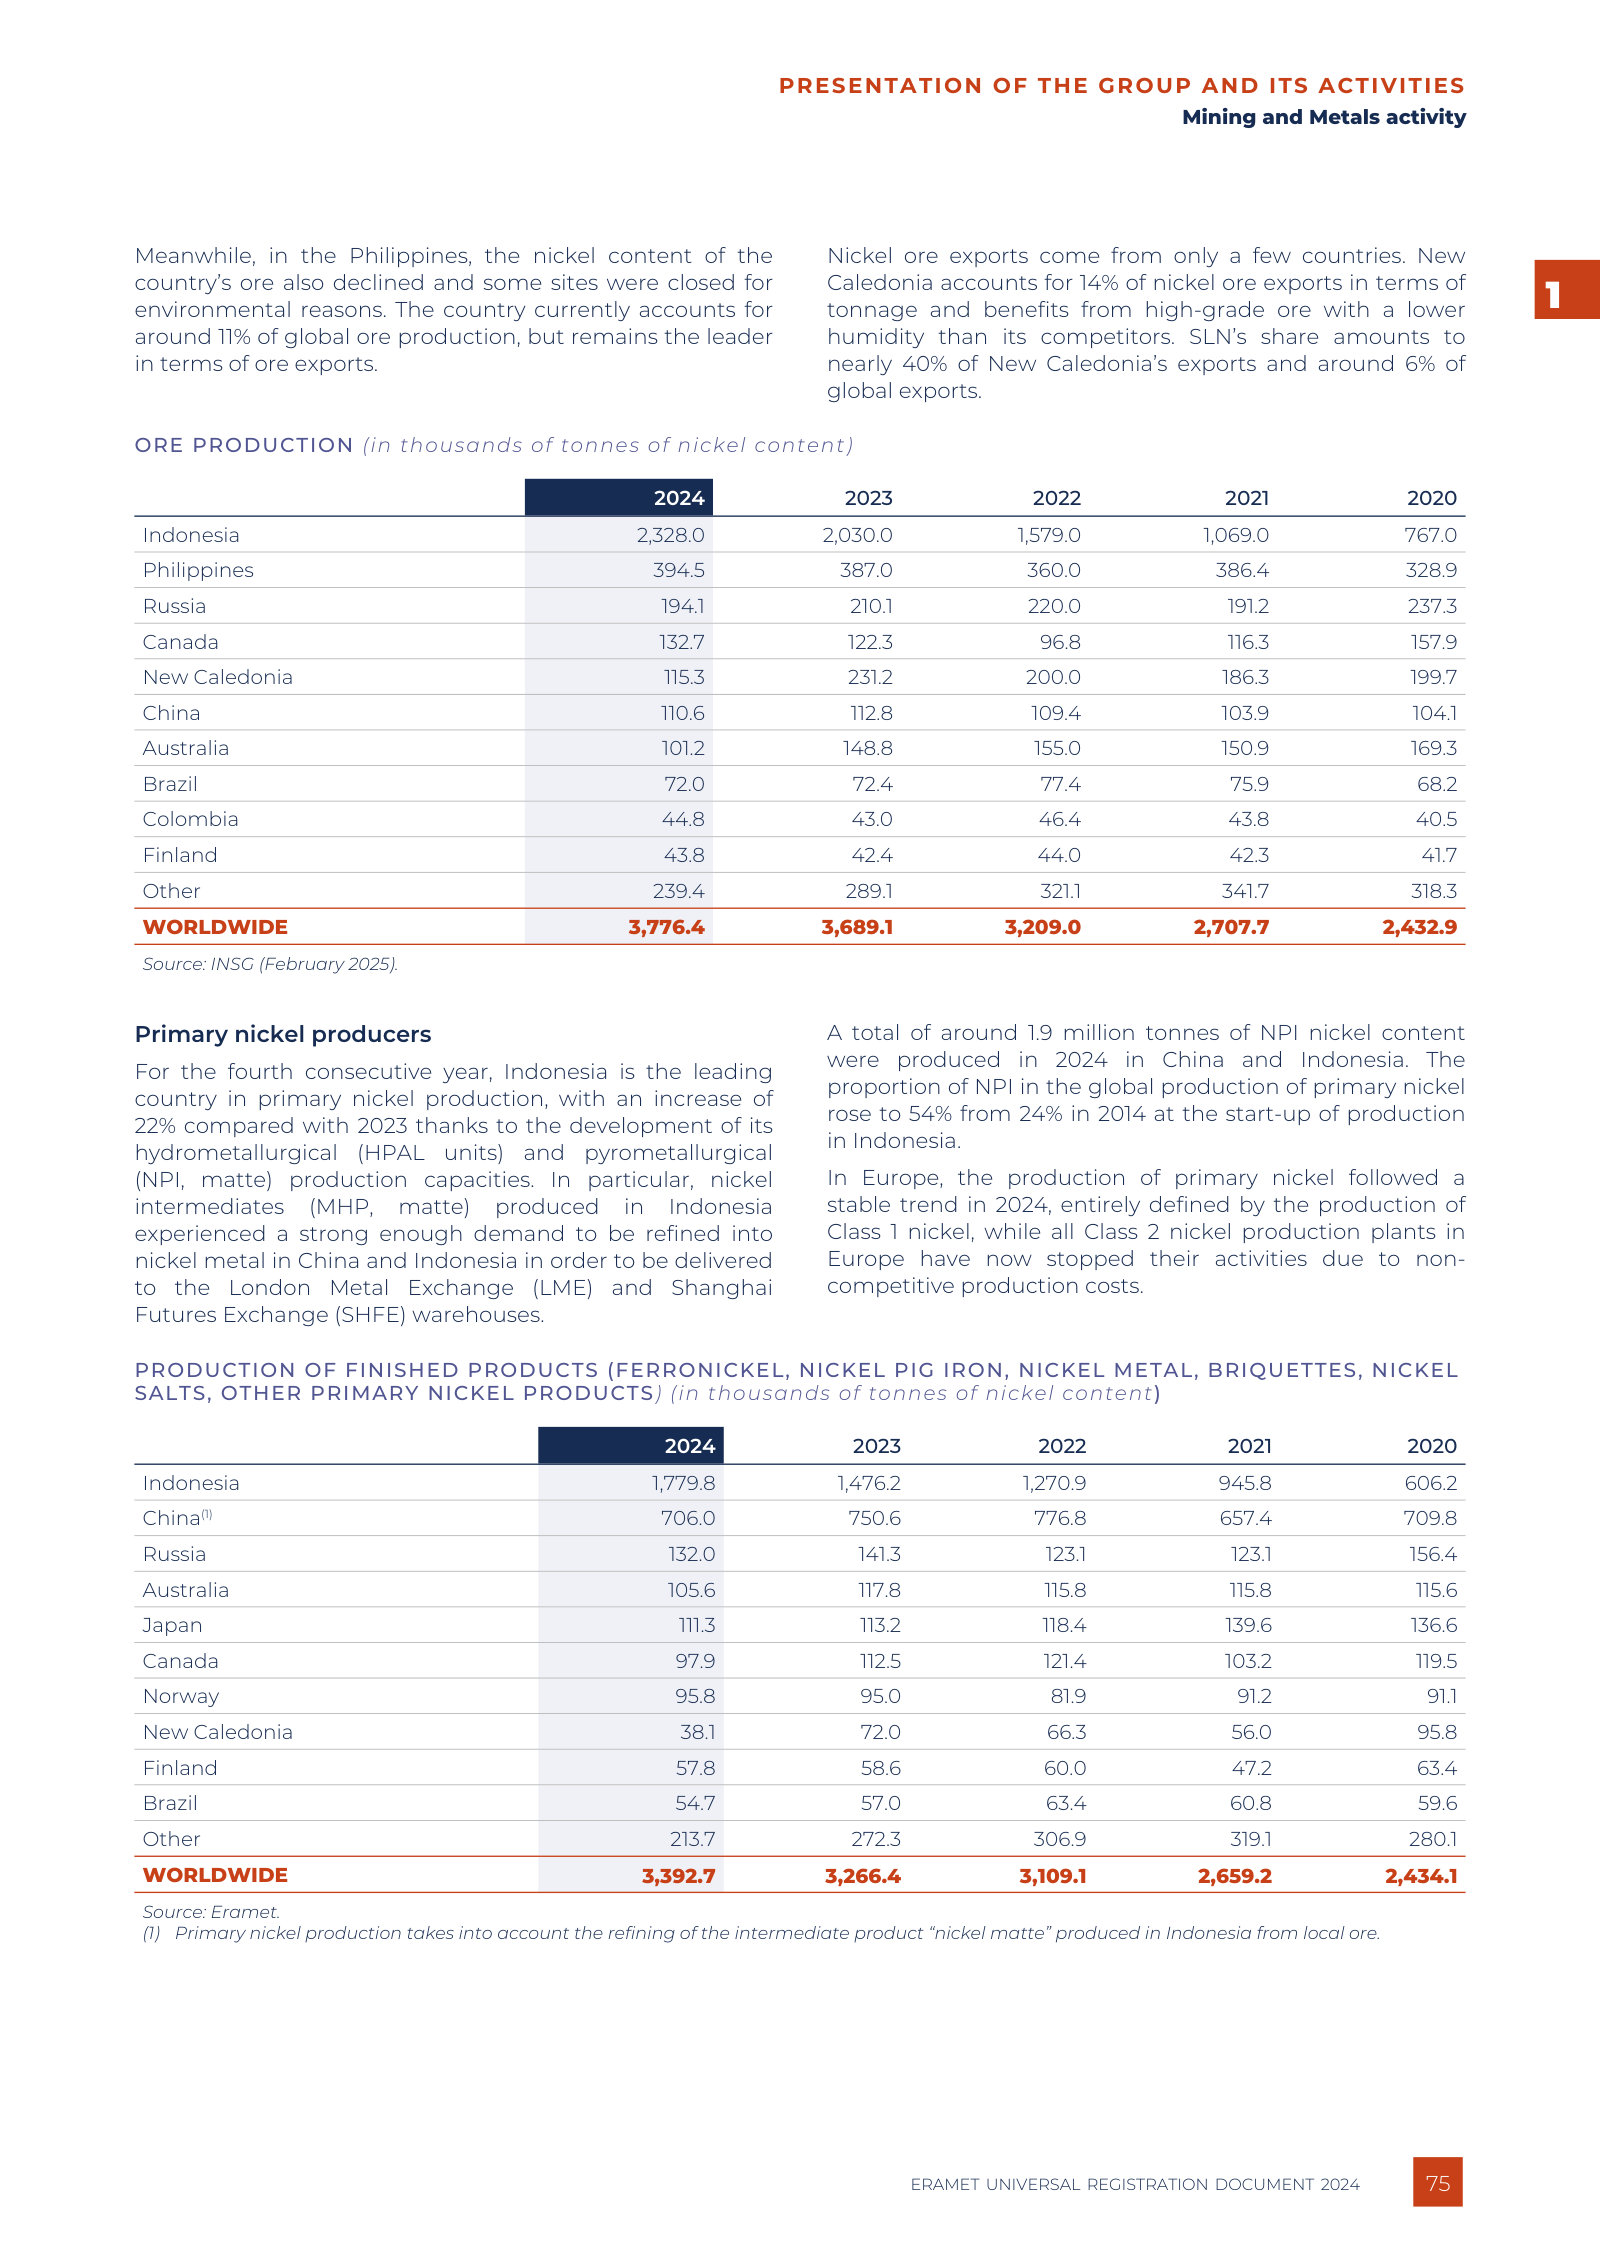
The ore-supply competitor's own strategy statement. Eramet puts nickel demand growth at 6% a year to 2027 with stainless steel about two-thirds of use, and positions Weda Bay in the first quartile of the cost curve, selling saprolite and laterite to local Class I and Class II producers. The volume numbers are the competitive point: 32 Mwmt permitted for 2025 - explicitly the ceiling of the current RKAB - with an ambition, agreed with partner Tsingshan and permitted under the 2024 AMDAL, to reach roughly 60 Mwmt a year, two-thirds saprolite. NCKL sold 30.59 Mwmt of nickel ore in 2025, so Weda Bay's current permitted volume is comparable to Harita's entire ore business and its stated ambition is roughly double it. "First quartile of the cost curve" is Eramet's own positioning claim, unquantified here.
Nickel demand is expected to increase by 6% (²)(average annual growth rate) over the 2024-2027 period, buoved by the resilient growth of stainless steel (which constituted about two-thirds of applications in 2024) and surging battery demand.
In this context, Eramet and its partner Tsingshan are developing the PT Weda Bay Nickel mine, which is positioned in the first quartile of the cost curve and supplies ore (saprolite and laterite) to local Class I and Il nickel producers. In accordance with the authorisations granted in October 2024 by the Indonesian Ministry of Mines. it is expected that
32 Mwmt of nickel ore will be marketed in 2025 - the limit of the current operating permits - with priority given to saprolites over laterites (whose nickel content is lower)
With its partner, the Group is still working to increase the mine's capacity to around 60 Mwmt per year, around two-thirds saprolites and around one-third laterites. in accordance with the environmental permit and the new long-term mining plan approved by the Indonesian authorities in the summer of 2024.
p. 18 · Read in context →
More peer documents
PT Merdeka Battery Materials Tbk - 2024 Annual Report — FY2024 · 424 pages · The prior-year baseline for the same disclosures used above: SCM ore volumes before the limonite ramp, RKEF cash costs of US$10,307/t Ni, and the HPAL pipeline as it stood before PT ESG began selling MHP. · Open →
Eramet - 2025 Integrated Report — FY2025 · 44 pages · The current-year Eramet update (French only, 44 pages): 42 Mwmt of marketable nickel ore at Weda Bay, the reaffirmed first-quartile positioning and 60 Mt/yr capacity goal, and a forecast of 9-12% annual growth in Class 1 battery nickel demand to 2040. · Open →
Source: S&P Capital IQ consensus via Xpressfeed · Generated 2026-08-03.
Consensus Tape
The forward tape has been moving one way. FY2027 revenue consensus sits 15.6% above where it was six months ago and FY2027 normalized EPS 15.9% above, with both still edging up in the past month. The company has beaten the revenue consensus in all seven quarters this feed captures one for, by 6.7% to 16.7%. The ratings are unanimous — nine buys, three outperforms, nothing else — but the estimates behind them thin out fast past FY2027.
FY2027 Revenue Consensus (IDR bn)
FY2027 EPS, Normalized (IDR)
FY2027 EPS Revision, Six Months
Straight Revenue Beats
Source: derived from vendor data.
FY2027 estimates are ~16% higher than six months ago — revenue and EPS alike
Source: derived from vendor data.
Six months ago the street carried FY2027 revenue at IDR 32,797bn and normalized EPS at IDR 184.80. Today it carries IDR 37,927bn and IDR 214.21 — up 15.6% and 15.9%. Almost all of that arrived between the three-month mark and the one-month mark: revenue is up 11.0% over three months but only 0.2% over the past month, and EPS up 8.8% then 2.0%. Both lines moved by nearly the same proportion, so this reads as a top-line revision carried down to earnings rather than a change in what the street assumes about margin. FY2028 has no history beyond one month in this feed, and has not moved within it.
Seven revenue prints, seven beats — the street is behind the top line
Source: derived from vendor data.
Every revenue print in the record beat: the smallest by 6.7% in 3Q24, the largest by 16.7% in 2Q25, and the last five all in double digits. EPS is noisier — five beats in six priced quarters, including 55.7% in 4Q24 and 36.2% in the most recent print, against one miss. That miss, 3Q25 at -30.6%, rested on a single analyst's IDR 53.62 estimate while the same quarter's revenue still beat by 10.4%; it says more about a thin quarterly EPS sample than about the quarter. The 1Q25 print, reported at IDR 26.27, carries no captured consensus and so sits outside the record.
Read together with the section above, the two signals agree rather than conflict: the street is raising numbers and still being beaten on the top line.
FY2027 is a pause year across every line the street models
Source: derived from vendor data. FY2025 levels are reported actuals; later years are consensus means.
Consensus revenue steps up 24.8% in FY2026 to IDR 36,979bn, then stalls at 2.6% in FY2027 before reaccelerating to 11.1% in FY2028. EBITDA follows the same profile at 27.5%, 6.3% and 14.6%, and EPS at 33.9%, 12.6% and 16.1%. The pause is therefore in the whole P&L, not in one line of it — and it is worth noting the FY2027 revenue mean is the number that has been revised hardest upward, so the flat year is flat against a FY2026 base that also rose. Earnings outgrow revenue in each year, consistent with the gross margin the street carries: 32.3% for FY2025 rising to 39.7% by FY2028.
The FY2027 EBITDA range is IDR 10,947bn to IDR 18,211bn on nine estimates
Source: derived from vendor data.
The FY2027 EBITDA mean of IDR 13,976bn sits inside a range running from IDR 10,947bn to IDR 18,211bn — the high is around two-thirds above the low, on nine estimates. That is real disagreement about the earnings power of the forward book, not rounding. Revenue is tighter in proportion, and EPS expresses the same argument per share.
Source: derived from vendor data.
Note where the counts fall away: eight to ten contributors on FY2026 and FY2027, four to five on FY2028. The widening of the range in the outer year is partly disagreement and partly the arithmetic of a smaller sample.
Cash turns net-positive by FY2027, and the payout ramps with it
Source: derived from vendor data. Currency amounts in IDR bn; dividend per share in IDR.
Source: derived from vendor data.
Consensus has operating cash flow at IDR 12,608bn for FY2025 rising to IDR 14,953bn by FY2028, against capex held between IDR 1,483bn and IDR 1,901bn a year. Net debt of IDR 7,412bn in FY2025 becomes net cash of IDR 6,687bn in FY2027 and IDR 14,295bn in FY2028 on these means, and the dividend rises with it, from IDR 34.62 per share for FY2025 to IDR 84.86 for FY2028. One caveat carries across this whole section: none of these lines carries an analyst count in the feed, so they are means over an unstated and probably small sample — treat them as directional, not as the same quality of consensus as revenue and EPS.
Eleven targets spanning IDR 1,200 to IDR 1,900, and not one hold
Source: derived from vendor data.
Eleven price targets run from IDR 1,200 to IDR 1,900, with a mean of IDR 1,631 and a median of IDR 1,594 — the mean above the median, so the spread is skewed by the top of the range rather than the bottom. The rating mix carries none of that dispersion: nine buys, three outperforms, no hold, sell or underperform anywhere in the set. This feed carries no share price, so nothing here implies an upside or a downside; the targets are useful only as a measure of how wide the band the street is underwriting has become.